Quick ratio
Learn what the quick ratio shows, how to calculate it in S$ and what a healthy result looks like for your business.
February 2024 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- The quick ratio shows whether your business can pay its short-term debts using only cash, marketable securities and money customers owe you
- A quick ratio of 1.0 or higher generally means you can meet upcoming bills without selling stock or borrowing
- The quick ratio leaves out inventory and prepaid expenses, so it gives a stricter view of liquidity than the current ratio
- Checking your quick ratio monthly helps you spot cash pressure early and act before bills fall due
What is the quick ratio?
The quick ratio is a financial metric that shows whether your business has enough liquid assets to pay its current liabilities right now. It’s also called the acid test ratio.
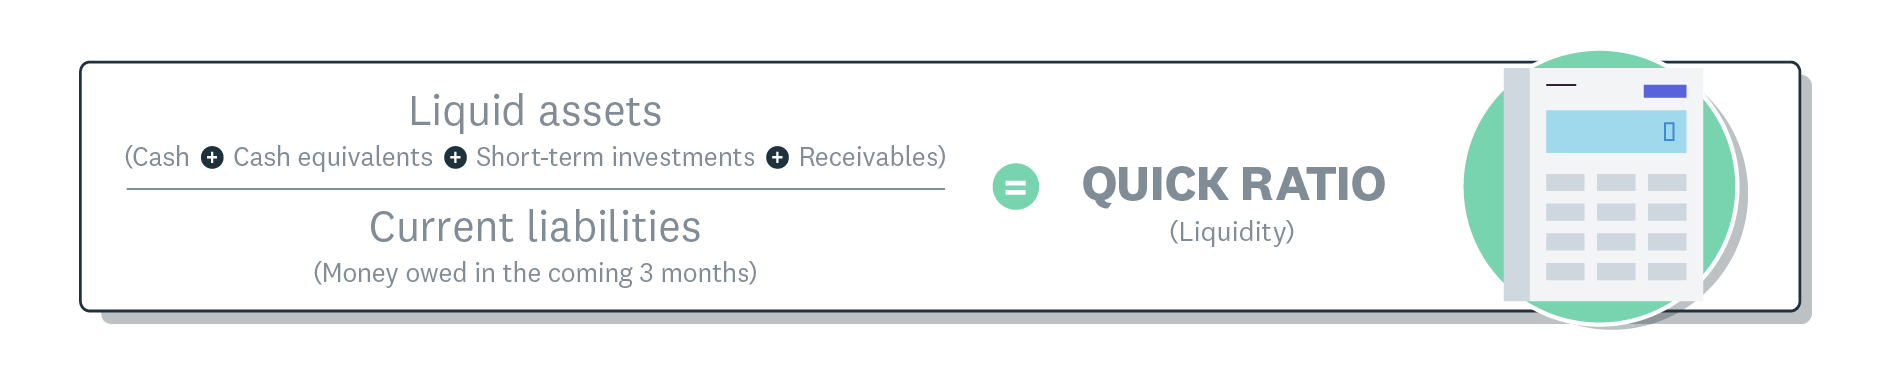
Quick ratio formula Version 1.
The ratio only counts assets you can turn into cash quickly. That means it strips out slower-moving assets such as inventory and prepaid expenses.
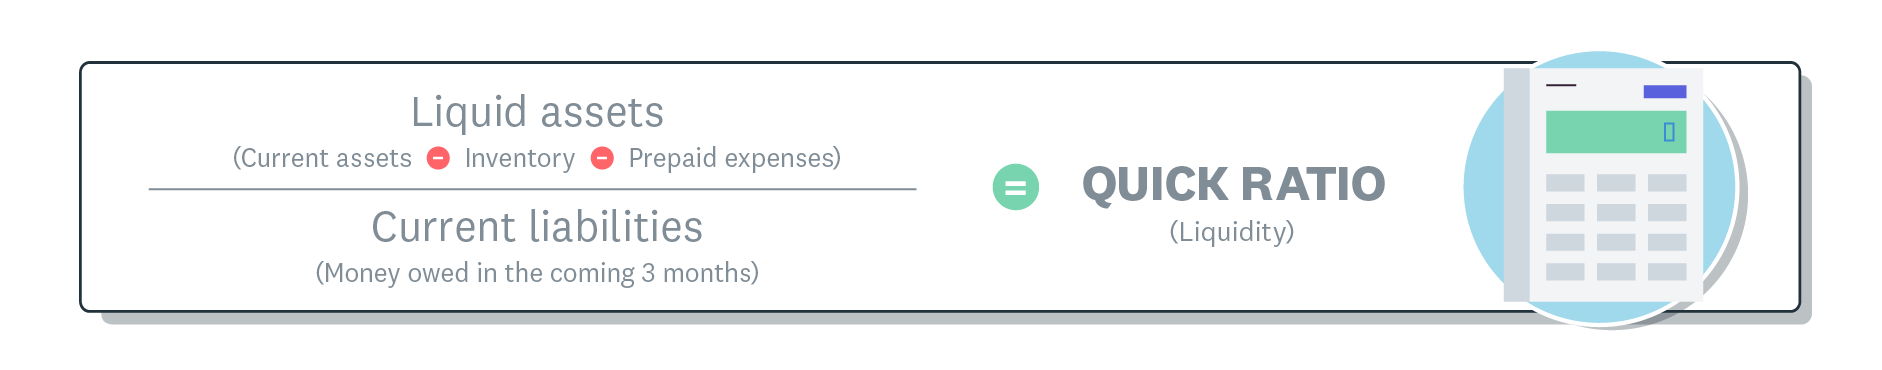
Quick ratio formula Version 2.
Think of it as a stress test: if every supplier and lender asked to be paid this quarter, could you pay without touching your stock? For small business owners, it’s a realistic snapshot of your ability to cover bills and loan repayments with the cash you can reach.
How to calculate the quick ratio
You calculate the quick ratio by dividing your quick assets by your current liabilities. There are two common ways to write the formula, and both give the same result.
Formula 1: Quick ratio = (cash + marketable securities + net accounts receivable) ÷ current liabilities
Formula 2: Quick ratio = (current assets minus inventory minus prepaid expenses) ÷ current liabilities
The first formula adds up your liquid assets directly. The second starts with total current assets and subtracts the items you can’t quickly convert to cash.
Follow these steps to work out your own quick ratio:
- Open your balance sheet for the date you want to check
- Add up your cash, marketable securities and net accounts receivable
- Total your current liabilities
- Divide your quick assets by your current liabilities
Quick ratio example in S$
Say your balance sheet shows S$50,000 in cash, S$10,000 in marketable securities and S$40,000 in net accounts receivable. You also hold S$30,000 of inventory, which you leave out, and you owe S$80,000 in current liabilities.
Quick ratio = (S$50,000 + S$10,000 + S$40,000) ÷ S$80,000 = S$100,000 ÷ S$80,000 = 1.25
A quick ratio of 1.25 means you have S$1.25 in liquid assets for every S$1 of short-term debt. You could cover all your current liabilities and still keep a buffer.
Components of the quick ratio
The quick ratio uses specific asset and liability categories from your balance sheet. Knowing what goes in, and what stays out, helps you calculate it accurately.
Assets included
The quick ratio only counts assets that are already cash or close to it. These are often called quick assets or liquid assets.
- Cash and cash equivalents, such as bank balances, petty cash and term deposits maturing within three months
- Marketable securities, such as shares or government bonds you can sell on an exchange at any time
- Net accounts receivable, which is what customers owe you minus any amount you expect to write off
Liabilities included
Current liabilities are debts and obligations due within the next 12 months. Include any Goods and Services Tax (GST) and Central Provident Fund (CPF) amounts you owe, as leaving them out inflates your ratio.
- Accounts payable owed to suppliers
- Short-term loans and credit card balances
- Corporate income tax and any GST payable (if you’re GST-registered) due within the year
- Employee wages and CPF contributions payable
- The current portion of any long-term debt
What’s excluded
The quick ratio leaves out assets that take longer to turn into cash. Inventory is excluded because selling stock can take weeks or months, and a rushed sale may bring in less than it’s worth.
Prepaid expenses, such as insurance or rent paid in advance, are also excluded. You’ve already spent that money, so it can’t be used to pay other bills.
What is a good quick ratio?
A quick ratio of 1.0 or higher is generally healthy. It means you have at least S$1 in liquid assets for every S$1 of short-term debt, so you can meet your obligations without selling inventory.
Here’s how to read some common results:
- A ratio of 0.75 means you have 75 cents in liquid assets for every S$1 you owe, so sales or financing must cover the rest
- A ratio of 1.0 means your liquid assets exactly cover your current liabilities, with no buffer
- A ratio of 1.5 gives you S$1.50 for every S$1 owed, which leaves comfortable room for surprises
- A ratio above 2.0 shows strong liquidity, though some of that cash could be reinvested in growth
What counts as good also depends on how your business earns money. A consulting firm or design agency carries little stock, so its quick ratio sits close to its current ratio and tends to be higher. A retailer or distributor holds more inventory, so a lower quick ratio can still be sound if stock sells steadily.
Seasonal businesses see their ratio swing through the year. A festive hamper seller building stock before Chinese New Year will see its quick ratio dip, then recover as sales come in. Compare the same month year on year, and benchmark against businesses similar to yours.
What the quick ratio means for your business
Your quick ratio tells you whether you could pay all your short-term debts today using only your most accessible assets. It’s a practical check on how well your business could absorb a sudden bill or a slow month.
Lenders and investors often look at the quick ratio when deciding whether to extend credit. A ratio that stays above 1.0 shows you manage cash well and can meet obligations without relying on inventory sales.
A ratio below 1.0 is a prompt to look closer. It could point to generous credit terms for customers or heavy short-term debt. Reading it alongside your working capital position shows how much room you have day to day.
Tracking the ratio each month gives you early visibility into cash flow gaps. You can then chase overdue invoices or renegotiate supplier terms while you still have time to act.
Quick ratio vs current ratio
The quick ratio and the current ratio both measure short-term liquidity. They differ in which assets they count as available to pay debts.
The current ratio includes all current assets: cash, receivables, inventory, prepaid expenses and anything else you expect to use or convert within 12 months. Its formula is:
Current ratio = current assets ÷ current liabilities
The quick ratio is more conservative. By removing inventory and prepaid expenses, it only counts assets you can realistically turn into cash at short notice.
A business can have a high current ratio and a low quick ratio at the same time. Picture a homeware shop with S$120,000 in current assets, including S$80,000 of stock, and S$60,000 in current liabilities. Its current ratio is a healthy-looking 2.0, but its quick ratio is 0.67, because most of its liquidity sits on the shelves.
Use the current ratio for a broad view of your short-term finances. Use the quick ratio for a stricter test of how fast you can pay debts. Together with the cash ratio, they make up the main liquidity ratios small businesses track.
Pros and limitations of the quick ratio
The quick ratio is simple and useful, but it’s one number from one point in time. Knowing its strengths and blind spots helps you decide when to rely on it.
What the quick ratio does well
The quick ratio gives you a fast, cautious read on liquidity. These are its main advantages:
- Gives a conservative view of liquidity by leaving out stock and prepayments
- Uses figures already on your balance sheet, so it takes minutes to calculate
- Offers lenders and investors a familiar figure when you apply for credit
- Flags cash pressure early when you track it every month
Limitations to keep in mind
The quick ratio works best alongside other measures. Watch for these gaps when you read it:
- Ignores when cash comes in and goes out, a gap highlighted by the Corporate Finance Institute
- Assumes customers will pay their invoices on time
- Treats all stock as slow to sell, even fast-moving products
- Covers short-term liquidity only, so check your long-term solvency separately
How to improve your quick ratio
You can strengthen your quick ratio by increasing your liquid assets or reducing your short-term liabilities. These five steps cover both sides.
1. Speed up your receivables
The sooner customers pay, the more cash you have on hand. Send invoices as soon as the work is done and set a routine for chasing late payments.
Offering online payment options such as cards or bank transfers makes it easier for customers to pay as soon as the invoice lands.
2. Reduce short-term liabilities
Look for chances to pay down short-term debt or negotiate longer payment terms with suppliers. Converting a short-term loan into a longer-term facility moves it out of current liabilities, which lifts your ratio.
3. Build your cash reserves
Set aside a fixed share of your revenue in a separate operating or savings account. Small, regular transfers add up and give you a buffer for lean months.
4. Manage inventory more efficiently
Inventory sits outside the quick ratio, but excess stock ties up cash you could hold instead. Order closer to actual demand and clear slow-moving lines to release that cash.
5. Monitor your ratio regularly
Check your quick ratio monthly or quarterly, instead of once at year end. Real-time financial reports let you spot trends early and adjust before a dip becomes a problem.
Track your quick ratio with Xero
Your quick ratio is most useful when the numbers behind it are up to date. Xero bank feeds bring your transactions in automatically, and real-time reports show your cash and receivables against what you owe as the figures change.
You can pull up your balance sheet any time to check the figures that feed your ratio, then share them with your accountant straight away. Try Xero and get one month free to see where your business stands.
FAQs on quick ratio
Here are answers to common questions about the quick ratio and related metrics.
Is the quick ratio the same as the acid test ratio?
Yes, they’re two names for the same formula. If a bank asks for your acid test ratio, give them your quick ratio.
Is a higher quick ratio always better?
A very high ratio can mean cash is sitting idle, and it can also point to a large receivables balance that’s slow to collect. Check your receivables ageing before reading a high ratio as good news.
What happens if a business has a quick ratio below 1?
Your business depends on selling stock or bringing in new cash to cover every bill as it falls due. Review when incoming payments are due against your upcoming bills, and talk to an accountant before taking on new debt.
How does the quick ratio differ from the cash ratio?
The cash ratio only counts cash and cash equivalents, leaving out receivables and marketable securities. In the worked example, the cash ratio would be S$50,000 ÷ S$80,000, or about 0.63.
Where do you find the figures for the quick ratio?
Cash, marketable securities, receivables and current liabilities all sit in the current assets and current liabilities sections of your balance sheet. Accounting software keeps those figures up to date, so you can work out the ratio whenever you need it.
Related terms
Learn more about quick ratio
Handy resources
Advisor directory
You can search for experts in our advisor directory.
Balance sheet template
See where and how assets and liabilities are reported.
Push-button liquidity reporting
Check your current ratio whenever you like with Xero’s accounting dashboard.
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.