What is liquidity? Definition, ratios and examples
Liquidity shows whether your business can pay its bills on time. Learn how to measure and improve it.
Published Wednesday 30 September 2026
Table of contents
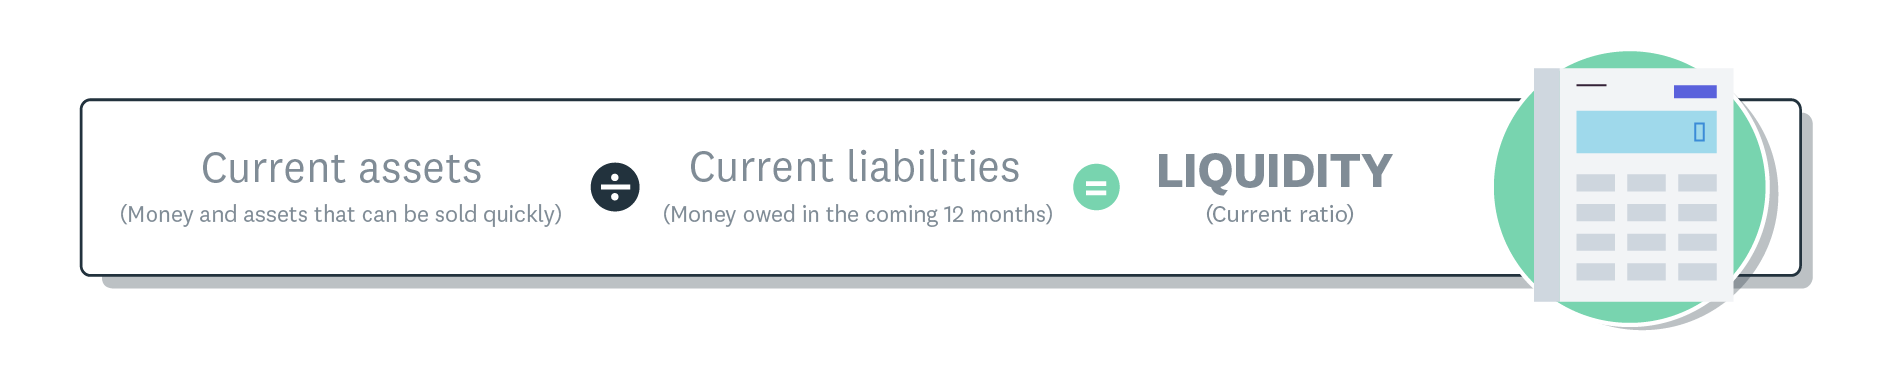
Current ratio liquidity formula.
Key takeaways
- Liquidity is how easily your business can pay the bills due in the next 12 months. It's usually shown as a ratio of current assets to current liabilities.
- The current ratio is the most common measure for small businesses. The quick ratio and cash ratio give a stricter view by leaving out less liquid assets.
- A current ratio of 1.0 or above generally means you can cover your short-term debts. Checking it on the same day each month shows which way it's trending.
- You can improve liquidity by collecting receivables sooner and planning ahead with a cash flow forecast. Liquidity and profit are different, so a profitable business can still run short of cash.
What is liquidity?
Liquidity is how quickly and easily you can turn assets into cash. For a business, it measures your ability to pay bills and loan repayments due in the coming months.
You work it out by comparing current liabilities, the amounts you owe within the next 12 months, with current assets. Current assets include cash, inventory, money customers owe you (receivables) and anything else you could sell quickly.
Think of liquidity like the credit on your transit card. Topped-up credit gets you through the gantry straight away, while a watch in your drawer has value but can't pay today's fare.
Liquid vs illiquid assets
Liquid assets turn into cash quickly without losing much value. Illiquid assets take longer to sell, or may only sell at a discount.
Here are common business assets in order of liquidity, starting with the most liquid:
- Cash in the bank is ready to use straight away
- Short-term investments, such as fixed deposits, can usually be withdrawn quickly, sometimes with a penalty
- Accounts receivable become cash once customers pay their invoices
- Inventory needs to be sold first, which can take weeks or months
- Fixed assets, such as equipment and property, can take months to sell
The first four count as current assets. Fixed assets add to your business's value, but they won't help you pay next month's bills.
Why liquidity matters for your business
Good liquidity means you can pay what you owe on time, even when sales dip for a while. It keeps daily operations running and gives you room to act on opportunities.
Healthy liquidity helps you:
- pay suppliers and staff on schedule
- cover surprise costs, such as an equipment repair, without borrowing at short notice
- show lenders and landlords that your business is a reliable bet
- take up opportunities, like a bulk-buy discount from a supplier
Watching your liquidity also lets you spot a cash squeeze weeks before it arrives. That gives you time to act while you still have options.
How to measure liquidity
You measure liquidity with ratios that compare what you own in the short term with what you owe. The current ratio is the most common for small businesses, while the quick ratio and cash ratio set a stricter test.
Each ratio uses figures from your balance sheet. The liquidity ratios guide covers each formula in more depth.
Current ratio
The current ratio compares all your current assets with all your current liabilities. It's the broadest measure because it includes inventory and prepaid expenses.
Current ratio = current assets ÷ current liabilities
For more practice, try these worked current ratio examples.
Quick ratio
The quick ratio, also called the acid test ratio, counts only assets you can turn into cash within about three months. It leaves out inventory and prepaid expenses, which are harder to spend.
Quick ratio = (cash + cash equivalents + short-term investments + receivables) ÷ current liabilities
You can also work it out as (current assets − inventory − prepaid expenses) ÷ current liabilities.
Cash ratio
The cash ratio is the strictest test. It asks whether you could pay every current liability today using only cash and cash equivalents.
Cash ratio = (cash + cash equivalents) ÷ current liabilities
A cash ratio below 1.0 can still be healthy if customers pay reliably, because their payments will top up your bank balance.
A worked example
Here's how the ratios look for a small café in Singapore at the end of the month. The owner takes these figures from the café's balance sheet.
The café has S$18,000 in the bank, S$4,000 owed by corporate catering clients, S$6,000 of coffee beans and other stock, and S$2,000 in prepaid rent. That's S$30,000 of current assets.
Its current liabilities total S$20,000: S$9,000 in supplier bills, S$7,000 in wages and S$4,000 in loan repayments due this year. Putting these figures into each formula shows that:
- the current ratio is 1.5 (S$30,000 ÷ S$20,000)
- the quick ratio is 1.1 (S$22,000 ÷ S$20,000), after removing S$6,000 of stock and S$2,000 of prepaid rent
- the cash ratio is 0.9 (S$18,000 ÷ S$20,000)
The café can comfortably cover its short-term bills. Its cash ratio shows it relies on catering clients paying on time to close the S$2,000 gap.
What your liquidity ratio tells you
Your liquidity ratio shows whether your short-term resources can meet your short-term obligations. The higher the number, the bigger your buffer.
Use these rough guides to read your current ratio:
- below 1.0 means current liabilities exceed current assets, which can be fine for a short time while you invest in growth
- 1.0 or above generally means your business can cover its short-term debts
- about 1.5–2.0 is often seen as a comfortable buffer
- well above 3.0 may mean cash is sitting idle when it could fund growth or pay down debt
These benchmarks vary by industry. A retailer holding lots of stock will look different from a consultancy with almost no inventory, and most businesses aim to keep their ratio above 1.0 over the long run.
Your ratio also moves with your billing cycle. Measure it on the same day each month and compare like for like to see whether liquidity is trending up or down.
How to improve liquidity
Improving liquidity means bringing cash in sooner and timing what goes out. Work through these steps to strengthen your position:
- Invoice as soon as the work is done and set up automatic payment reminders
- Offer more ways to pay, such as PayNow or card, so customers can settle quickly
- Agree supplier payment terms that line up with when your customers pay you
- Keep stock lean by reordering based on what actually sells
- Sell equipment you rarely use to free up cash
- Review your ratios each month to check the changes are working
A rolling cash flow forecast ties these steps together. It shows when money will come in and go out, so you can plan for tight weeks early.
Liquidity vs working capital, free cash flow and cash flow
Liquidity, working capital, free cash flow and cash flow all describe your spending power, but each answers a different question. Knowing the difference helps you choose the right measure for each decision.
In short:
- cash flow is the movement of money into and out of your business over a period
- liquidity shows how easily you can cover upcoming costs, expressed as a ratio
- working capital is the dollar amount left after current assets cover current liabilities
- free cash flow is the cash left after you've paid for capital investments, such as new equipment
For example, the café above has S$10,000 of working capital (S$30,000 − S$20,000) and a current ratio of 1.5. Both figures come from the same balance sheet, and this guide to working capital explains how to manage it day to day.
Keep track of your liquidity with Xero
Liquidity is easier to manage when your numbers are current. Xero turns your accounts into easy-to-read financial reports, including a balance sheet with the current assets and liabilities behind each ratio.
Bank feeds keep your figures up to date, and short-term cash flow forecasts show what's coming in and going out. Try Xero and get one month free to see your liquidity at a glance.
FAQs on liquidity
Here are quick answers to common questions about liquidity.
What is an example of liquidity?
Cash in your business bank account is the most liquid asset you have. A delivery van is far less liquid, because selling it takes time and may mean accepting a lower price.
Is liquidity the same as solvency?
Liquidity covers the next 12 months, while solvency is about whether your total assets can meet all your debts over the long term. A property-rich business can be solvent yet still short of cash, as this look at solvency and liquidity explains.
What is a good liquidity ratio?
It depends on how quickly your customers pay you. A café paid at the till can safely run closer to 1.0 than a wholesaler that waits weeks for invoices to clear.
Can a profitable business have poor liquidity?
Yes, if customers pay slowly or your profit is tied up in stock and equipment, you can report a profit and still struggle with this month's bills. Tracking profitability ratios alongside liquidity gives you the fuller picture.
What does liquidity mean in trading?
In trading, liquidity is how easily an asset such as a share can be bought or sold without moving its price. Assets with many active buyers and sellers are highly liquid, so trades happen quickly at a price close to the last one.
Related terms
Learn more about liquidity
Handy resources
Advisor directory
You can search for experts in our advisor directory
Xero Small Business Guides
Discover resources to help you do better business
Online accounting with Xero
Automate your accounting in the cloud
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.