Quick ratio vs current ratio
Compare the quick ratio and current ratio, how to calculate each, and what your results say about liquidity.
February 2024 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- The current ratio compares all current assets with current liabilities to show whether you can cover debts due within a year
- The quick ratio, or acid-test ratio, leaves out inventory and prepaid expenses for a stricter view of your short-term position
- Healthy results vary by industry, though a current ratio of 1.5–3.0 and a quick ratio around 1.0 are common rules of thumb
- Tracking both ratios together shows how much your ability to pay upcoming bills depends on selling stock
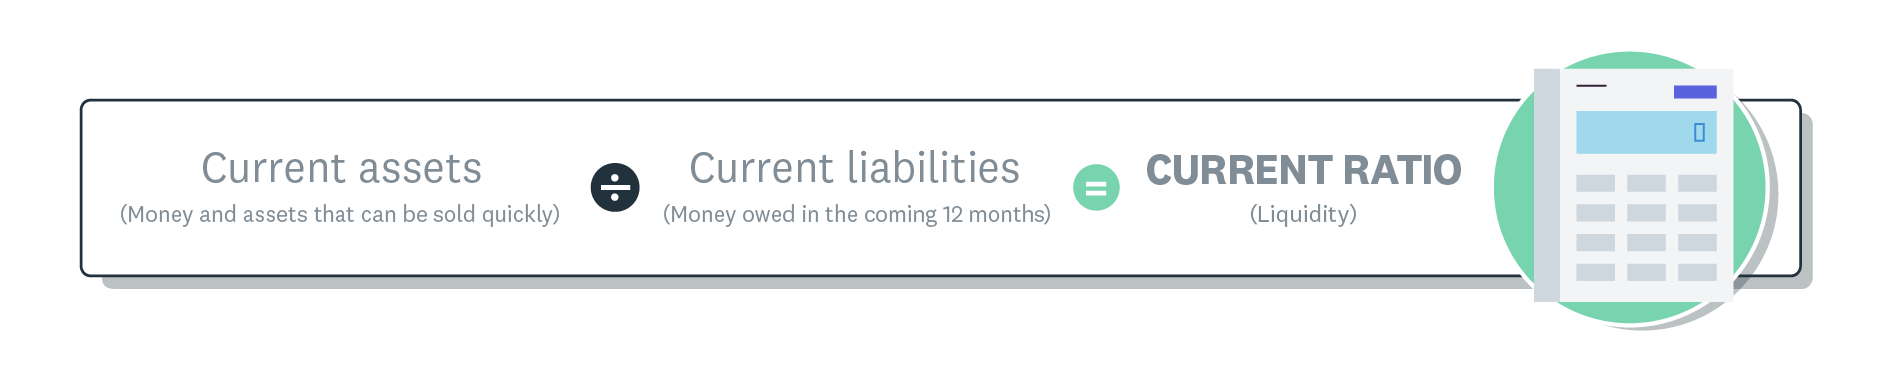
Current ratio liquidity formula.
What is the current ratio?
The current ratio compares what your business owns in the short term with what it owes in the short term. Also known as the working capital ratio, it shows whether you can meet obligations due within a year.
Current ratio = current assets ÷ current liabilities
Under International Accounting Standard 1 (IAS 1), current assets are items you expect to turn into cash within 12 months. If your normal operating cycle is longer, that cycle applies instead. Singapore companies report under Singapore Financial Reporting Standards (SFRS), which are aligned with or identical to International Financial Reporting Standards (IFRS).
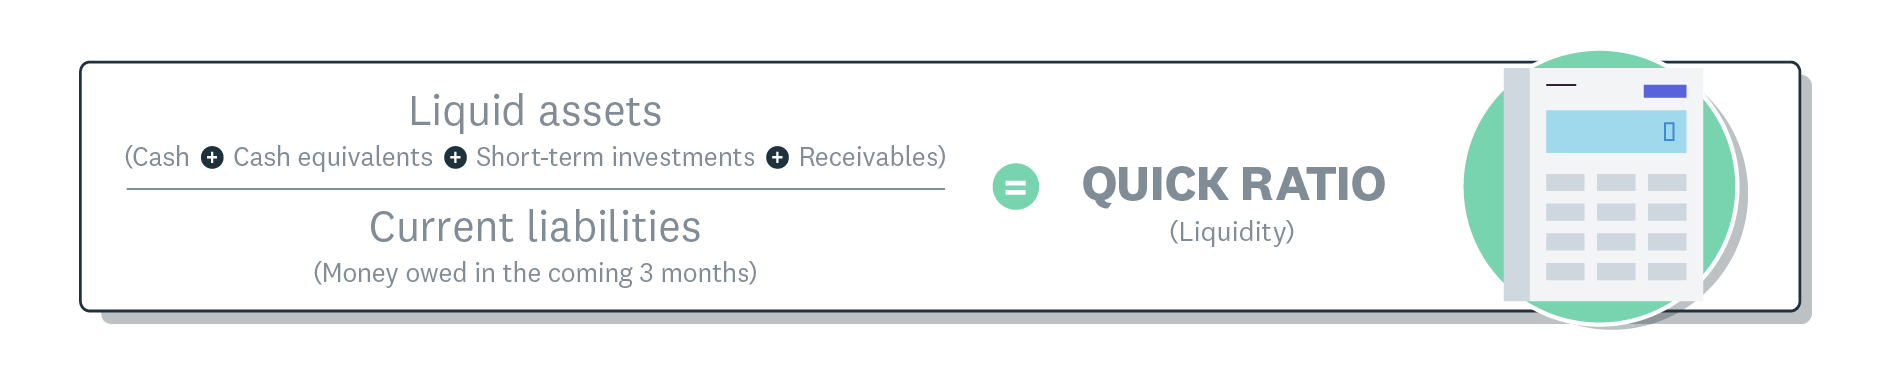
Quick ratio formula Version 1.
Both figures come from your balance sheet, which sits alongside your profit and loss statement among your core financial statements. Current assets typically include:
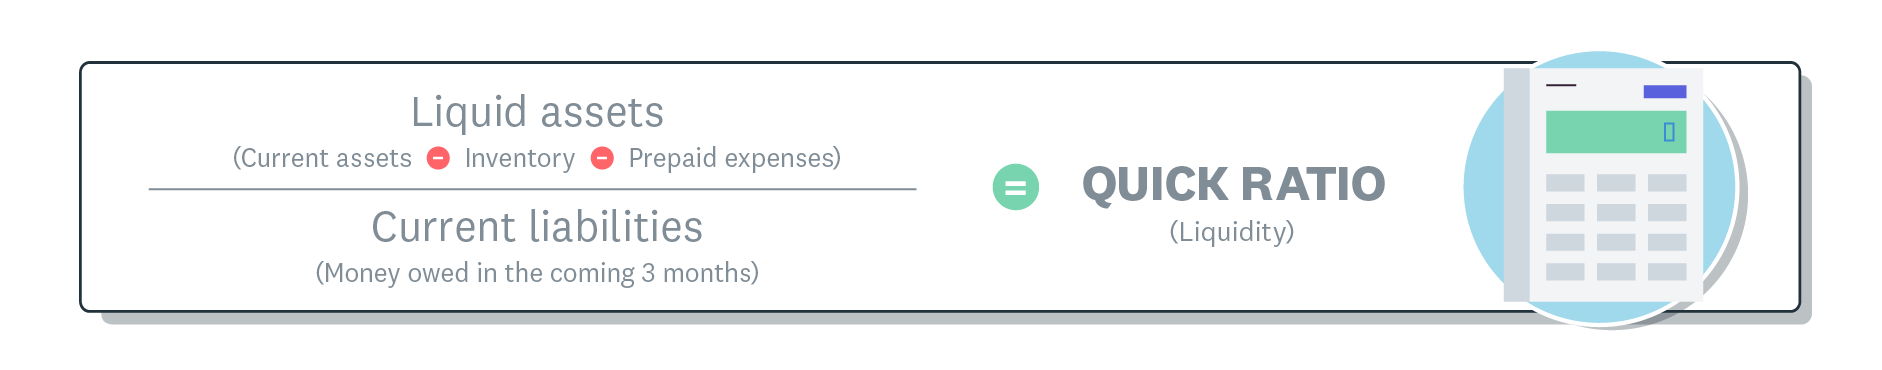
Quick ratio formula Version 2.
- cash and bank balances
- accounts receivable
- inventory
- prepaid expenses, such as rent or insurance paid in advance
On the other side of the balance sheet, current liabilities are debts due within the same period. They typically include:
- accounts payable
- short-term loans and bank overdrafts
- taxes owed, such as GST payable
- wages and CPF contributions due
Say your business has S$150,000 in current assets and S$100,000 in current liabilities. Your current ratio is 1.5, so you have S$1.50 of current assets for every S$1 you owe.
What is the quick ratio?
The quick ratio, also called the acid-test ratio, measures whether you can pay short-term debts using only assets you can turn into cash quickly. It gives a tougher test than the current ratio because it leaves out inventory and prepaid expenses.
There are two ways to calculate the quick ratio, and both give the same answer:
Quick ratio = (cash + marketable securities + accounts receivable) ÷ current liabilities
Quick ratio = (current assets – inventory – prepaid expenses) ÷ current liabilities
Why inventory is excluded
Stock only helps pay your bills once a customer buys it. According to AccountingTools, inventory can be hard to sell in the short term, and a rushed sale may mean selling at a loss.
Picture a furniture shop with S$55,000 of sofas in its showroom: that value can’t cover this month’s rent until the sofas sell. Prepaid expenses are left out too, because you’ve already spent that money and can’t use it to settle other bills.
Quick ratio example
Handy resources
Advisor directory
You can search for experts in our advisor directory.
Balance sheet template
See where and how assets and liabilities are reported.
Push-button liquidity reporting
Check your current ratio whenever you like with Xero’s accounting dashboard.
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.
Using the same business from the current ratio example, here’s how its S$150,000 in current assets breaks down:
- S$30,000 in cash
- S$50,000 in accounts receivable
- S$55,000 in inventory
- S$15,000 in prepaid expenses
Quick ratio = (S$150,000 – S$55,000 – S$15,000) ÷ S$100,000 = 0.8
A current ratio of 1.5 looks comfortable, yet the quick ratio of 0.8 shows you’d need to sell some stock to cover every short-term bill. To try this with your own numbers, list your assets and liabilities in a balance sheet template.
Key differences between the quick ratio and current ratio
When you weigh up the quick ratio vs current ratio, both divide assets by current liabilities; they differ in which assets make the cut. Here’s how they compare:
- The current ratio includes every current asset, while the quick ratio includes only cash, marketable securities and receivables
- The current ratio takes a 12-month view, while the quick ratio focuses on assets you can turn into cash quickly
- The current ratio reads higher for businesses holding lots of stock, while the quick ratio shows how they’d fare without selling it
- The two ratios give similar results for service businesses that hold little or no stock
How to interpret your results
Your ratios tell you the most when you read them against your industry and your own past results. Here’s what each number can signal.
Current ratio benchmarks
A current ratio above 1.0 means your current assets exceed your short-term debts. According to Corporate Finance Institute (CFI), analysts often consider 1.5–3.0 healthy, though the right figure depends on your business. CFI adds that a ratio below 1.0 could leave you exposed if sales slow or credit tightens.
Quick ratio benchmarks
A common rule of thumb is a quick ratio of around 1.0 or higher, which means your quick assets alone cover your current liabilities. Below 1.0, you’d rely on selling stock or bringing in new cash to pay everything due. At the other end, CFI notes that a very high quick ratio can point to spare cash you could put to better use.
Industry context
CFI’s comparison explains that retailers may operate well with a current ratio around 0.90 thanks to fast stock turnover. Manufacturers tend to target higher ratios. A wide gap between the two ratios, such as a current ratio of 2.0 and a quick ratio of 0.7, signals heavy reliance on inventory.
Who uses these ratios and why
Your liquidity ratios interest anyone deciding whether to extend you credit or put money into your business. The people most likely to check them are:
- banks and other lenders, when assessing a loan application
- suppliers, when deciding how much trade credit to offer
- investors, when judging whether the business can cover its short-term costs
- you and your accountant, when planning new hires or large purchases
Lumen Learning’s guide to financial ratio analysis notes that creditors watch the current ratio closely. Many loan and bond contracts also set a minimum level. If you’re weighing up ways to fund your business, check whether any agreement includes a ratio condition like this.
When to use the quick ratio vs the current ratio
The current ratio gives you the broad view, and the quick ratio tests whether that view holds up without stock sales. Here’s when each is most useful:
- Check the current ratio for a broad view of the obligations due over the next 12 months
- Check the quick ratio when you want to know you can pay bills without selling inventory
- Lean on the quick ratio when you build up seasonal stock, such as ahead of Chinese New Year or year-end festive sales
- Calculate both when you’re preparing a loan application, so you can explain any gap between them
With cloud accounting software, the underlying figures stay up to date, so you can check either ratio whenever a decision comes up.
Limitations of the quick ratio and current ratio
Both ratios are useful starting points, and they work best alongside other information. AccountingTools’ guide to the limits of the working capital ratio flags the snapshot and timing issues, and the rest follow from how the formulas work:
- They capture a single day, so a seasonal business may see very different ratios across the year
- They ignore when cash arrives and when bills fall due, so a healthy ratio can still come with a cash crunch
- They count receivables at full value, so an overdue invoice looks as liquid as cash in the bank
- They measure short-term liquidity only, so a strong ratio can sit alongside thin profits
Pairing your ratios with a cash flow forecast fills in the timing gap, because it shows when money is due in and out.
Other liquidity ratios to know
Two more ratios test your short-term position from different angles. One is stricter than the quick ratio, and the other looks at cash flow instead of balances.
Cash ratio
The cash ratio counts only cash and cash equivalents, which makes it the most conservative liquidity measure, according to AccountingTools.
Cash ratio = (cash + cash equivalents) ÷ current liabilities
In the earlier example, the cash ratio would be S$30,000 ÷ S$100,000 = 0.3.
Operating cash flow ratio
The operating cash flow ratio compares the cash your day-to-day operations bring in with your current liabilities. AccountingTools describes it as a helpful tool for lenders, especially when they’re evaluating smaller or newer borrowers.
Operating cash flow ratio = cash flow from operations ÷ current liabilities
Because it uses cash flow over a period, a single balance sheet date has less effect on the result.
How to improve your liquidity ratios
You can lift both ratios by bringing cash in sooner and keeping less of it tied up. Work through these steps as a regular routine:
- Tighten your payment terms and offer a small discount for early payment, so receivables turn into cash sooner
- Ask suppliers for longer payment terms, giving you more time to collect cash before bills fall due
- Keep inventory lean by ordering closer to demand, so less cash sits on your shelves
- Set aside part of each month’s revenue to build a cash reserve
- Talk to your lender about moving short-term borrowing into a longer-term loan, which shifts part of the debt out of current liabilities
- Review your ratios regularly using financial reports, and act early when a figure starts to slip
Track your liquidity ratios with Xero
Checking the quick ratio and current ratio together shows whether you can cover upcoming bills, and how much depends on selling stock. With Xero, automatic bank feeds bring in your transactions, so your balance sheet stays up to date in real time.
You can spot trends in cash and receivables with Xero’s dashboard and analytics tools, and share reports with your accountant whenever you need. Try Xero and get one month free to see your liquidity in one place.
FAQs on quick ratio vs current ratio
These answers cover common follow-up questions about reading and comparing your results.
Is 0.5 a good quick ratio?
A quick ratio of 0.5 means you have S$0.50 in quick assets for every S$1 of short-term debt. It can work for a business that sells stock very fast, but for most others it’s a prompt to review cash flow closely.
Is 1.2 a good current ratio?
A current ratio of 1.2 covers your short-term debts with a S$0.20 buffer for every S$1 owed. Whether that’s enough depends on how quickly your stock and receivables turn into cash.
What happens if my current ratio is less than 1?
Your current liabilities exceed your current assets, which means you have negative working capital. You’d need incoming sales, new financing or longer supplier terms to pay bills as they fall due.
What are quick assets?
Quick assets are the items you can turn into cash within a short time without a big loss in value. They’re cash, cash equivalents, marketable securities such as listed shares, and accounts receivable.
Why is it hard to compare ratios across companies?
Businesses hold different amounts of stock, run different operating cycles and prepare balance sheets on different dates. You’ll get the fairest comparison against businesses in your own industry, measured at a similar time of year.
How often should you calculate liquidity ratios?
Calculating them monthly helps you spot changes early. Pick the same point in your billing cycle each time, so every result reflects a comparable moment in your cash cycle.