Current ratio: formula, calculation and examples
Learn the current ratio formula, work through an S$ example and see what a healthy ratio looks like for your business.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Monday 26 October 2026
Table of contents
Key takeaways
- Calculate your current ratio by dividing current assets by current liabilities to see if you can cover short-term debts with available resources
- Aim for a current ratio between 1.5 and 2.0, as this shows healthy liquidity without holding excess cash you could invest in growth
- Measure your current ratio at the same time each month to track trends and make consistent comparisons
- Combine your current ratio with other measures, like cash flow forecasts and the quick ratio, for a complete picture of your business’s financial health
What is the current ratio?
Current ratio = current assets ÷ current liabilities. With S$250,000 in current assets and S$175,000 in current liabilities, S$250,000 ÷ S$175,000 = 1.43: S$1.43 of current assets for every S$1 owed. Below 1 means a possible shortfall, around 1.5–2 is generally healthy, and above 3 may mean idle cash or stock.
Current ratio measures your ability to pay short-term debts using your short-term assets. It’s a liquidity ratio that shows whether you can cover upcoming bills and loan repayments. You might also see it called the working capital ratio.
Current ratio is broader than the quick ratio because it includes all current assets, even those that take longer to turn into cash, like inventory. That’s why Wall Street Prep describes the quick ratio as a more conservative measure.
How to calculate current ratio
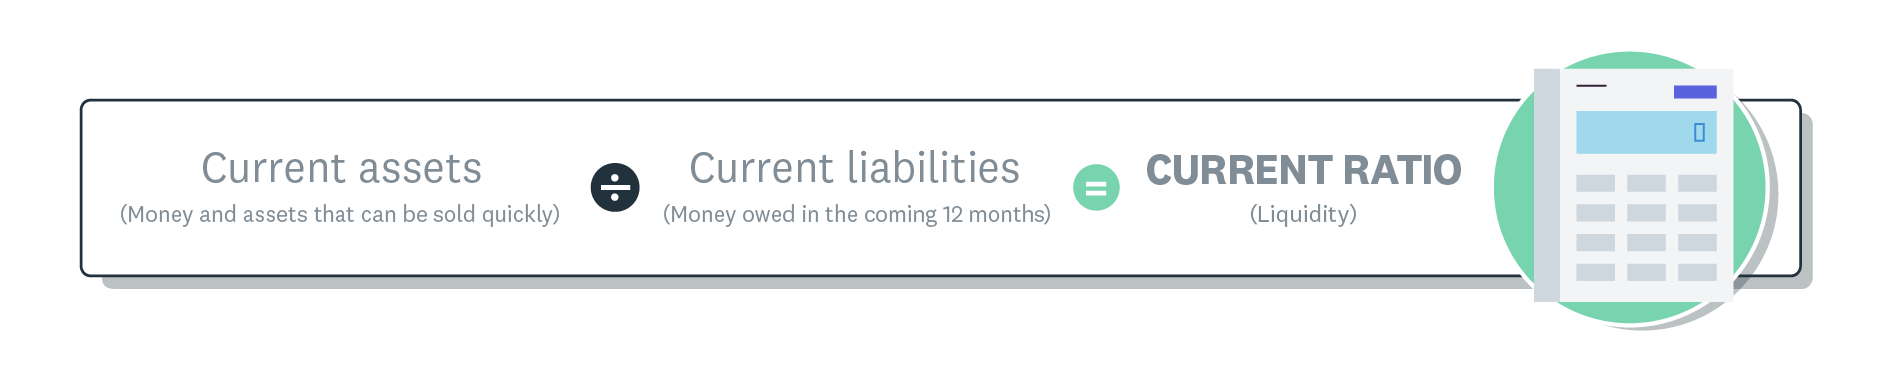
Current ratio liquidity formula.
You need two numbers from your balance sheet to calculate your current ratio. Follow these steps:
- Add up your current assets
- Add up your current liabilities
- Divide your current assets by your current liabilities
Current assets
Current assets are resources you expect to convert into cash within one year. They include:
- cash and cash equivalents
- inventory
- prepaid expenses
- short-term investments
Current liabilities
Current liabilities are obligations you must pay within one year. They include:
- short-term loans and credit lines
- accrued expenses
- taxes payable
- the current portion of long-term debt
Current ratio calculation example
A small construction business wants to check whether it can cover upcoming loan repayments and material costs. The business has S$250,000 in current assets and S$175,000 in current liabilities.
S$250,000 ÷ S$175,000 = 1.43. The current ratio is above 1, which means the company can cover upcoming liabilities. For every S$1 of liabilities, the company has S$1.43 available.
The company might invest the remaining cash in other areas. Or it could hold on to the extra cash for a time when its assets are lower and liabilities are higher.
How to interpret your current ratio
Your current ratio tells you whether your business can pay its bills. Here’s how to read the result.
- A ratio below 1.0 means you’ll want to improve your cash position to comfortably pay upcoming bills. This happens sometimes, especially for growing businesses making investments, so aim to get back above 1.0 soon.
- A ratio above 1.0 means your business can cover short-term debts and is generally in good shape. For every S$1 you owe, you have more than S$1 available.
- A ratio between 1.5 and 2.0 is what ReadyRatios calls a normal and acceptable value. It shows healthy liquidity while keeping cash working for you.
- A ratio above 3.0 is very high. You may have cash available for investment opportunities.
When to measure
Your current ratio changes throughout your billing cycle. Measure it at the same time each month to compare like for like and spot long-term trends.
Use it alongside other metrics
Combine your current ratio with profitability ratios and cash flow forecasts for a complete picture. ReadyRatios notes that acceptable current ratios vary from industry to industry.
What are the limitations of using the current ratio?
The current ratio is a snapshot of one moment, so it has some blind spots. Keep these in mind when you read it:
- Asset quality varies, as cash is ready now while inventory might take months to sell, yet the ratio counts both equally
- Timing isn’t reflected, because the ratio assumes all liabilities fall due at once
- Cash flow changes daily, so a single calculation can quickly go out of date
- Seasonal swings can make the ratio look stronger or weaker than usual
For a more complete view, track your ratio over time and combine it with cash flow forecasting.
Current ratio vs quick ratio
Both ratios measure liquidity, and the quick ratio sets the stricter test. Here’s how they compare:
- The current ratio counts all current assets, including inventory and prepaid expenses
- The quick ratio, also called the acid test ratio, counts only assets you can convert to cash within 90 days, so it leaves out inventory and prepaid expenses
- The current ratio gives a broad view, while the quick ratio suits businesses with slow-moving stock; see the differences between the quick and current ratio
- The cash ratio is the strictest test, comparing only cash and cash equivalents against current liabilities
Current ratio in relation to working capital and cash flow
Your current ratio is one of several ways to read your short-term finances. Here’s how it relates to working capital and cash flow:
- Working capital is the difference between current assets and current liabilities, showing the actual dollar amount
- Cash flow is the net movement of money in and out of your bank account
- The current ratio shows your capacity to pay, while cash flow shows the money actually moving
- Free cash flow is what remains after you subtract capital expenditure from operating cash flow
Track your current ratio with Xero
Xero handles the calculations so you can focus on what the numbers mean. Xero helps you:
- monitor your financial position in real time
- track how your ratios trend month to month
- use reporting tools to project future cash positions
- access the insights you need to plan confidently
Sign up today and get one month free to start tracking your business health with confidence.
FAQs on current ratio
Here are answers to common questions about the current ratio.
What is a good current ratio?
A good current ratio is typically 1.5–3.0, though acceptable ratios vary by industry. Above 1.0 covers short-term debts, and 1.5–2.0 is a healthy balance.
What is a good current ratio for a small business in Singapore?
For most small businesses in Singapore, 1.5–2 is a good target, depending on your industry and cash cycle. Compare your ratio with similar businesses in your sector and track it monthly in S$ to spot changes early.
Is 1.0 a good current ratio?
A current ratio of 1.0 means you have exactly enough current assets to cover your current liabilities. It’s the minimum threshold, so most businesses aim higher for a buffer.
What does a current ratio of 2.5 mean?
A current ratio of 2.5 means you have S$2.50 in current assets for every S$1 of liabilities, which shows strong liquidity. If it stays this high, consider investing the excess.
How often should I calculate my current ratio?
Calculate it monthly, at the same point in your billing cycle. This gives you like-for-like comparisons over time.
Can my current ratio be too high?
Yes, a ratio above 3.0 may mean you’re holding excess cash or inventory that could fund growth.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.