Free cash flow (FCF)
Learn what free cash flow is, how to calculate it, and how to use it to plan your business spending.
Published Wednesday 30 September 2026
Table of contents
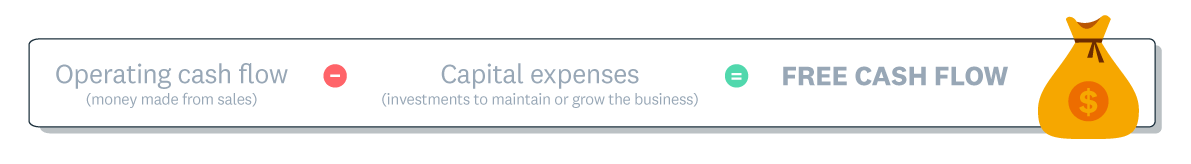
Free cash flow formula.
Key takeaways
- Free cash flow (FCF) is the cash your business has left after paying operating costs and capital expenditures. It shows how much you can put towards debt, savings, owner pay or growth.
- The standard formula is operating cash flow minus capital expenditures. You can also start from net profit and adjust for non-cash expenses and working capital.
- FCF differs from profit and earnings before interest, taxes, depreciation and amortisation (EBITDA) because it tracks real cash movements. A business can report healthy earnings and still run short of cash.
- Tracking FCF monthly or quarterly helps you spot shortfalls early. Collecting payments sooner and timing big purchases carefully can both lift it.
What is free cash flow?
Free cash flow (FCF) is the cash your business generates from normal operations after paying for capital expenditures such as equipment or vehicles. It shows how much cash is truly available once day-to-day costs and long-term investments are covered.
Your business can be profitable on paper while much of that profit sits in unpaid invoices and new equipment. That’s because under accrual accounting, profit records income when you earn it, even if the customer pays weeks later. FCF looks past this timing to show the cash you can use right now.
Think of FCF as your business’s take-home pay: what’s left in your hands after the essential bills and big purchases are paid. It bridges the gap between what your income statement says you earned and what your bank account shows.
Why free cash flow matters
Free cash flow matters because it gives you and your lenders a realistic view of your business’s financial health. Revenue and profit show what you’ve earned, while FCF shows whether you have the cash to keep running smoothly.
Tracking FCF helps you in several practical ways.
- Shows your true spending power once all essential costs are covered
- Helps you plan ahead, as a cash flow forecast built on your FCF trend flags shortfalls before they hit
- Builds credibility with banks and investors, who often check FCF to judge whether you can take on new debt
- Supports decisions such as when to hire or buy new equipment
When sales slow, knowing the cash left after operating costs and capital spending helps you decide where to cut costs or whether to seek funding.
Free cash flow formula
The free cash flow formula subtracts capital expenditures from operating cash flow. The Corporate Finance Institute (CFI) describes FCF as the cash a company produces once it has paid for operations and capital assets.
Free cash flow = operating cash flow – capital expenditures
Each part of the formula comes from your cash flow statement.
- Operating cash flow is the cash your regular trading brings in, such as customer payments minus supplier and staff costs. It’s sometimes labelled “cash from operations”.
- Capital expenditures (CapEx) are what you spend on long-term assets your business needs to operate or grow. Common examples include a new vehicle or a workspace renovation.
If you’d rather start from your profit and loss report, use this alternative version of the formula.
Free cash flow = net profit + non-cash expenses (such as depreciation) – increase in working capital – capital expenditures
Both versions should land on the same figure, because the adjustments turn profit back into operating cash flow first.
How to calculate free cash flow
You can calculate free cash flow in four steps once your financial records are up to date. Work through them in order for each period you want to measure.
1. Locate your operating cash flow
Operating cash flow is your starting point. Open your cash flow statement and find the section labelled “cash flows from operating activities”. If your statement uses the indirect method, this figure starts with net profit, then adjusts for non-cash items like depreciation and for changes in money owed to and by you.
2. Identify your capital expenditures
Next, find what you spent on long-term assets during the period. Under International Accounting Standard 7, cash flow statements group cash flows into operating, investing and financing activities. Buying property, plant and equipment counts as an investing activity, so look there.
If you use Xero accounting software, you can pull these figures straight from your reports.
3. Subtract capital expenditures from operating cash flow
Take your operating cash flow and subtract your capital expenditures. The result is your free cash flow for the period you’re analysing.
4. Review and compare across periods
One FCF figure is a snapshot, so track it monthly or quarterly. Comparing periods helps you spot seasonal patterns and early signs of cash pressure.
Free cash flow calculation example
A worked example shows how the formula plays out in a real business. Imagine you own a small landscaping business in Singapore.
At the end of the quarter, your cash flow statement shows operating cash flow of SGD 85,000. You also spent SGD 20,000 on a new mower and trailer.
Free cash flow = SGD 85,000 – SGD 20,000 = SGD 65,000
Your business generated SGD 65,000 in cash that quarter after covering operating costs and new equipment. You could use it to pay down a loan or fund a marketing campaign to win new clients.
To compare quarters with different sales levels, work out your FCF margin: FCF ÷ revenue × 100. For example, if quarterly revenue was SGD 250,000, FCF margin = 65,000 ÷ 250,000 = 26%.
Now say the next quarter looks different: operating cash flow drops to SGD 60,000 and you spend SGD 35,000 on a used truck. Your FCF is SGD 60,000 – SGD 35,000 = SGD 25,000. The drop reflects a planned purchase, and it tells you to go easier on discretionary spending that quarter.
Free cash flow vs operating cash flow and EBITDA
Free cash flow is operating cash flow minus capital expenditures, while EBITDA is a profit measure that ignores both capital spending and working capital. Knowing the difference stops a strong-looking number from hiding a cash squeeze.
Operating cash flow is the cash your core operations bring in before you spend anything on long-term assets. FCF takes that figure and deducts CapEx, so it falls whenever you invest in equipment or vehicles.
EBITDA stands for earnings before interest, taxes, depreciation and amortisation. As CFI’s EBITDA guide explains, it’s an earnings measure, so it leaves out CapEx and changes in working capital. That means EBITDA can look healthier than the cash you actually have.
Picture a business whose biggest customers pay late and that has just bought a new van. Its EBITDA looks strong, while its FCF shows how little cash is really left to spend.
How free cash flow compares to other financial metrics
Free cash flow is one of several measures of business health, and each one captures something different. Here’s how FCF relates to four other common measures.
- Total cash flow covers all cash moving in and out, including investing and financing, while FCF narrows to what’s left from operations after CapEx
- Working capital compares current assets with current liabilities at one point in time, while FCF measures cash generated over a period
- Net profit includes non-cash items such as depreciation, so it can differ from the cash your business actually produced
- Liquidity, measured with liquidity ratios, describes how easily you can turn assets into cash, and FCF is one input into that picture
Each metric fills a gap the others leave. Tracking FCF alongside your financial statements gives you a fuller view of where your business stands.
Types of free cash flow
There are two main types of free cash flow, and each answers a different question about who the cash is for. The difference comes down to whether lenders are counted.
- Free cash flow to the firm (FCFF) is the total cash available to everyone with a financial stake in your business, including lenders and owners. It’s calculated before interest and debt repayments.
- Free cash flow to equity (FCFE) is the cash left for owners after expenses, reinvestment and debt, as set out in CFI’s guide to FCFE. You could pay it out to shareholders or keep it as retained earnings.
For most small business owners, the standard formula works well for everyday decisions. FCFF and FCFE become more useful when you’re seeking investment or preparing to sell the business.
How to use free cash flow
Positive free cash flow gives you choices about where your spare cash goes. Most small businesses put it towards one or more of these goals.
- Pay down loans or credit lines to reduce interest costs
- Build a cash buffer for slow months or surprise bills
- Reinvest in new equipment or growth projects
- Pay yourself and other owners through drawings or dividends
Checking FCF before each decision shows how much you can commit without squeezing day-to-day cash.
How to interpret free cash flow
Your FCF figure tells you the most when you read it in context. Check whether the number is positive and which way it’s trending over time.
Positive free cash flow means your business brings in more cash than it spends on operations and capital investments. Consistently positive FCF over several quarters signals a financially stable business with room to save and invest.
Negative free cash flow is often the normal result of a large, planned investment, such as new equipment or a second location. What matters is whether it’s a one-off or a pattern. Ongoing negative FCF without a clear reason suggests the business is spending more cash than it brings in.
Trends tell you more than a single number, so review FCF over three or four quarters or more. A steady rise suggests stronger cash generation. A steady decline is a prompt to check costs and collections, even while FCF is still positive.
External conditions also affect how you read your free cash flow. A dip during a slow quarter for your industry may reflect wider market conditions rather than a problem with how you run the business. Compare your numbers with what’s happening in your market.
How to improve free cash flow
You can lift free cash flow by collecting cash sooner and holding on to it for longer. These steps are a practical place to start.
- Send invoices promptly with online invoicing and follow up on overdue payments
- Review your accounts receivable each week to see who owes you and for how long
- Negotiate longer payment terms with suppliers so cash stays with you for more days
- Cancel subscriptions and services you rarely use
- Match stock to demand, using an inventory management system to track what sells
- Space out capital purchases or lease equipment to spread the cash cost
- Raise prices or add a complementary service to boost operating cash flow
Small improvements across several areas often add up to more than one big change. Review your FCF each month to see which changes make the most difference.
Benefits and limitations of free cash flow
Free cash flow is a practical measure, and it works best when you understand its strengths and gaps. Weigh both before you base a big decision on it.
Tracking FCF brings these benefits.
- Reflects real cash movements, which makes it harder to distort than net profit
- Supports budgeting for investments and unexpected costs
- Allows benchmarking against past periods or similar businesses
- Signals financial health to lenders and potential buyers
Keep these limitations in mind too.
- Swings sharply after one large equipment purchase, even in a strong quarter
- Leaves out loan principal repayments and owner drawings, so it covers only part of your cash commitments
- Shifts with timing, as delaying a purchase can lift FCF without any real improvement
- Works best alongside profit margins and your cash flow statement
Track your free cash flow with Xero
Free cash flow shows how much cash your business can spend after keeping operations running and investing in assets. Checking it regularly helps you plan purchases and repayments with confidence.
Xero connects your bank feeds and builds the reports you need to calculate FCF in minutes. Xero’s cash flow forecasting then shows where your cash is heading, so you can plan your next investment early. Try Xero today and get one month free.
FAQs on free cash flow
Here are quick answers to common questions about free cash flow.
What is a good free cash flow?
A good FCF stays positive in most quarters and grows alongside your revenue. Tracking FCF margin lets you compare periods fairly even when sales rise or fall.
Can a business have negative free cash flow?
Yes, and new or fast-expanding businesses often do for a while. Plan how you’ll cover the gap, such as with savings or a loan, before the big spending starts.
Is EBITDA the same as free cash flow?
No. Use EBITDA to compare underlying profitability between periods, and use FCF to decide what you can actually afford to spend.
What can free cash flow be used for?
You can use it to repay debt, build reserves, reinvest or pay owners. Set an order of priority before the cash arrives, for example, topping up your buffer first and then splitting the rest.
How often should you calculate free cash flow?
Monthly works well for most small businesses. Calculate it at the same point each period so your comparisons stay consistent.
Is free cash flow the same as profit?
No. Buying a van outright can leave you with a profit and negative FCF in the same quarter. Profit spreads the van’s cost over several years, while the cash leaves at once.
Related terms
Learn more about free cash flow
Handy resources
Advisor directory
You can search for experts in our advisor directory
Cash flow statement template
Download our template to help you stay across cash flow for your business
Financial reporting
Keep track of your performance with accounting reports
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.