What is operating profit?
Learn what operating profit is, how to calculate it in rupiah and how to use it to improve your business.
Published Wednesday 30 September 2026
Table of contents
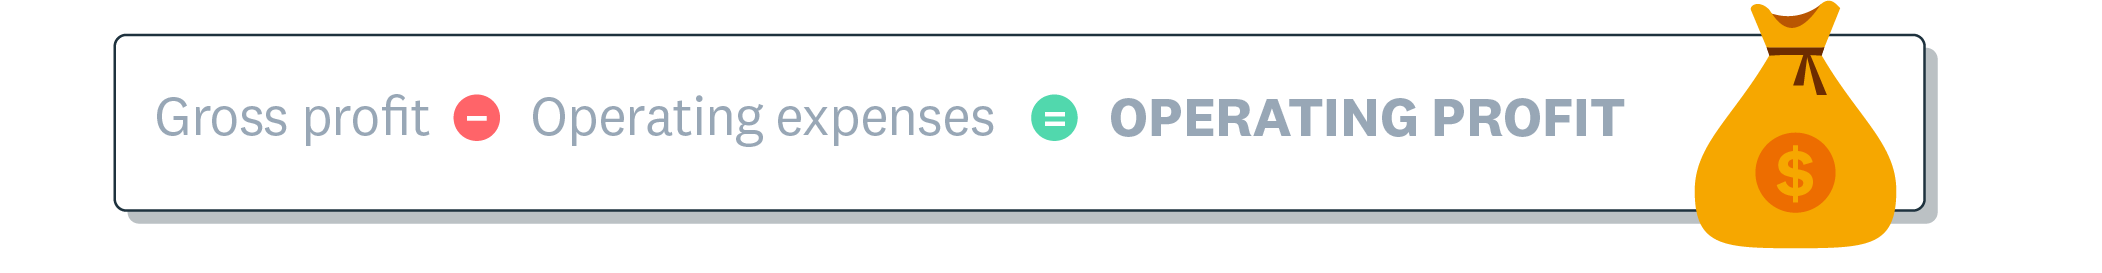
Operating profit is the money you make before taxes
Key takeaways
- Operating profit is what your business earns from its core activities after you subtract cost of goods sold (COGS) and operating expenses
- You work it out as revenue minus COGS minus operating expenses, and many people treat it as earnings before interest and taxes (EBIT)
- From 1 January 2027, Indonesia’s updated presentation standard requires entities that apply it to show operating profit as a defined subtotal
- Your operating profit margin shows how much of every Rp100 in revenue you keep, and pricing reviews or leaner overheads can lift it
What is operating profit?
Operating profit is the money your business makes from its core activities after you pay the costs of running them. It’s also called operating income or EBIT, and in Indonesia you’ll often see it written as laba operasional.
Picture a bakery owner asking one question: does selling bread and cakes make money before loan repayments and tax come into play? This figure answers that question, because it leaves out financing costs and income tax.
That focus shows how well your day-to-day operations perform, whatever way you fund or structure the business. Watch it closely when you want to know whether your business model holds up.
Handy resources
Advisor directory
You can search for experts in our advisor directory
Financial reporting
Keep track of your performance with accounting reports
What’s included and excluded from operating profit
The calculation counts the costs of running your business and sets aside items linked to financing and tax. Knowing which side each item falls on keeps your figure accurate.
The costs you subtract from revenue are:
- cost of goods sold (COGS), which covers direct costs such as materials and production labour
- operating expenses, which cover indirect costs such as rent, utilities, marketing, office salaries, insurance and depreciation
Owners and analysts usually strip out items that sit outside everyday trading. These typically include:
- interest you pay on loans or earn on savings
- income tax
- dividends and other investment income
- gains or losses when you sell equipment or property
- foreign exchange gains or losses on loans and investments
- one-off gains or losses, such as a legal settlement
Accounting standards can classify some of these items differently. Your accountant can confirm where each one belongs in your statements.
Why operating profit matters for your business
This measure tells you whether your trading pays its way. Strong sales only help when the costs of making them stay in check.
Checking it regularly helps you:
- see whether costs are keeping pace with the revenue you bring in
- spot which expenses are rising or which products are underperforming
- compare your results with similar businesses in your industry
- show lenders and investors that your core business can sustain itself
Those trends then guide your next moves, such as adjusting prices or putting more money into what’s working.
How to calculate operating profit
The calculation is straightforward once your figures are organised. Follow these steps for any period, such as a month or a quarter.
- Find your total revenue for the period.
- Add up your COGS for the same period.
- Subtract COGS from revenue to get your gross profit.
- Add up your operating expenses, including depreciation and amortisation.
- Subtract operating expenses from gross profit to get operating profit.
Those steps give you two formulas that reach the same answer. The one-line version is quicker:
Operating profit = revenue − COGS − operating expenses
The two-step version shows gross profit along the way, which helps you check your pricing:
Gross profit = revenue − COGS
Operating profit = gross profit − operating expenses
Operating profit example
A worked example makes the formula easier to follow. Say you own a bakery in Indonesia and want to check last month’s results.
For the month, your bakery records:
- Rp450,000,000 in sales revenue
- Rp180,000,000 in COGS for flour, sugar, butter, packaging and baker wages
- Rp35,000,000 in rent
- Rp8,000,000 in utilities
- Rp12,000,000 in marketing
- Rp40,000,000 in administrative salary
- Rp5,000,000 in insurance
- Rp10,000,000 in equipment depreciation
First, add rent, utilities, marketing, salary, insurance and depreciation to get your total operating expenses:
Rp35,000,000 + Rp8,000,000 + Rp12,000,000 + Rp40,000,000 + Rp5,000,000 + Rp10,000,000 = Rp110,000,000
Then apply the formula:
Operating profit = Rp450,000,000 − Rp180,000,000 − Rp110,000,000 = Rp160,000,000
Your bakery earned Rp160,000,000 from its core operations before loan interest and income tax. That’s the figure to use when you judge how the business performs on its own merits.
Where operating profit appears in your financial statements
You’ll find this figure on your profit and loss statement, after operating expenses and before financing costs and tax. Reading down, you see revenue, COGS, gross profit, operating expenses, operating profit and then net profit.
Its place in Indonesian reporting is becoming more formal under the Indonesian Financial Accounting Standards Board (DSAK IAI). The board ratified Pernyataan Standar Akuntansi Keuangan (PSAK) 118 on 28 May 2025, according to Ikatan Akuntan Indonesia (IAI). It adopts International Financial Reporting Standard (IFRS) 18, replaces PSAK 201 and takes effect on 1 January 2027.
PSAK 118 requires defined subtotals, including operating profit, as SW Indonesia explains. It sorts income and expenses into operating, investing, financing, income tax and discontinued operations categories. Entities that apply it will present this subtotal on a consistent basis.
Private businesses have another option. Standar Akuntansi Keuangan Entitas Privat (SAK EP) took effect on 1 January 2025 for entities without public accountability, according to IAI. Your accountant can confirm which standard applies to your business.
Operating profit vs. other profit types
Operating profit is one of several profit measures on your financial statements, and each one stops at a different line. Comparing them shows exactly which costs you’re looking at.
Operating profit vs. gross profit
Gross profit subtracts only COGS from revenue, while the operating figure also subtracts rent, marketing, insurance and administrative salaries. Gross profit tells you whether pricing covers production costs; the second tells you whether the whole business covers its running costs.
A healthy gross profit can still sit alongside thin operating results when overheads are high. Checking both figures shows you where the pressure sits.
Operating profit vs. net profit
Net profit is your bottom line after every cost, including interest and tax. The operating figure stops earlier, so it removes the effects of your financing and tax position.
Two businesses with identical operations can report very different net profits because of their debt levels. Looking one line higher lets you compare them on how they trade.
Operating profit vs. EBIT
The two are often the same number, but they’re calculated from different directions. Operating profit works down from revenue, while EBIT is often built up from net profit by adding back interest and tax.
Built that way, EBIT picks up non-operating items such as investment income or a gain on selling equipment. So if your business has those items, EBIT can differ from your operating result.
Operating profit vs. EBITDA
EBITDA stands for earnings before interest, taxes, depreciation and amortisation. It adds depreciation and amortisation back to operating profit.
Analysts sometimes use EBITDA to compare businesses with very different asset bases. For most small businesses, the operating figure is more practical, because it reflects the real cost of wearing out your equipment over time.
What is operating profit margin?
Operating profit margin turns that figure into a percentage of revenue. That makes it easy to compare periods, or to compare your business with others.
Use this formula:
Operating profit margin = (operating profit ÷ revenue) × 100
For the bakery, that’s (Rp160,000,000 ÷ Rp450,000,000) × 100 = 35.6%. In other words, the bakery keeps about Rp35.60 of every Rp100 in revenue after paying production and operating costs.
Margins vary widely by industry. Aswath Damodaran’s emerging-markets dataset (New York University Stern School of Business, updated January 2026) puts average pre-tax operating margins at about:
- 4.2% for restaurants and dining
- 6.1% for general retail
- 3.8% for grocery and food retail
- 4.7% for business and consumer services
- 9.1% for the total market
These averages come from listed companies, so margins for local small businesses may differ. Your own trend over time is the more useful signal, because a falling margin points to rising costs or pricing pressure.
Limitations of operating profit
The figure is a strong guide to how your business trades, but it covers only part of your financial picture. Knowing its blind spots helps you read it alongside other figures.
Keep these points in mind.
- It records sales when you earn them, so cash from late-paying customers may arrive weeks later
- It leaves out loan interest, so a heavily borrowed business can look healthier than it is
- It’s a pre-tax figure, which is why some analysts use net operating profit after tax instead
- It shifts with accounting choices, such as your depreciation method or when you recognise revenue
Pairing it with a cash flow forecast gives you a fuller view. You’ll see both what your operations earn and when the money lands.
How to improve your operating profit
You can lift this figure by earning more from each sale, spending less to run the business, or both. These practical steps are a good place to start.
- Review your pricing, because a 5% increase on Rp450,000,000 of monthly revenue adds Rp22,500,000 if sales volume holds
- Trim overheads by auditing recurring costs such as subscriptions and services
- Negotiate bulk discounts or longer payment terms with suppliers to lower your COGS
- Use accounting software to automate bank reconciliation and expense tracking
- Drop products or services that consistently earn low margins
- Check expenses monthly so you catch rising costs early
Small gains across several of these areas add up over a quarter or a year. For more ways to trim spending, browse these cost-saving ideas.
Track your operating profit with Xero
Your operating results are most useful when the numbers behind them are current. Xero brings your transactions in through bank feeds, so your financial reports stay up to date with less manual entry.
See your profit and expense trends at a glance in real-time profit and loss reports, then share them with your advisor and discuss them together. Compare plans, or get one month free if you want to try Xero before you buy.
FAQs on operating profit
These answers cover the questions owners often ask once they start tracking these numbers.
Is operating profit the same as EBIT?
They match when your business has no non-operating income or one-off gains. Before you compare your figure with a lender’s, ask which measure they use, because their EBIT may include those extra items.
Can a business have a positive operating profit but a net loss?
Yes, when interest costs and tax add up to more than your operating result, or a one-off loss pushes the bottom line below zero. This usually means the core business is sound, and your debt costs or unusual items need attention.
How is operating profit different from cash flow?
It includes non-cash costs like depreciation, while cash flow tracks the money that moves in and out of your bank account. Cash flow also captures loan repayments and equipment purchases, which the profit figure leaves out.
What does an operating loss mean?
An operating loss means your running costs are bigger than your gross profit, so your core activities cost more than they bring in. It can happen in a start-up phase or a slow season, and reviewing prices and overheads is the usual first step.
Related terms
Learn more about operating profit
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.