Straight-line depreciation explained
Learn the straight-line depreciation formula, follow a worked example, and build a schedule for your assets.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Tuesday 6 October 2026
Table of contents
Key takeaways
- Straight-line depreciation spreads an asset’s cost evenly over its useful life, making it the simplest method to calculate and apply
- The formula is (cost − salvage value) ÷ useful life, which gives you the same expense every year
- The method suits assets that lose value steadily, like office furniture, buildings, rental property, and leasehold improvements
- Understanding depreciation helps you make smarter tax decisions, including whether to use Section 179 expensing or bonus depreciation for faster write-offs
What is straight-line depreciation?
Every physical asset your business owns loses value over time, and depreciation is how you reflect that loss in your financial records. Straight-line depreciation is the most commonly used approach, and it’s the easiest to understand.
The method spreads the cost of a tangible asset evenly across each year of its useful life. You subtract the asset’s salvage value (what it’s worth at the end of its life) from its original cost to get the depreciable base. Then you divide that depreciable base by the number of years you expect to use the asset.
Businesses use depreciation because accounting standards don’t allow you to expense the full cost of a long-term asset in the year you buy it. Instead, you recognize a portion of the cost each year, matching the expense to the revenue the asset helps generate. This gives you a more accurate picture of your profitability over time.
Straight-line depreciation is popular because the calculation is simple and produces a consistent expense each period. If you want a predictable way to account for wear and tear on your equipment, vehicles, or property, it’s often the right starting point.
Straight-line depreciation formula
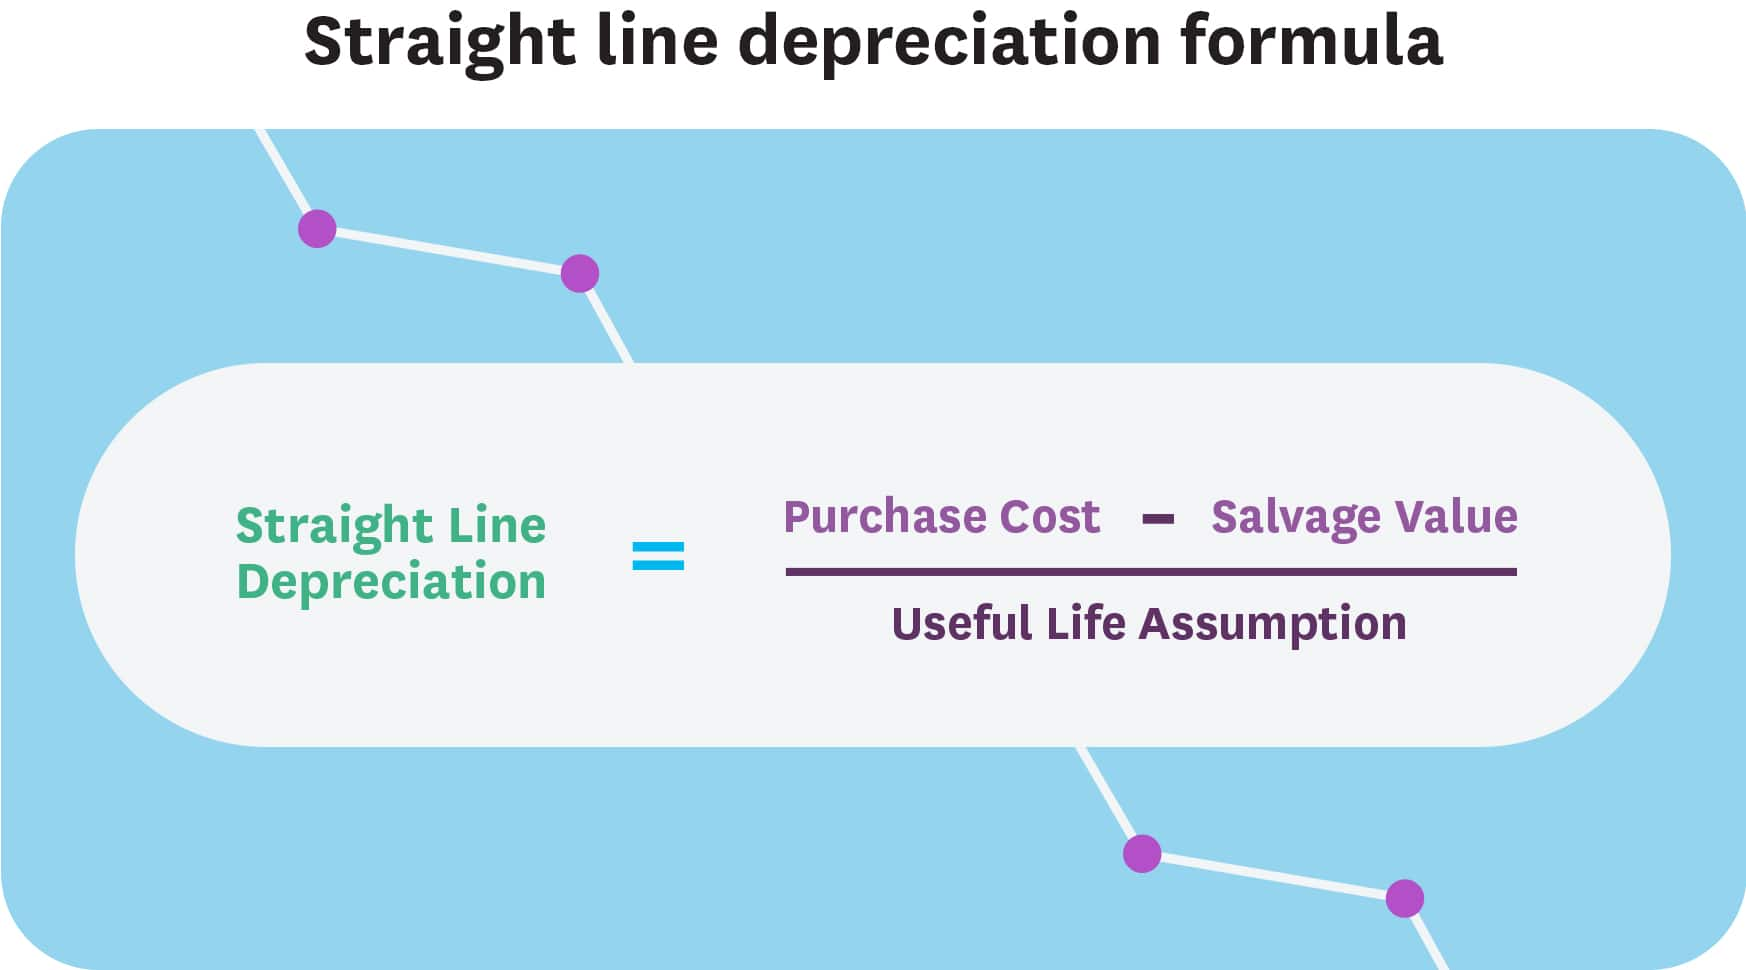
The formula for straight-line depreciation uses three figures you can estimate for any asset. Here’s how it works:
Annual depreciation expense = (cost − salvage value) ÷ useful life
Each component plays a specific role in the calculation.
- Cost: the total amount you paid to acquire and put the asset into service, including purchase price, shipping, and installation
- Salvage value: the estimated amount the asset will be worth when you’re done using it, sometimes called residual value
- Useful life: the number of years you expect to use the asset in your business before retiring or replacing it
The difference between cost and salvage value is known as the depreciable base. That’s the total amount you’ll expense over the asset’s useful life.
How to calculate straight-line depreciation
Four steps take you from an asset’s price tag to its annual depreciation expense. One example, a delivery van, runs through every step so you can see the formula in action.
1. Work out the asset’s total cost
Start with the purchase price, then add anything you spent to get the asset ready for use, such as shipping, installation, and setup. This total is the cost figure in the formula. Say your business buys a delivery van for $35,000, including all costs to put it on the road.
2. Estimate the salvage value
Salvage value is what you expect the asset to be worth when you stop using it. Base your estimate on resale prices for similar used assets or on your own experience selling equipment. For the van, you estimate a salvage value of $7,000.
3. Estimate the useful life
Useful life is the number of years you expect the asset to work for your business before you retire or replace it. Consider how heavily you’ll use it and how long similar assets have lasted you. You plan to run the delivery van for seven years.
4. Divide the depreciable base by the useful life
Subtract the salvage value from the cost to get the depreciable base, then divide it by the useful life. For the van, $35,000 − $7,000 = $28,000, and $28,000 ÷ 7 = $4,000 a year. If you record depreciation monthly, divide the annual figure by 12 to get about $333.33 a month.
More straight-line depreciation examples
The same four steps work for any asset, whatever its price. Say you buy a piece of plant machinery for $22,000, expect to use it for 10 years, and estimate a $2,000 salvage value. Your depreciable base is $20,000, so you’d record $2,000 in depreciation expense each year for 10 years.
Smaller purchases follow the same pattern. An office computer costs $1,200, lasts five years, and has a $200 salvage value. That gives you a $1,000 depreciable base and $200 of depreciation a year.
Example depreciation schedule
A depreciation schedule shows how the expense builds up and the asset’s book value falls each year. Here’s the schedule for the delivery van, which loses $4,000 of book value a year until it reaches its $7,000 salvage value.
- Year 1: $4,000 annual expense, $4,000 accumulated depreciation, $31,000 book value at year end
- Year 2: $4,000 annual expense, $8,000 accumulated depreciation, $27,000 book value at year end
- Year 3: $4,000 annual expense, $12,000 accumulated depreciation, $23,000 book value at year end
- Year 4: $4,000 annual expense, $16,000 accumulated depreciation, $19,000 book value at year end
- Year 5: $4,000 annual expense, $20,000 accumulated depreciation, $15,000 book value at year end
- Year 6: $4,000 annual expense, $24,000 accumulated depreciation, $11,000 book value at year end
- Year 7: $4,000 annual expense, $28,000 accumulated depreciation, $7,000 book value at year end (salvage value)
Mid-year convention
In some cases, you may not place an asset in service on the first day of your fiscal year. The mid-year convention assumes that all assets are placed in service at the midpoint of the year, regardless of the actual purchase date. This means you claim half a year’s depreciation in the first year and half in the final year.
For the delivery vehicle example above, a mid-year convention would give you $2,000 of depreciation in year one and $2,000 in year eight, with $4,000 in each year between. The IRS requires the mid-year convention for most assets under the Modified Accelerated Cost Recovery System (MACRS) unless a different convention applies.
Download a straight-line depreciation schedule template
A schedule keeps each asset’s figures in one place, so you can see its book value at a glance. Download the straight-line depreciation schedule template to set up your own in minutes.
The template has a column for each figure you need.
- Asset name
- Date placed in service
- Cost
- Salvage value
- Useful life
- Annual depreciation
- Accumulated depreciation
- Book value at year end
Add one row for each asset, then update accumulated depreciation and book value at the end of every year. You can also browse more free small business templates for invoicing, reporting, and planning.
Pros and cons of the straight-line method
Like any accounting method, straight-line depreciation has clear advantages and some limitations. Here’s what to consider when deciding if it’s right for your business.
Pros
The straight-line method’s biggest strength is simplicity. It helps you in these ways.
- Keeps the math simple, even without an accounting background
- Produces a consistent, predictable expense each period, which helps with budgeting and forecasting
- Meets GAAP (Generally Accepted Accounting Principles) for financial reporting
- Suits assets that wear out evenly over time
Cons
The same even spread can work against you for some assets. Keep these limitations in mind.
- Understates early wear on assets that lose value faster in their first years, like technology or vehicles
- Mismatches expense and revenue when an asset earns more early in its life
- Differs from what the IRS usually requires for tax depreciation, which is MACRS
- Ignores unexpected changes in an asset’s useful life or value
Other depreciation methods
Depending on how you use an asset and your tax situation, a different method may fit better than straight-line. Here are the main alternatives.
Units of production
This method ties depreciation to actual usage rather than time. You calculate a per-unit rate by dividing the depreciable base by the total estimated units the asset will produce. It works well for manufacturing equipment or vehicles, where wear and tear depends on how much you use them.
Declining balance
The declining balance method applies a fixed depreciation rate to the asset’s remaining book value each year. Because the book value shrinks over time, your depreciation expense is highest in the first year and decreases after that. This better reflects assets that lose the most value early in their life.
Double-declining balance
This is an accelerated version of the declining balance method. You take twice the straight-line rate and apply it to the remaining book value each year. It’s useful when you want to front-load your depreciation expense, which is common for technology assets and equipment that becomes obsolete quickly.
Sum-of-the-years’-digits
Another accelerated method, sum-of-the-years’-digits assigns a fraction to each year based on the remaining life of the asset. For an asset with a five-year life, the fractions would be 5/15, 4/15, 3/15, 2/15, and 1/15. Like declining balance, this front-loads the expense to reflect faster early depreciation.
MACRS (Modified Accelerated Cost Recovery System)
MACRS is the depreciation system the IRS requires for most business assets for tax purposes. It uses predetermined recovery periods and accelerated methods to calculate your deduction. MACRS assigns specific recovery periods to different asset types.
- Computers and peripherals: five years
- Light trucks and vehicles: five years
- Office furniture: seven years
- Residential rental property: 27.5 years
- Nonresidential real property: 39 years
You’ll find a complete list of recovery periods in IRS Publication 946.
MACRS also has an alternative system called ADS (Alternative Depreciation System). ADS generally uses longer recovery periods and the straight-line method. It’s required for certain types of property, including assets used predominantly outside the US and tax-exempt property.
Keep in mind that MACRS is for tax depreciation only. For your internal books and financial statements, you can still use straight-line or any other method that best reflects how the asset loses value.
Depreciation impact on financial statements and taxes
Depreciation shows up on three major financial statements and shapes your tax planning. Here’s how.
Income statement
Depreciation appears as an operating expense on your income statement. It reduces your reported net income for the period, even though you didn’t make a cash payment. This non-cash expense lowers your taxable income, which is one reason depreciation matters for tax purposes.
Balance sheet
On your balance sheet, accumulated depreciation is subtracted from the asset’s original cost to show its net book value. As depreciation builds up over time, the net book value of your assets decreases. This gives you and anyone reviewing your financials a more realistic picture of what your assets are currently worth.
Cash flow statement
Because depreciation is a non-cash expense, it gets added back to net income in the operating activities section of your cash flow statement. This means depreciation reduces your taxable income without reducing your actual cash on hand, which can improve your cash flow position.
Section 179 expensing
Instead of depreciating an asset over several years, Section 179 lets you deduct the full purchase price in the year you buy it. For 2026, the maximum Section 179 deduction is $2,560,000.
The deduction phases out once your total equipment purchases exceed $4,090,000 in a single year. Small businesses often use it for an immediate tax benefit on qualifying equipment, vehicles, and software.
Bonus depreciation
Bonus depreciation is a federal tax incentive that lets you deduct part of an asset’s cost in the year you place it in service. The One Big Beautiful Bill Act restored 100% bonus depreciation for qualifying property acquired after January 19, 2025.
For 2026, that means you can deduct the full cost of eligible assets in year one. You can also combine bonus depreciation with regular MACRS depreciation if you choose a reduced rate.
Book vs. tax depreciation
Your financial statements (book depreciation) and your tax return (tax depreciation) often use different methods and timelines. For books, you might use straight-line over 10 years; for taxes, the IRS may require MACRS over five years. This creates temporary differences between your reported income and your taxable income, so tracking both keeps your financial reporting accurate and your tax filings compliant.
When to use straight-line depreciation
Choosing the right depreciation method depends on the type of asset and how your business uses it. Straight-line depreciation works best when an asset loses value at a steady, predictable rate over its lifetime.
Assets suited for straight-line depreciation
Some assets naturally fit the straight-line approach because their value decreases consistently from year to year.
- Office furniture and fixtures
- Buildings and structural improvements
- Residential and commercial rental property
- Leasehold improvements
- General office equipment like printers and phone systems
Assets better served by accelerated methods
Other assets lose most of their value in the first few years. For these, an accelerated method like double-declining balance or MACRS may give you a more accurate picture and a larger tax deduction early on.
- Computers and technology hardware
- Vehicles, especially those with high mileage
- Specialized manufacturing equipment
- Software with a short expected lifespan
If you’re unsure which method fits your situation, talk with your accountant. They can help you choose the approach that balances accurate financial reporting with the best tax outcome for your business.
Recording straight-line depreciation in your accounting system
Once you’ve calculated your annual depreciation, you need to record it in your books. If you use double-entry bookkeeping, each depreciation entry involves two accounts.
At the end of each period, you record a journal entry in two steps:
- Debit the depreciation expense account for the amount of depreciation calculated
- Credit the accumulated depreciation account for the same amount
The debit increases your expense, which lowers your net income for the period. The credit increases accumulated depreciation, which is a contra-asset account on your balance sheet that reduces the asset’s book value over time.
Using the office computer example from earlier, you’d debit depreciation expense by $200 and credit accumulated depreciation by $200 each year.
Cloud accounting software like Xero can help you set up fixed asset registers and automate these recurring journal entries. This saves you time and helps you avoid manual errors, so your books stay accurate throughout the year.
Track depreciation and manage your assets with Xero
Getting depreciation right keeps your financial statements accurate and your tax filings on track. With Xero’s cloud accounting software, you can manage your fixed assets, automate depreciation calculations, and keep your books organized in one place. Choose a plan today to get one month free and spend more time running your business.
FAQs on straight-line depreciation
Here are answers to common questions about straight-line depreciation.
What does depreciation mean in accounting?
Depreciation spreads the cost of a tangible asset over its useful life, so you recognize part of the cost each year. This matches the expense to the periods when the asset helps your business earn revenue.
What are the main methods for calculating depreciation?
The most common methods are straight-line, declining balance, double-declining balance, sum-of-the-years’-digits, and units of production. For tax purposes, most US businesses use MACRS, which the IRS requires for depreciating business property.
How does depreciation affect my business’s financial statements and taxes?
Depreciation lowers net income on your income statement and the book value of assets on your balance sheet. It’s added back on your cash flow statement as a non-cash expense, and it reduces your taxable income, which can lower your tax bill.
What is the difference between straight-line and accelerated depreciation?
Straight-line spreads the cost evenly across an asset’s useful life, while accelerated methods like double-declining balance record more depreciation early on. They often suit assets that lose value quickly, like technology equipment.
Can you change depreciation methods after you start?
Yes, though it’s worth checking with your accountant first. Your books treat it as a change in accounting estimate applied from then on, and for taxes you generally file IRS Form 3115.
What is the depreciable base of an asset?
The depreciable base is the asset’s original cost minus its estimated salvage value, which is the total you can depreciate over its life. For example, an asset that costs $10,000 with a $1,000 salvage value has a depreciable base of $9,000.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.