Accumulated depreciation: definition, examples and how to calculate it
Learn what accumulated depreciation is, where it sits on your balance sheet and how to calculate it.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Tuesday 6 October 2026
Table of contents
Key takeaways
- Recognise accumulated depreciation as a contra asset account with a credit balance that offsets the original cost of your fixed assets
- Calculate straight-line depreciation by subtracting salvage value from cost and dividing by useful life, then track the running total to find book value
- Record depreciation at the end of each accounting period by debiting depreciation expense and crediting accumulated depreciation
- Use non-cash depreciation expenses to reduce your taxable income, which lowers your tax bill while keeping cash in your business
What is accumulated depreciation?
Accumulated depreciation is the total depreciation recorded on a fixed asset since you acquired it. It’s held in a contra asset account that reduces the asset’s cost to its book value, also called its carrying amount.
This running total captures the wear and tear, obsolescence or loss of value recorded over time. Book value is the asset’s cost minus accumulated depreciation, and it shows what the asset is realistically worth today.
Indonesian businesses report under Indonesian Financial Accounting Standards (SAK), where fixed assets are covered by PSAK 216 Aset Tetap. This standard is the renumbered PSAK 16, effective 1 January 2024, and it’s aligned with International Accounting Standard IAS 16. Under its cost model, you carry an asset at cost less accumulated depreciation and any impairment losses.
Say your office furniture cost Rp50,000,000 and depreciates by Rp10,000,000 a year. After three years, accumulated depreciation is Rp30,000,000, leaving a book value of Rp20,000,000.
Machinery that cost Rp250,000,000 and depreciates by Rp25,000,000 a year works the same way. After six years, accumulated depreciation is Rp150,000,000, leaving a book value of Rp100,000,000.
Depreciation vs accumulated depreciation: what’s the difference?
Depreciation is the expense for a single period, while accumulated depreciation is the total of those expenses to date. Here’s how the two concepts differ.
Depreciation is a recurring expense that shows the decrease in an asset’s value over a set period, like a month or a year. You record it regularly as part of your accounting cycle.
Accumulated depreciation is the running total of all depreciation expenses recorded for an asset. It increases each time you add a new depreciation expense, growing larger as the asset ages.
Is accumulated depreciation an asset or a liability?
Accumulated depreciation is neither an asset nor a liability. It’s classified as a contra asset account, which offsets the original value of assets on your balance sheet.
Unlike liabilities, accumulated depreciation isn’t a debt you owe or an obligation you must fulfil. It simply reflects the reduction in an asset’s book value over time due to wear and tear, obsolescence or age.
A contra asset works differently from a standard asset. While you record it alongside your other assets, it carries a credit balance (negative value). This offsets the asset’s original cost to show its current book value, giving you a more realistic picture of what your assets are worth.
Is accumulated depreciation a debit or credit?
Accumulated depreciation is recorded as a credit on the balance sheet. This is because it’s a contra asset account, which carries a credit balance to offset the debit balance of the related asset.
When you record depreciation each period, you create this journal entry:
- Debit depreciation expense (increases expenses on the income statement)
- Credit accumulated depreciation (increases the contra asset on the balance sheet)
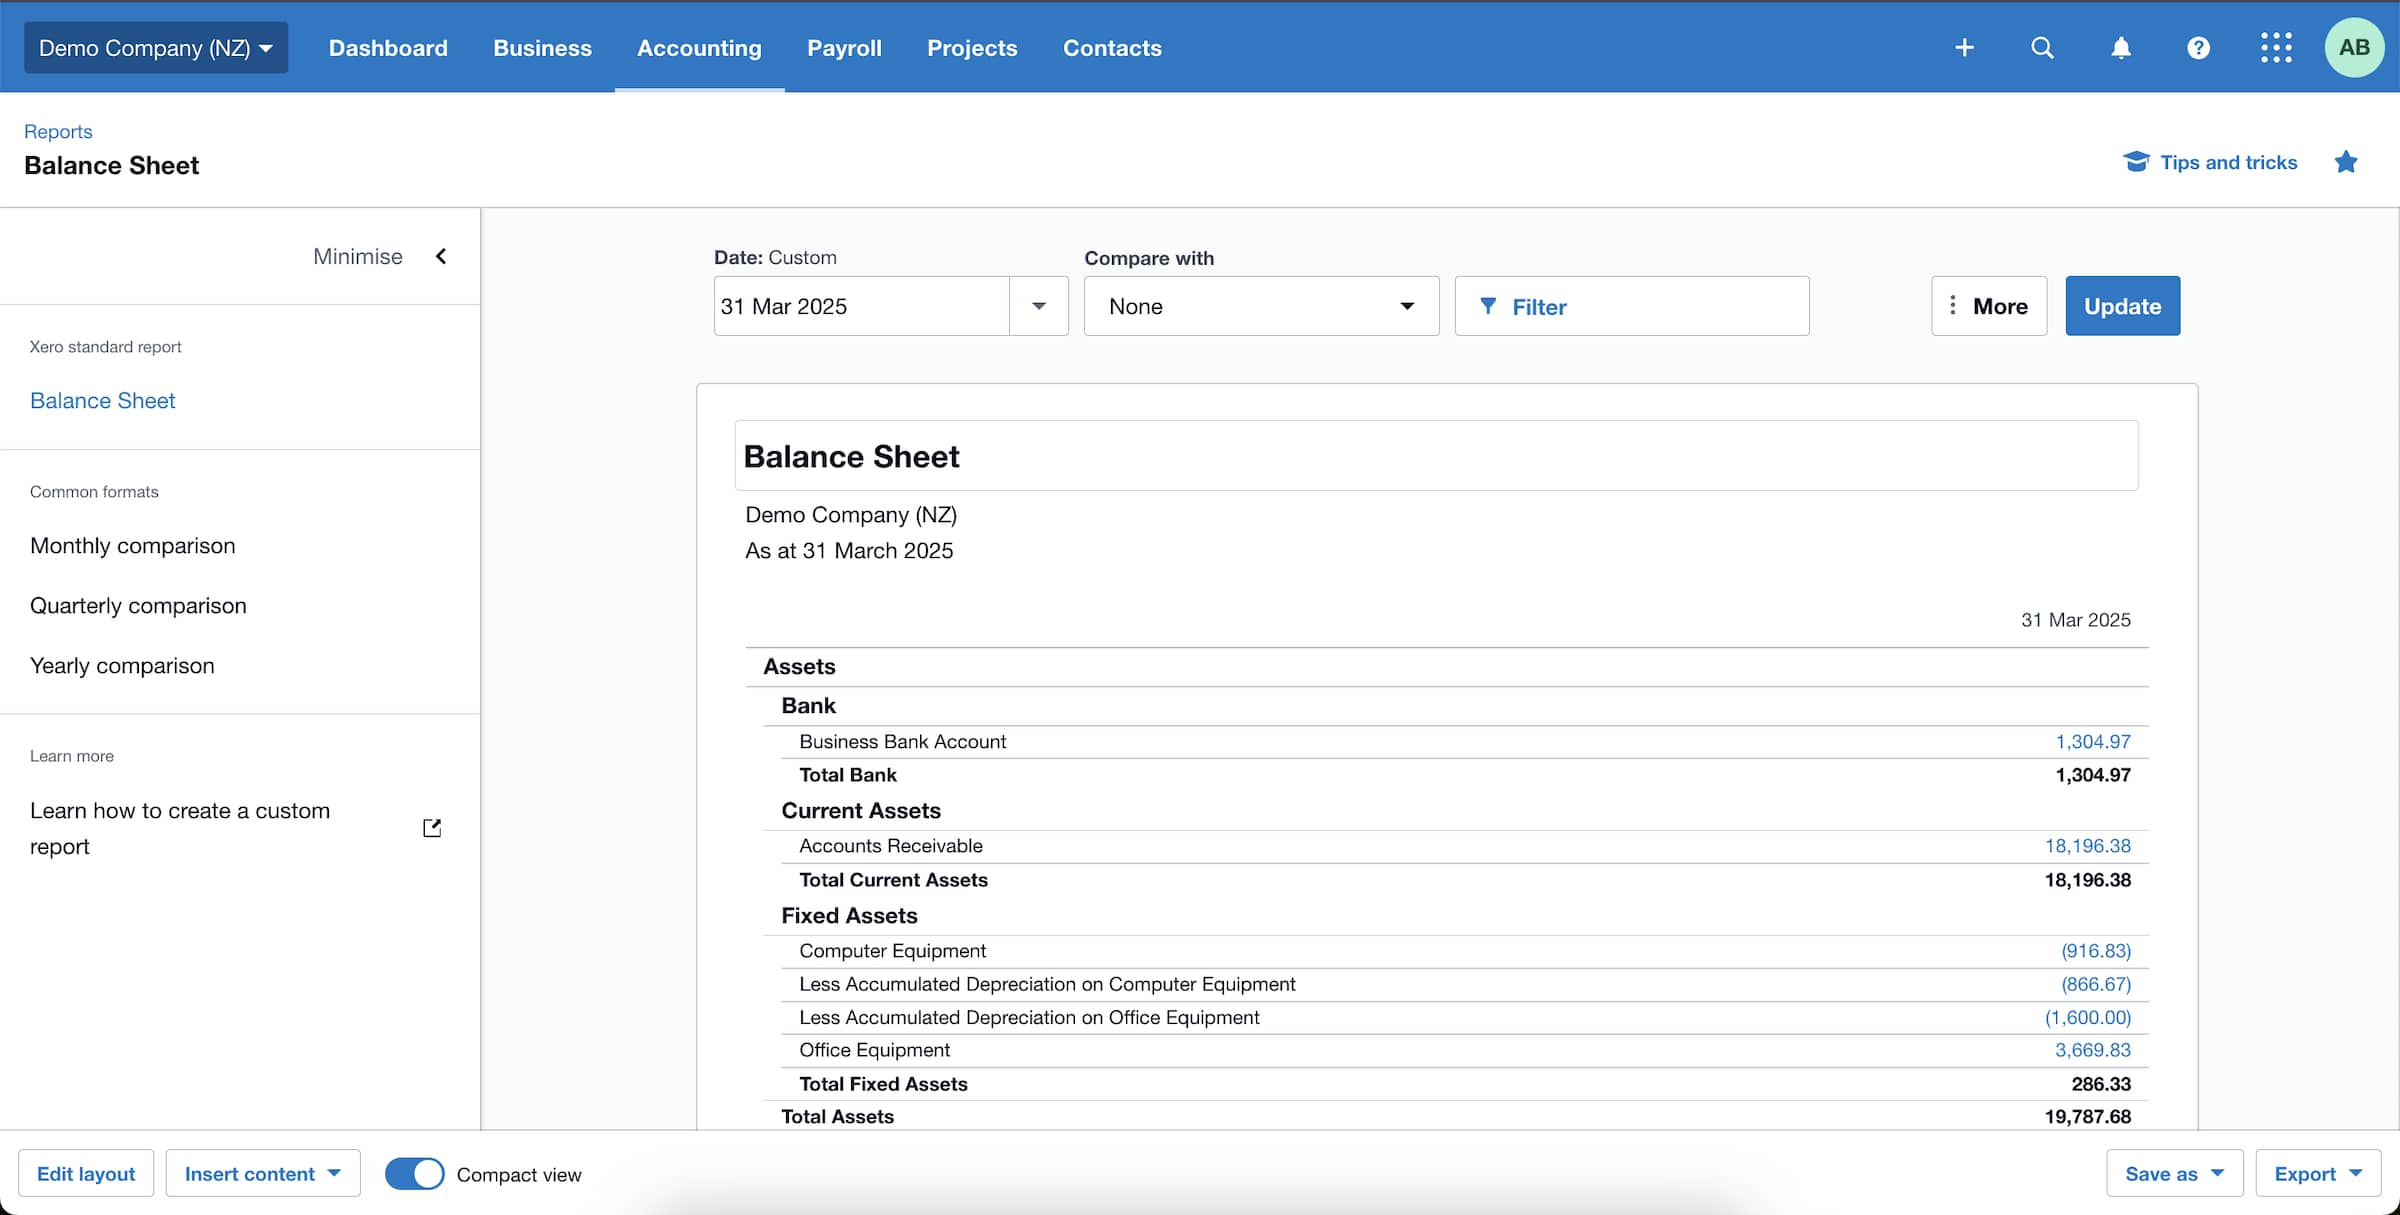
In accounting software like Xero, accumulated depreciation typically appears as a negative number under fixed assets. This credit balance reduces the asset’s original cost to show its current book value.
Where accumulated depreciation appears in financial statements
Accumulated depreciation affects your financial statements in different ways. It sits on the balance sheet, while the related depreciation expense flows through the income statement and cash flow statement.
Accumulated depreciation on the balance sheet
Accumulated depreciation appears under fixed assets (also called property, plant and equipment) on the balance sheet. It’s listed as a credit balance directly below the asset it relates to.
Your business sets a capitalisation threshold in its accounting policy to decide which purchases count as fixed assets. The balance sheet shows each asset’s original cost, then subtracts accumulated depreciation to display the net book value. This adjusted figure reflects what the asset is currently worth to your business.
Accumulated depreciation on the income statement
Accumulated depreciation doesn’t appear directly on the income statement. Instead, depreciation expense shows up as a line item that reduces your taxable income for the period.
As a non-cash expense, depreciation lowers your reported profits without requiring a cash outlay. This can reduce your tax bill while keeping cash available in your business.
In Indonesia, tax depreciation follows separate asset groups set by the Ministry of Finance, so your tax and book figures can differ. Check with your accountant to confirm how each asset is treated for tax.
Accumulated depreciation on the cash flow statement
Depreciation is added back to net income on the cash flow statement because it’s a non-cash expense. No money actually leaves your business when you record depreciation.
This adjustment shows your true operating cash flow, separate from accounting entries that don’t involve actual cash movement.
Accumulated depreciation example on a balance sheet
This example shows how accumulated depreciation changes the net book value of a vehicle on your balance sheet. The asset’s cost stays the same each year, while the depreciation total grows.
Say you buy a delivery van for Rp300,000,000 and depreciate it using the straight-line method over six years, with no salvage value. That’s Rp50,000,000 of depreciation a year.
After two years, your balance sheet shows vehicles at cost of Rp300,000,000, less accumulated depreciation of Rp100,000,000. That leaves a net book value of Rp200,000,000.
How to calculate accumulated depreciation
Calculating accumulated depreciation helps you track how much value your assets have lost over time. Here’s how to do it using the straight-line depreciation method, the most common approach for small businesses.
The straight-line depreciation calculation
The straight-line depreciation formula is:
Annual depreciation expense = (cost of asset – salvage value) ÷ useful life
Here’s what each term means:
- Cost of asset: the original purchase price
- Salvage value: the estimated amount you’ll receive when the asset is no longer usable (resale or scrap value)
- Useful life: the estimated years the asset will remain functional
These factors work together to determine your annual expense. A shorter useful life means higher yearly depreciation, and a higher salvage value means lower yearly depreciation.
Calculate straight-line depreciation
Follow these three steps to calculate depreciation.
- Calculate the annual depreciation expense: subtract the salvage value from the asset’s cost, then divide by its useful life.
- Track accumulated depreciation each year: add each year’s depreciation expense to the running total in your depreciation schedule.
- Calculate the asset’s book value: subtract accumulated depreciation from the asset’s initial cost.
Say an asset costs Rp10,000,000, has a salvage value of Rp1,000,000 and a useful life of five years. The annual depreciation expense is (Rp10,000,000 – Rp1,000,000) ÷ 5 = Rp1,800,000 a year.
Accumulated depreciation then grows by the same amount each year. It’s Rp1,800,000 after year one, Rp3,600,000 after year two and Rp5,400,000 after year three. It reaches Rp7,200,000 after year four and Rp9,000,000 after year five.
After three years, the asset’s book value is Rp10,000,000 – Rp5,400,000 = Rp4,600,000. After year five, the book value equals the Rp1,000,000 salvage value.
Other depreciation methods
While straight-line depreciation works well for most small businesses, other methods exist. Standards boards occasionally prohibit the use of certain approaches, such as revenue-based depreciation.
- Declining balance method: applies a fixed percentage to the remaining book value each year, resulting in higher depreciation early in the asset’s life
- Double-declining balance method: uses twice the straight-line rate, accelerating depreciation even further
These methods may suit businesses with assets that lose value quickly in their early years. For most small business needs, straight-line depreciation offers the simplest and most predictable approach.
Why accumulated depreciation matters for your business
Understanding accumulated depreciation helps you make better decisions about the assets your business relies on. It helps you:
- track how asset values change over time so you can plan replacements, upgrades and maintenance costs
- reduce your taxable income with depreciation charges, lowering your tax bill and keeping more cash available
- present accurate asset values to improve your chances of securing loans or attracting investors
- record depreciation consistently so your reported profit reflects the cost of using your assets
Track accumulated depreciation with Xero
Keeping accumulated depreciation up to date gives you an accurate view of what your assets are worth and what they cost you each year.
You can simplify these tasks with Xero, tracking assets and creating detailed depreciation schedules. You’ll get a clear view of fixed asset values and more accurate financial reporting.
To see how it works for your business, get one month free or learn how Xero supports your business.
FAQs on accumulated depreciation
Here are answers to common questions about accumulated depreciation.
How does accumulated depreciation affect cash flow?
Accumulated depreciation doesn’t directly affect cash flow because it’s a non-cash expense. However, it reduces your taxable income, which lowers your tax bill and keeps more cash in your business.
What happens to an asset’s accumulated depreciation when you sell it?
When you sell an asset, its accumulated depreciation is removed from your balance sheet. You compare the book value (cost minus accumulated depreciation) to the sale price to record a gain or loss on disposal.
What is the journal entry for accumulated depreciation?
The journal entry debits depreciation expense and credits accumulated depreciation. Record this entry at the end of each accounting period (monthly, quarterly or annually) to reflect the asset’s loss in value.
Is accumulated depreciation a current liability?
No, accumulated depreciation is a contra asset that reduces an asset’s book value over time. It sits apart from current and non-current liabilities, which are debts you owe, with current ones due within 12 months.
Can accumulated depreciation exceed the cost of an asset?
No, accumulated depreciation stops once it equals the asset’s depreciable amount (cost minus salvage value). After that, you stop recording depreciation expense even if you keep using the asset.
What is the difference between accumulated depreciation and book value?
Accumulated depreciation is the running total deducted from an asset’s cost since you bought it. Book value is what remains after that deduction, so it falls each period as accumulated depreciation rises.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.