Margin of safety formula: how to calculate your buffer
Learn the margin of safety formula to set sales targets, protect profit, and plan smarter.
Written by Shaun Quarton—Accounting & Finance Content Writer and Growth Marketer. Read Shaun's full bio
Written by Shaun Quarton—Accounting & Finance Content Writer and Growth Marketer. Read Shaun's full bio
Published Friday 6 November 2026
Table of contents
Key takeaways
- Calculate your margin of safety using the formula (Current sales – Break-even sales) ÷ Current sales to determine how far your sales can drop before your business starts losing money.
- As a rough rule of thumb, many businesses aim for a margin of safety of 20–25%, with 30% or higher giving a stronger buffer against unexpected downturns.
- Use your margin of safety to make key business decisions like setting sales targets, adjusting pricing, controlling costs, and evaluating new products or services.
- Track your margin of safety monthly or weekly if sales fluctuate significantly, as businesses with high fixed costs need higher margins than those with mostly variable costs.
What is the margin of safety?
(Current sales – Break-even sales) ÷ Current sales = Margin of safety
For example, Rp500,000,000 in current sales and a Rp300,000,000 break-even point gives (Rp500,000,000 – Rp300,000,000) ÷ Rp500,000,000 = 40%.
Margin of safety measures how far your sales can fall before reaching your break-even point, where revenue equals costs and your business breaks even. This financial buffer protects you against drops in demand or cost increases, and a wider margin means lower risk.
What is the margin of safety formula?
The margin of safety formula is:
(Current sales – Break-even sales) ÷ Current sales = Margin of safety
Here's what each component means:
- Current sales: your total revenue from selling goods and services over a specific period
- Break-even sales: the exact revenue needed to cover all fixed and variable costs, where your business makes zero profit and zero loss
For example, a business with Rp80,000,000 in current sales and a Rp60,000,000 break-even point would calculate:
Margin of safety = (Rp80,000,000 – Rp60,000,000) ÷ Rp80,000,000 = 0.25 (25%)
This means sales could drop by 25% before the business starts operating at a loss.
How to calculate margin of safety
Now let's break down the margin of safety calculation.
1. Find your current sales
Current sales is your total revenue over a specific period, whether actual figures or forecasted amounts. Your sales figures should be readily available through your existing sales tools.
If you need to forecast sales, use one of these methods:
- Analyse historical data: review your financial reports for past sales trends and seasonal patterns from your point of sale (POS) system, eCommerce platform, or accounting software like Xero.
- Conduct market research: study your target market, industry trends, and competitor performance.
- Gather qualitative insights: ask your sales team or industry experts for their input.
- Apply quantitative methods: use statistical analysis of historical and market data to predict future sales.
For example, a craft business tracking monthly sales through a POS system recorded Rp50,000,000 last month. This figure is used in the margin of safety calculation.
2. Calculate your break-even sales revenue point
For the margin of safety calculation, you need your break-even sales revenue. Here's the formula:
Fixed costs ÷ ((Sales price – Variable cost) ÷ Sales price) = Break-even sales
In this formula:
- Fixed costs are expenses that stay the same regardless of sales volume, such as salaries and rent
- Variable costs are expenses that change with sales volume, such as raw materials and sales commission
Learn more about variable costs and how they differ from fixed costs. Your accountant can also help you distinguish between them.
Continuing with the craft business example:
- Fixed costs: Rp20,000,000
- Variable costs: Rp50,000 per unit
- Sales price: Rp250,000 per unit
The break-even calculation:
Rp20,000,000 ÷ ((Rp250,000 – Rp50,000) ÷ Rp250,000) = Rp20,000,000 ÷ 0.8 = Rp25,000,000
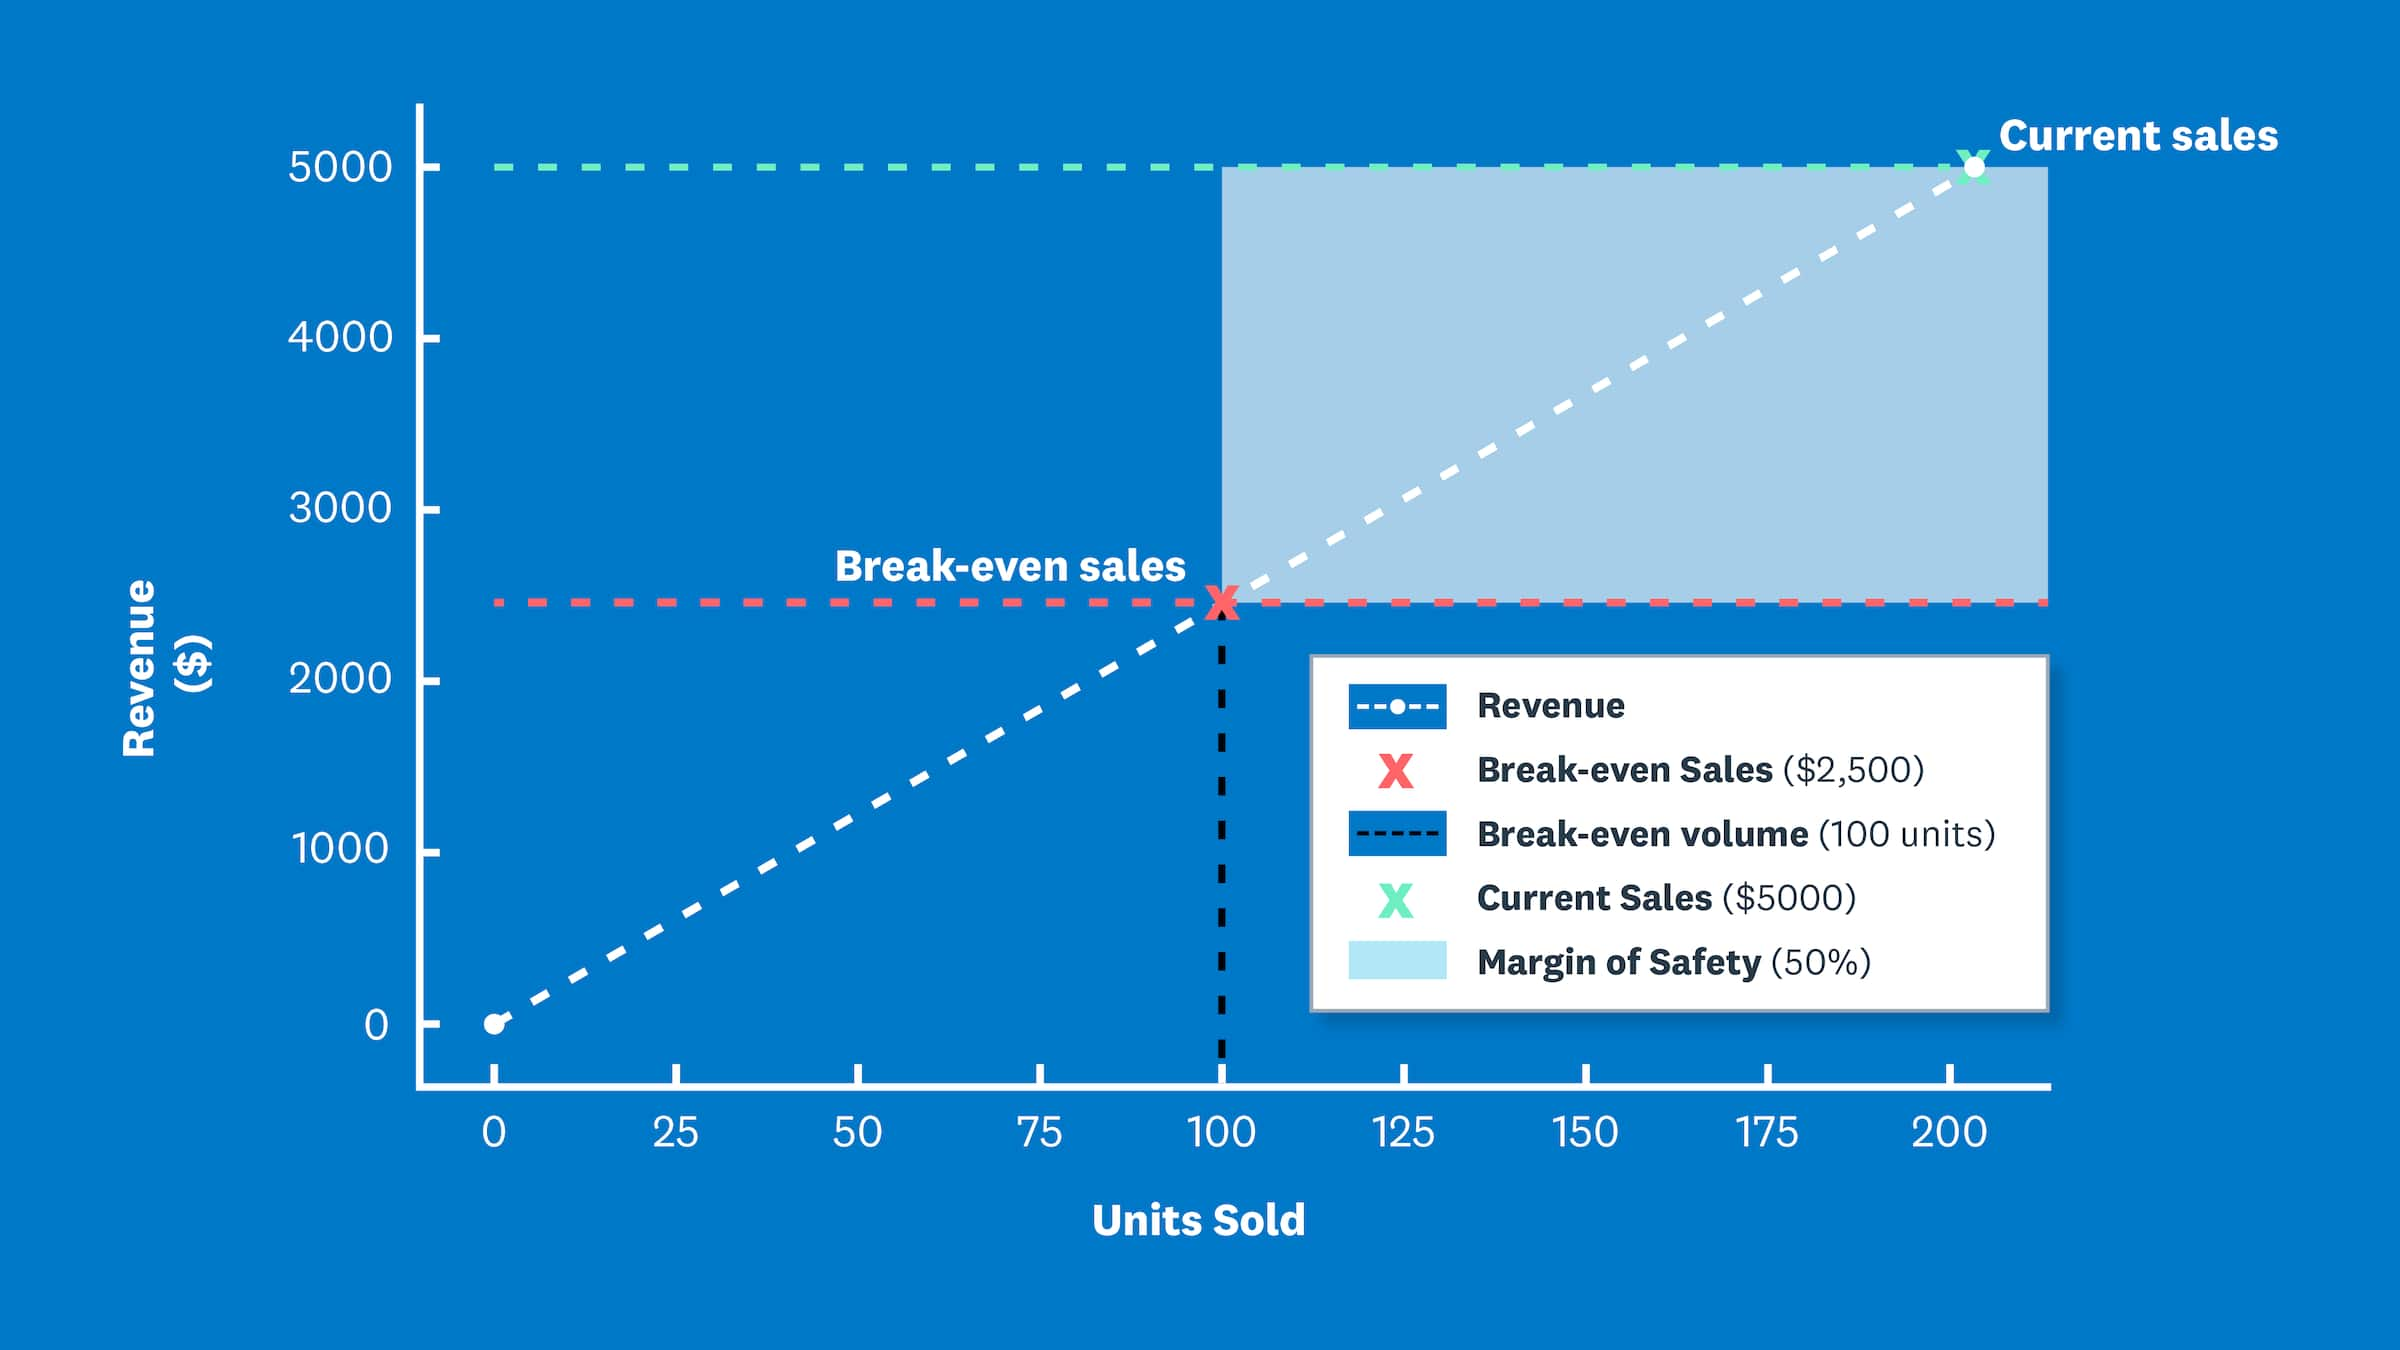
With a sales price of Rp250,000, the business needs Rp25,000,000 in revenue (100 units) to break even.
3. Apply the margin of safety formula
Apply the margin of safety formula:
(Current sales – Break-even sales) ÷ Current sales = Margin of safety
The result is your margin of safety ratio, the percentage by which sales can fall before your business starts operating at a loss.
For the craft business with Rp50,000,000 in current sales and a Rp25,000,000 break-even point:
(Rp50,000,000 – Rp25,000,000) ÷ Rp50,000,000 = 0.5 = 50%
This 50% margin of safety means sales could fall by half before the business reaches its break-even point.
What is a good margin of safety percentage?
A good margin of safety percentage depends on your business type, cost structure, and risk tolerance. These rough rules of thumb can help you read your result:
- 30% or higher: strong financial buffer with low risk
- 20–25%: reasonable margin, especially for businesses with mostly variable costs
- 10–20%: moderate risk; monitor closely and look for ways to improve
- Under 10%: high risk; you're operating close to break-even with little room for error. For example, one company analysis showed that with a breakeven point of $3.95M on sales of $4.2M, their resulting margin of safety of 5.8% left little room for unexpected downturns.
Variable cost businesses, where most costs change with sales volume, can often operate safely with lower margins because costs drop when sales drop. Fixed cost businesses, with high rent, salaries, or equipment costs, need higher margins because those costs remain even when sales fall.
Your business stage also matters. Established businesses with predictable revenue can accept lower margins, while growing businesses facing market uncertainty may need a larger buffer.
For example, a margin of safety of 40% means your sales could drop by 40% before you start losing money. A margin of 15% leaves much less room for a downturn.
The importance of the margin of safety for your small business
Margin of safety is essential to your risk management strategy because it shows how far sales can fall before your business starts making a loss.
- High margin of safety: indicates low risk, meaning your business can absorb small shifts without much disruption. For instance, one case study of a company with a 32% margin of safety showed that its sales could decrease by $72,000 from their current level before it would be at risk of suffering a loss.
- Low margin of safety: your risk is higher, and you're operating close to your break-even point with less room to manoeuvre.
External shocks, like a jump in supplier prices, increase your variable costs and push up your break-even point. This eats into your margin of safety and leaves your business exposed to further cost increases or falling sales.
How the margin of safety supports your business decisions
Your margin of safety helps you make important decisions across your small business. A 2025 review of cost-volume-profit research in the Journal of Public Administration and Social Welfare Research cites findings that most managers in manufacturing firms rely on cost-volume-profit analysis to make quick cost-saving decisions during periods of economic instability.
- Set performance targets: calculate a clear break-even point to establish achievable sales targets that keep you profitable.
- Adjust pricing: review your pricing if your margin of safety is shrinking so each sale contributes enough to cover costs.
- Control costs: treat a low margin of safety as a signal to cut costs and protect your buffer.
- Evaluate new products or services: assess how the costs of a proposed new product affect your margin of safety and ability to turn a profit.
Other metrics that work with margin of safety
Margin of safety works best when combined with other key financial metrics. Using it alongside cost-volume-profit (CVP) analysis gives you a clearer view of your profitability and risk, a practice that a study of Sri Lankan companies linked to more efficient decision-making.
Track your margin of safety with Xero
Xero brings all your accounting data into an easy-to-read set of reports, so you have the up-to-date sales and cost figures you need to work out your margin of safety.
With accurate, up-to-the-minute financial data in Xero, you can recalculate your margin of safety whenever you need to and base every pricing or cost decision on reliable numbers. Get one month free and see how Xero makes it easier to keep an eye on your financial buffer so you can focus on growing your business.
FAQs on margin of safety
Here are answers to common questions about calculating and using your margin of safety.
How often should I calculate my margin of safety?
Calculate your margin of safety monthly for most businesses, or weekly if your sales fluctuate significantly. At minimum, review it quarterly to catch trends before they become problems.
Can my margin of safety be negative, and what does that mean?
Yes, a negative margin of safety means you're operating below your break-even point. This requires immediate action to increase sales, reduce costs, or both.
What's the difference between margin of safety and profit margin?
Margin of safety measures how far your sales can drop before you start losing money. Profit margin measures how much profit you make as a percentage of each sale. They're related but track different aspects of financial health.
How can I improve my margin of safety?
Improve your margin of safety by increasing sales revenue, reducing fixed costs, lowering variable costs per unit, or raising prices. Often a combination of these approaches works best.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.