Tax deduction
A tax deduction lowers your taxable income. See what Indonesian businesses can claim and which records to keep.
Published Thursday 22 October 2026
Table of contents
Key takeaways
- A tax deduction is a business cost you subtract from your income, so you pay tax on a smaller amount. If a cost is partly personal, you can only claim the business share.
- Deductions matter when you keep full books. If you use the deemed-profit norm or a final tax on turnover, expenses don’t change your tax.
- Indonesian law requires you to keep bookkeeping records and supporting documents for 10 years, so store every receipt and invoice you claim.
- Using accounting software to record and sort expenses as they happen makes it easier to claim every eligible deduction at tax time.
Tax deductions definition
A tax deduction is a business expense that reduces your taxable income, so you pay less tax. You subtract eligible expenses from your income to arrive at the amount your income tax is based on.
Many everyday business costs can count as deductions. Common deductible expenses for small businesses include:
- office costs, such as rent, utilities, equipment and supplies
- business travel, such as transport and accommodation
- professional services, such as legal and accounting fees
- marketing, such as advertising, website costs and promotional materials
In Indonesia, the Directorate General of Taxes (DJP) applies the Income Tax Law (UU PPh). Article 6 of UU PPh allows you to deduct the costs of earning, collecting and maintaining your income. Article 9 lists non-deductible costs, and both were last amended by Law 7 of 2021 on Harmonisation of Tax Regulations (UU HPP).
These rules come into play when your tax is worked out from your bookkeeping. Individuals with turnover under Rp4,800,000,000 a year can choose the deemed-profit norm (NPPN) instead. It sets net income as a percentage of turnover, so actual expenses aren’t deducted.
Some businesses pay a final tax on turnover, which also leaves expenses out of the calculation. Government Regulation (PP) 20/2026 sets a 0.5% final rate for individuals and one-person companies from 22 April 2026. Newly registered limited liability companies (PT), limited partnerships (CV) and firms can’t use it, so check which method applies to you first.
Example of a tax deduction calculation
A worked example shows how deductions shrink the income you pay tax on. Here’s how it looks for a business that keeps complete books.
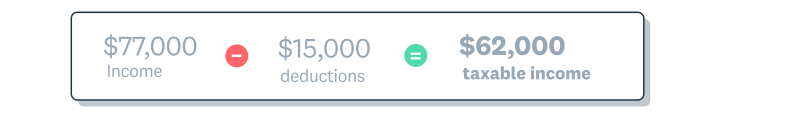
Jo owns a photographic studio and earned Rp770,000,000 last year. She has Rp150,000,000 in deductible business expenses, which reduces her taxable income to Rp620,000,000.
Rp770,000,000 (income) minus Rp150,000,000 (deductions) = Rp620,000,000 (taxable income)
Jo pays tax on Rp620,000,000 instead of her full Rp770,000,000, so she keeps more of what her studio earns. Her claim holds up because each expense meets the conditions below.
Business purpose requirement
For an expense to qualify as a tax deduction, it needs a genuine business purpose. A camera is deductible for a photographer, but not for a baker.
Personal vs business expenses
Some of what you spend is fully deductible and some isn’t, so you need to separate personal and business costs. Expenses fall into three groups:
- personal expenses, such as groceries and personal clothing, which you can’t deduct
- mixed-use expenses, where you claim only the business share (80% business use of a phone means an 80% deduction)
- business-only expenses, which are fully deductible when used solely for work
Record keeping essentials
Each deduction Jo claims needs proof behind it. Keep receipts for every expense you plan to deduct, as good documentation supports your claims if DJP audits your return.
Types of tax deductions for small business
Now that you know how deductions work, you can look at what qualifies. The groups below follow the deductible costs set out in Article 6 of UU PPh.
Costs of earning income
Most deductions are direct costs of earning, collecting and maintaining your income. They include:
- materials used in your business
- wages, salaries and allowances for your staff
- interest, rent and royalties
- business travel
- waste treatment
- insurance premiums
- promotion, sales and administration costs
- taxes other than income tax (PPh)
Business operating costs
These are the day-to-day running costs of your business. They include rent for your premises, staff salaries and office supplies. Tracking them each month keeps your deduction total accurate and up to date.
Home office deductions
If you run your business from home, some household costs, such as electricity and internet, may partly relate to your work. Claim only the business-use portion, and keep records that show how you worked out the split.
Vehicle and travel expenses
Business travel counts as a cost of earning income. If you use a vehicle for work and private trips, the same apportionment approach applies. Claim only the business share of running costs, and back it up with records of each trip’s date, destination and purpose.
Other deductible costs
Beyond running costs, a few other items can reduce your taxable income. These include:
- contributions to a pension fund approved by the Financial Services Authority (OJK)
- losses from selling or transferring business assets
- foreign exchange losses
- research and development carried out in Indonesia
- bad debts that meet the required conditions
Depreciation and amortisation
When you buy equipment, tools or vehicles, you claim their cost over time through depreciation. Article 9 requires you to depreciate or amortise assets with a useful life of more than one year. You spread their cost instead of deducting it upfront.
Indonesian tax depreciation groups assets by type, and each group has its own useful life. A registered tax consultant (konsultan pajak) can confirm which group your assets fall into.
What you can’t claim as a tax deduction
Knowing what you can claim is half the picture; the other half is what you can’t. Article 9 of UU PPh lists the costs that are never deductible, however closely they seem linked to your business.
Expenses you can’t claim include:
- personal costs, including the private share of mixed-use expenses
- profit distributions, such as dividends
- income tax (PPh) itself
- administrative and criminal tax sanctions
- personal insurance premiums paid by individuals
- gifts and donations, apart from the qualifying exceptions
Non-deductible costs still reduce your net profit in your books, so you add them back when you work out taxable income. If you’re unsure about a specific expense, check the DJP website at pajak.go.id or speak with a registered tax consultant.
How to claim tax deductions
Once you know which expenses qualify, claiming them comes down to a clear process and good records kept throughout the year. Follow these steps to claim your deductions:
- Confirm you spent the money yourself and weren’t reimbursed.
- Check the expense relates to earning, collecting or maintaining your income.
- Keep a record, such as a receipt or invoice, to prove the expense.
- Calculate the deductible amount, separating any personal use and non-deductible items.
- Include your deductible expenses in your annual income tax return.
Using accounting software to track deductions
Tracking expenses by hand makes it easy to miss deductions or make errors. Accounting software helps you capture and categorise expenses as they happen, so you can claim every eligible deduction at tax time.
Record keeping requirements
Good records are the foundation of every deduction claim. They prove your income and expenses, make tax time smoother and support you if DJP audits your return.
What records to maintain
Keep records for all your business transactions, including invoices, receipts, bank statements and contracts. For expenses, your records should show:
- what you bought
- when and where you bought it
- how much you paid
- how it relates to your business
How long to keep records
Once your records are in order, plan for how long you’ll hold them. Under Article 28(11) of the General Provisions and Tax Procedures Law (UU KUP), you need to keep bookkeeping records and supporting documents for 10 years.
Digital vs physical records
Over 10 years, that’s a lot of paper. You can keep records in paper or digital form. Digital records are easier to store, search and back up, so use software to snap photos of receipts.
Common tax deduction mistakes to avoid
Even with the right records in place, a few common slips can cost you. Knowing them helps you claim with confidence at tax time.
Mixing personal and business costs
You can only claim the business-use portion of an expense. If you use your car for business and private trips, separate the costs and claim only the business part.
Insufficient documentation
Every deduction needs a record to prove it. Keep clear, organised records for each claim, and store them securely for the full retention period.
Overclaiming risks
If you claim costs you aren’t entitled to, DJP can correct your return when it reviews or audits it. A correction can increase the tax you owe and lead to sanctions. Check borderline expenses with your accountant or a registered tax consultant before you claim them.
Simplify your tax deductions with Xero
Tracking every receipt and sorting every expense through the year can feel like a big job. Xero accounting software connects to your bank feeds, matches transactions and organises expenses as they come in. Your deductions are ready when you need them.
You can capture receipts on your phone, categorise expenses as you go and run a profit and loss statement whenever you need one. Your accountant or bookkeeper can access your data directly, which saves back-and-forth at year end. Get one month free and see how much easier tax time can be.
FAQs on tax deductions
Here are answers to some common questions about tax deductions in Indonesia.
What records do Indonesian businesses need to keep?
Under UU KUP Article 28(11), you need to keep bookkeeping records, supporting documents and electronically processed data in Indonesia for 10 years. Storing them digitally makes them easier to find if DJP asks to see them.
What’s the difference between a tax deduction and a tax credit?
A tax deduction reduces your taxable income before tax is calculated. A tax credit (kredit pajak), such as PPh 22, 23 or 25 you’ve already paid, reduces the tax payable on your annual return.
Can I claim personal expenses as business deductions?
Record personal costs paid from your business account as owner drawings (prive) instead of expenses. That keeps them out of your deduction claim and shows your true business costs.
Are pension fund contributions tax deductible?
Contributions are deductible when you pay them to a pension fund approved by the Financial Services Authority (OJK), under Article 6 of UU PPh. Check that the fund holds this approval before you claim.
Are personal insurance premiums tax deductible?
Premiums for personal cover, such as life or health insurance, that you pay as an individual aren’t deductible under Article 9(1)(d) of UU PPh.
How do I know if an expense is tax deductible?
Ask two questions: does the cost help you earn, collect or maintain income, and is it absent from the non-deductible list? If it’s borderline, a registered tax consultant (konsultan pajak) can confirm how to treat it for your business.
Related terms
Learn more about tax deductions
Handy resources
Advisor directory
You can search for experts in our advisor directory
Try Xero for free
Try Xero’s fast, simple, powerful online accounting software for your small business
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.