What are retained earnings?
Learn what retained earnings are, how to calculate them and when your company can pay dividends.
June 2023 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- Retained earnings are the net profit your company has kept over its life after paying dividends. They sit in the equity section of your balance sheet.
- To calculate them, add this period’s net profit after tax to your opening balance and subtract dividends. A net loss reduces the balance instead.
- They’re an accounting figure, so a healthy balance can sit alongside a tight bank balance. Profit is often tied up in unpaid invoices or stock.
- A Malaysian private limited company (Sdn Bhd) can pay dividends only from available profits and only if it stays solvent for 12 months afterwards. From year of assessment (YA) 2025, individuals pay 2% tax on dividend income above RM100,000 a year.
Retained earnings definition
Retained earnings are the total net profit your business has kept since it started, after paying dividends to shareholders. They’re the share of past profit you’ve reinvested in the company.
The Corporate Finance Institute’s accounting guide places this figure under shareholders’ equity on the balance sheet at each period end. It’s an equity balance, separate from the cash in your bank account.
Think of it as a running scorecard for your company. Each profitable year adds to the total, while losses and dividends bring it down.
Retained earnings formula and how to calculate them
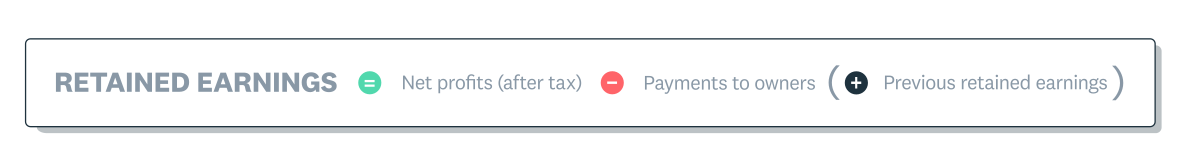
You work out the figure by taking last period’s closing balance, adding this period’s net profit after tax and subtracting dividends. The formula looks like this:
Retained earnings = opening retained earnings + net profit after tax (or − net loss) − dividends paid
Net profit is gross profit minus all other operating expenses and taxes. You’ll find it at the bottom of your profit and loss statement.
How to calculate retained earnings
Follow these steps at the end of each accounting period. You’ll need last period’s balance sheet and this period’s profit and loss statement.
- Find your opening retained earnings on the previous period’s closing balance sheet
- Take net profit after tax, or the net loss, from this period’s profit and loss statement
- Total the dividends declared to shareholders during the period
- Add the net profit to the opening balance, then subtract the dividends to get your closing figure
Retained earnings worked example
Say your Sdn Bhd starts the year with RM50,000 in retained earnings. During the year, it earns RM30,000 in net profit after tax and pays RM10,000 in dividends to shareholders.
Retained earnings = RM50,000 + RM30,000 − RM10,000 = RM70,000
Your closing balance of RM70,000 becomes next year’s opening figure. It’s the profit your company has built up to reinvest or hold as a buffer.
Retained earnings vs cash
This balance measures profit kept in the business, while cash is the money in your bank account. Profit you’ve earned can be tied up in unpaid invoices and stock well before it turns into spendable money.
Say your company earns RM40,000 in net profit after tax this year and pays no dividends. Your equity rises by RM40,000, and here’s where that profit sits:
- RM16,000 in customer invoices still waiting to be paid, recorded as accounts receivable
- RM12,000 in extra inventory bought for next quarter’s orders
- RM6,000 in new equipment for your workshop
- RM6,000 in your bank account as extra cash
Assuming nothing else changes, you’re RM40,000 better off on paper but have only RM6,000 more to spend. Tracking cash flow alongside profit shows you what you can afford before you plan a dividend or a big purchase.
What affects retained earnings
The balance moves each period with your profit and with what you pay out to shareholders. These are the main drivers:
- Net profit after tax, which increases the balance
- Net losses, which reduce the balance
- Dividends declared to shareholders, which reduce the balance
- Prior-period adjustments, which correct past accounting errors and can move the balance either way
Longer-term factors shape the figure too. A newer company has had fewer profitable years to build it up. Your dividend policy also decides how much profit stays in the business each year.
Negative retained earnings
A negative balance happens when your accumulated losses are bigger than your accumulated profits. You’ll often see this labelled as an accumulated deficit or accumulated losses in the equity section.
A few situations commonly push the balance below zero.
- Operating losses over several years
- Large one-off costs, such as writing off damaged stock or equipment
- Start-up costs in a new business’s first years
- Heavy spending on growth, such as marketing or hiring, before sales catch up
For a Sdn Bhd, accumulated losses generally prevent the company from paying dividends. The Companies Act 2016 requires distributions to come from available profits, so you’ll usually need to rebuild profits first.
Lenders may also look more closely at a business with an accumulated deficit. For an early-stage company investing to grow, a deficit that shrinks year on year can still tell a positive story.
How to interpret retained earnings
This balance shows how much profit your business has kept over time, and the trend tells you more than any single year. Read it alongside your company’s age and recent investment decisions.
A rising balance usually means your business is consistently profitable and reinvesting in itself. It also puts you in a stronger position when you want to expand or ride out a slow patch.
A falling or negative balance can be normal after a big investment or in a company’s early years. If it keeps falling with no plan behind it, take a closer look at your margins and costs.
Retain earnings or pay dividends
Once your company has built up profit, you can keep it in the business or pay some of it to shareholders as dividends. In Malaysia, the law sets clear conditions before any dividend leaves the company.
Companies Act 2016 dividend rules
Section 131 of the Companies Act 2016 lets a company make a distribution to shareholders only out of available profits, and only if it’s solvent. Both conditions have to be met.
Section 132 treats a company as solvent if it can pay its debts as they fall due within 12 months after the distribution. Naidu Chambers’ guide to the solvency test describes it as a forward-looking cash flow test.
The directors who authorise a dividend must be satisfied the company will be solvent immediately after it’s paid. As Datamet’s dividend compliance update notes, paying a distribution that breaks these rules is an offence for the company and its officers.
How dividends are taxed in Malaysia
Malaysia uses a single-tier system: your company pays income tax on its profits, and dividends are then exempt in shareholders’ hands. There’s one exception for individual shareholders.
From YA2025, individuals pay 2% tax on annual dividend income above RM100,000 from Malaysian resident companies, after eligible deductions. According to PwC’s Malaysia tax summary, this covers resident and non-resident individuals, and it still applies for YA2026.
Choosing between reinvesting and dividends
Keeping profit in the company funds growth without borrowing, while dividends reward shareholders and can give owner-directors personal income. You can also pay a smaller dividend and keep the rest.
These questions can help you decide how much to pay out.
- Will the company still pass the 12-month solvency test after the payment?
- Are growth plans or loan repayments coming up soon?
- Does your cash balance, as well as your accumulated profit, cover the dividend?
- Will the dividend push any shareholder’s annual dividend income above RM100,000?
What are retained earnings used for?
Profit you keep lets you fund your company’s future from its own earnings, without taking on a loan or bringing in new investors. That internal funding is especially useful when cash is tight or borrowing is expensive.
Here’s where businesses commonly put retained profit to work.
- Covering day-to-day costs like rent and supplies during slower months
- Buying equipment or opening a new location
- Developing and testing new products or services
- Building a cash reserve for unexpected disruptions
- Paying down loans early to cut interest costs
- Boosting working capital so you can take on bigger orders
A strong balance can also help when you do borrow. Lenders often review your equity when assessing a loan application, and accumulated profit can make up a large part of it.
Where retained earnings appear in financial statements
You’ll find this figure in the equity section of your balance sheet, alongside share capital and any other reserves. Its movement over the year is shown in a separate statement.
Retained earnings on the balance sheet
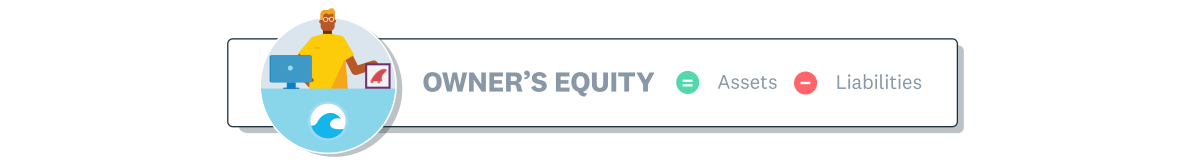
Your balance sheet follows a simple equation: owner’s equity = assets − liabilities. Accumulated profit is part of that equity, so it tracks the value your business holds after its debts.
When you use retained profit to pay off a loan, your cash and your liabilities both fall. When you spend it on equipment, cash becomes a different asset, and your equity stays the same.
Statement of changes in equity
Malaysian companies report under Malaysian Financial Reporting Standards (MFRS) or the Malaysian Private Entities Reporting Standard (MPERS). Private entities can choose either framework, as the MPERS announcement summary from IAS Plus explains. Under both, the year’s movement in retained earnings appears in the statement of changes in equity.
MPERS also lets you use a combined statement of income and retained earnings instead, according to a Malaysian Accounting Standards Board (MASB) framework comparison. This option applies when the only equity changes that year come from specific items, such as profit or loss and dividends.
Companies lodge their financial statements and an annual return with the Companies Commission of Malaysia (SSM) each year, as PwC Malaysia’s annual compliance guide explains. Keeping your equity figures accurate all year makes that lodgement easier.
Retained earnings vs net profit and revenue
The retained figure builds on net profit, which in turn starts with revenue. Here’s how they compare.
Retained earnings vs net profit
Net profit is your profit for one accounting period: gross profit minus all other operating expenses and taxes. Retained earnings add up every period’s net profit or loss since the business began, minus dividends.
Think of net profit as this year’s result and the retained figure as the running total you’ve kept.
Retained earnings vs revenue
Revenue is the total money your business brings in from sales before any costs come off. It’s the top line of your profit and loss statement.
To reach the retained figure, subtract cost of goods sold for gross profit, then operating expenses and tax for net profit, then dividends. A business with high revenue can still keep little profit if its costs or payouts are high.
Retained earnings for sole proprietors and partnerships
Sole proprietorships and partnerships track kept profit differently from companies. Profit you leave in the business builds up in your capital account, and money you take out is recorded as drawings.
Capital accounts and drawings
Each year, your share of the business profit is added to your capital account and your drawings are taken off. It works much like a company’s retained profit and dividends, with no dividend declaration or solvency test needed.
Here’s how drawings play out in your books.
- You move money from the business account to your personal account
- Your capital account falls by the amount you withdraw
- Your equity on the balance sheet falls by the same amount
- Your taxable profit stays the same, because drawings reduce your equity rather than counting as a business expense
How sole proprietors and partners are taxed
As a sole proprietor, you’re taxed on your business profit as personal income, whether or not you withdraw it. You report it on Form B to the Inland Revenue Board of Malaysia (LHDN), as ClearTax’s sole proprietorship guide sets out.
A partnership pays no income tax itself. Instead, it files Form P to show its profit and how it’s split. Each partner then reports their share on their own Form B, as MyTaxMate’s partnership tax guide and ClearTax’s Form B filing guide explain.
Tracking your drawings closely shows you how much the business can comfortably spare.
Track and manage retained earnings with Xero
Knowing your accumulated profit helps you decide with confidence when to reinvest and when a dividend is safe to pay. That starts with accurate, up-to-date numbers.
Xero accounting software keeps your books current with automated bank feeds, so your balance sheet reports show your equity position whenever you need it. Check profit and cash side by side before you declare a dividend. Choose a plan that suits your business and get one month free.
FAQs on retained earnings
Here are quick answers to common questions Malaysian business owners ask about this figure.
Are retained earnings an asset?
Retained earnings sit in equity on your balance sheet, where they show how much of your assets has been funded by profit you’ve kept. The profit they represent is held in assets such as cash, stock, equipment or money customers owe you, which appear on their own lines.
Are retained earnings taxed in Malaysia?
Your company pays income tax on its chargeable profit before that profit is retained, and keeping it adds no further tax. Tax applies again only when an individual shareholder receives dividends above RM100,000 in a year.
How often should you calculate retained earnings?
You’ll calculate them at least once a year when you prepare your annual financial statements. Checking monthly or quarterly gives you an early read before you plan dividends or big purchases.
What’s the difference between retained earnings and reserves?
Reserves is the broader equity heading, and retained earnings are the one built from accumulated profit. Other reserves, such as a revaluation reserve, come from items like revaluing property rather than trading profit.
Do retained earnings include share capital?
Share capital is the money shareholders put into the company in exchange for shares, and it sits on its own line in equity. Total equity is share capital plus retained earnings plus any other reserves.
Can a Sdn Bhd pay dividends if it has accumulated losses?
Generally not, because distributions must come from available profits and the company must also pass the solvency test. A single profitable year may not be enough if earlier losses still outweigh it, so check with your company secretary before declaring a dividend.
Related terms
Learn more about retained earnings
Handy resources
Advisor directory
You can search for experts in our advisor directory
Finance your business
Learn 14 ways to finance your business and help turn it into a profit machine
Financial reporting
Keep track of your performance with accounting reports
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.