Retained earnings: what they are and how to calculate them
Learn what retained earnings are, how to calculate them and how Irish dividend rules apply.
June 2023 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- Retained earnings are the net profits your company has kept rather than paid out to shareholders. Irish accounts often show them as the profit and loss reserve.
- To calculate them, take opening retained earnings, add net profit after tax (or subtract a loss) and subtract dividends paid.
- An Irish limited company can only pay dividends out of profits available for distribution, and it must withhold 25% dividend withholding tax.
- Healthy retained earnings help you fund growth and borrow on better terms, while close companies should watch for a surcharge on some undistributed income.
Retained earnings definition
Retained earnings are the total net profits your company has kept since it started, after paying dividends to shareholders. It’s the money you’ve reinvested in the business instead of taking it out.
On your balance sheet, retained earnings sit under capital and reserves, also called shareholders’ funds. Irish accounts often label this line the profit and loss reserve.
Each year your company makes a profit and keeps some of it, the balance grows. Think of it as a savings jar the business fills with profit and dips into when it pays dividends.
Retained earnings formula and how to calculate them
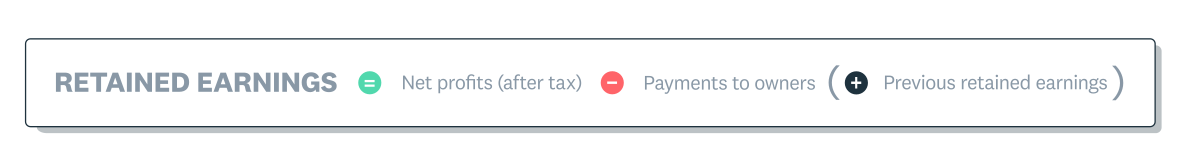
You calculate retained earnings by adding this period’s profit to last period’s balance and taking away dividends. The formula looks like this:
Retained earnings = opening retained earnings + net profit after tax (or − net loss) − dividends paid
Each part of the formula comes straight from your accounts:
- opening retained earnings are the balance carried forward from the end of the previous period
- net profit after tax is what’s left once you subtract all expenses and corporation tax from income
- a net loss reduces the balance instead of adding to it
- dividends paid are the distributions made to shareholders during the period
Say your company starts the year with €50,000 in retained earnings. During the year, it makes €30,000 in net profit after tax and pays €10,000 in dividends to shareholders.
Retained earnings = €50,000 + €30,000 − €10,000 = €70,000
Your closing balance is €70,000. That’s the profit your company has built up and kept, ready to reinvest or hold as a cushion.
Step-by-step calculation
You can work out retained earnings in three steps using your year-end figures. Here’s the order to follow:
- Find your opening retained earnings on last year’s balance sheet.
- Add this year’s net profit after tax, or subtract a net loss, from your profit and loss account.
- Subtract the dividends paid or declared during the year to get your closing balance.
Statement of retained earnings
A statement of retained earnings shows how the balance moved from the start of the year to the end. Under FRS 102, the financial reporting standard for the UK and Republic of Ireland, this movement usually appears in the statement of changes in equity.
Some smaller companies use a combined statement of income and retained earnings instead. Either way, it starts with the opening balance, adds the year’s profit and deducts dividends.
This statement links the profit and loss account to the balance sheet. It shows how each year’s profit flows into shareholders’ funds, which is why it sits alongside your other financial statements.
What affects retained earnings
Profit, losses and dividends drive most changes in retained earnings. A few accounting adjustments can also move the balance without any cash changing hands.
Your retained earnings balance can change because of:
- a net profit, which increases the balance
- a net loss, which reduces it
- dividends paid to shareholders, which reduce it
- corrections of errors from earlier periods, which can restate the opening balance up or down
- a change in accounting policy, which can also restate the opening balance
- a bonus issue of shares, which moves part of the balance into share capital
Your company’s age and dividend policy shape the balance over the longer term. A new company has had fewer profitable years to build it up, and paying out more of each year’s profit slows its growth.
Negative retained earnings
Negative retained earnings mean your company’s accumulated losses are larger than its accumulated profits. Accountants call this an accumulated deficit.
A deficit usually builds up for one or more of these reasons:
- trading losses over several years
- a large one-off cost, such as writing off equipment or settling a legal claim
- paying out more in dividends than the company has earned
- heavy start-up costs in the early years
A company with an accumulated deficit has no profits available for distribution, so it can’t pay dividends. Lenders may also look more closely at a loan application.
A deficit is common for young companies that spend heavily while they win customers. What matters most is whether the balance is moving towards profit over time.
Retained earnings and profits available for distribution
In Ireland, your company can only pay dividends out of profits available for distribution. Retained earnings are the starting point, but the legal test is narrower.
Under Companies Act 2014 section 117, distributable profits are accumulated, realised profits less accumulated, realised losses. Profits already distributed or capitalised don’t count, and losses already written off in a capital reduction or reorganisation drop out.
Unrealised gains, such as a fair value gain on investment property taken to profit or loss, can boost retained earnings without adding to distributable profits. Check both figures with your accountant before your board declares a dividend.
When you pay a dividend, Irish-resident companies generally must withhold dividend withholding tax (DWT) at 25%. Some exceptions apply, so confirm how DWT affects each shareholder.
How to interpret retained earnings
Retained earnings show how much profit your company has kept, but you need context to read the number well. Compare it with your company’s age and recent spending.
A rising balance usually points to steady profits and reinvestment. It also gives you room to hire staff or ride out a quiet spell.
A low or falling balance can be normal after a big investment or in the first few years of trading. A decline over several years is a good prompt to review your profitability ratios.
The retention ratio shows the share of each year’s net profit you keep in the business. It works out as follows:
Retention ratio = 1 − dividend payout ratio
In the worked example above, the company pays €10,000 of its €30,000 net profit as dividends. Its payout ratio is about 33%, so its retention ratio is about 67%.
What are retained earnings used for?
Retained earnings let you invest in your company’s future without borrowing or bringing in outside investors. Many companies use them to cover costs and plan ahead.
Common uses for retained earnings include:
- covering wages, rent and supplies during slow months
- buying equipment, opening a new premises or hiring staff
- developing and testing new products or services
- buying a competitor or a complementary business
- building a cash reserve for unexpected disruptions or economic downturns
- paying down loans early to cut interest costs
Strong retained earnings also help when you do borrow. They lift shareholders’ funds, which lowers your gearing ratio and can help you qualify for better loan terms.
Close company surcharge on retained income
If your company is a close company, keeping some types of income can trigger an extra corporation tax charge. Check with your accountant whether your company is a close company.
According to Revenue’s surcharge guidance, close companies pay a 20% surcharge on undistributed after-tax estate and investment income. This includes rental income, interest and dividends.
Close service companies, such as those carrying on a profession, pay a 15% surcharge on one half of undistributed trading income. Distributing income within 18 months of the end of the accounting period reduces the surcharge.
How retained earnings affect the balance sheet
Retained earnings sit in the capital and reserves section of your balance sheet, alongside share capital. Together these make up shareholders’ funds, a measure of your company’s net worth.
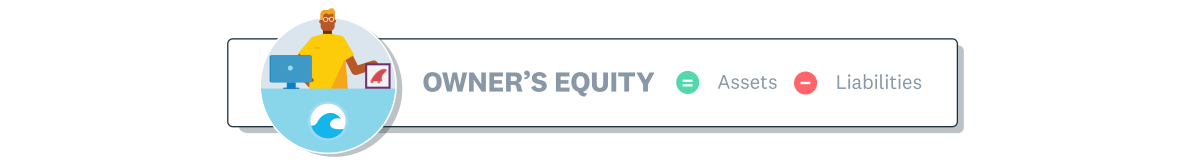
The balance sheet equation shows how the pieces fit:
Shareholders’ funds = assets − liabilities
When your company keeps a profit, shareholders’ funds rise by the same amount. That retained profit then shows up on the other side of the equation in two ways:
- as extra assets, such as cash, stock or equipment you buy with it
- as lower liabilities, such as loans or supplier bills you pay off with it
Say your company makes €10,000 in net profit after tax and pays no dividends. Retained earnings and shareholders’ funds both grow by €10,000, whether you hold the cash or spend it on equipment.
The other way to grow shareholders’ funds is to issue new shares to investors. For many small companies, retaining profit is the simpler route.
Retained earnings vs net profit and revenue
Retained earnings, net profit and revenue are linked, but each measures something different. Net profit and revenue cover one period, while retained earnings build up over the company’s life.
Retained earnings vs net profit
Net profit is your profit for one accounting period, such as a year. It’s what’s left after you subtract all costs and tax from your income for that period.
Retained earnings are cumulative. They add up every year’s net profit, less losses and dividends, since the company started.
Think of net profit as what you earned this year. Retained earnings are the running total of what you’ve kept.
Retained earnings vs revenue
Revenue, often called turnover in Ireland, is the total your business brings in from sales before any costs. It’s the top line on your profit and loss statement.
To get from revenue to retained earnings, you subtract all costs and tax to reach net profit. You then subtract dividends and add the result to last year’s balance.
Revenue can be high while retained earnings stay low. That happens when costs or dividends take up most of the income.
Retained earnings for sole traders and partnerships
Sole traders and partners don’t have retained earnings in the company sense, but the idea is similar. Profit you leave in the business builds up in your capital account instead.
You can take money out as drawings without declaring a dividend. Drawings reduce your capital balance, much as dividends reduce retained earnings for a limited company.
Here’s how drawings work:
- you move money from the business account to cover personal costs
- your capital balance drops by the amount you take
- owner’s equity on your balance sheet falls by the same amount
- your tax bill stays the same, because drawings aren’t a business expense
As a sole trader, you pay income tax at 20% or 40%, Universal Social Charge (USC) and Pay Related Social Insurance (PRSI) on your profits. You pay these whether you draw the profits out or leave them in the business.
Keep a clear record of your drawings so you always know what’s left in the business. Talk to your accountant about how this affects your tax planning.
Track and manage retained earnings with Xero
Knowing your retained earnings helps you decide when to reinvest and when to pay dividends. Accurate, up-to-date figures make those calls easier.
Xero gives you a real-time view of your position with automated bank feeds and balance sheet reports. You can run financial reports whenever you need them and share them with your accountant.
Start tracking your profits with confidence and get one month free.
FAQs on retained earnings
These answers cover common questions Irish business owners ask about retained earnings.
What are retained earnings in simple words?
Retained earnings are the profits your company has made over its life that it hasn’t paid out to shareholders. They stay in the business to fund growth or act as a cushion.
Where do retained earnings appear on the balance sheet?
They appear under capital and reserves, usually as the profit and loss reserve. You’ll find them next to called-up share capital and any other reserves.
Can a company have negative retained earnings?
Yes, a company has negative retained earnings when its accumulated losses exceed its accumulated profits. The company then needs to return to profit and clear the deficit before it can pay dividends again.
Is it good to have high retained earnings?
High retained earnings usually signal steady profits and financial strength. If the profit sits as cash rather than being put to work, though, you may want to review your plans for investment or dividends.
Are retained earnings an asset?
No, retained earnings belong in equity on the balance sheet. The profit they reflect is held in assets such as cash or equipment, or it has gone towards paying off liabilities.
Can you take money out of retained earnings?
Yes, a limited company can pay dividends, but only out of profits available for distribution and after withholding 25% DWT. Sole traders and partners take drawings instead.
What happens to retained earnings when dividends are paid?
Retained earnings fall by the gross amount of the dividend, and cash falls by the same total. Profit for the year stays the same, because a dividend is a distribution of profit rather than a business expense.
Are retained earnings taxed in Ireland?
Your company pays corporation tax on its profits before they become retained earnings, so keeping them doesn’t usually trigger more tax. Close companies may face a surcharge on certain undistributed income.
Related terms
Learn more about retained earnings
Handy resources
Advisor directory
You can search for experts in our advisor directory
Finance your business
Learn 14 ways to finance your business and help turn it into a profit machine
Financial reporting
Keep track of your performance with accounting reports
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.