Trial balance: what it is, how to prepare one, and why it matters
Learn what a trial balance is, its components, and how to prepare one with worked examples in Rupiah.
Written by Ebony-Storm Halladay — Freelance accounting copywriter, 10 years. Read Ebony's full bio
Published Wednesday 21 October 2026
Table of contents
Key takeaways
- Prepare trial balances regularly to catch mathematical errors and missing entries before they affect your financial statements, saving you time and preventing costly mistakes that compound over time.
- Verify that your total debit balances equal your total credit balances when creating a trial balance, as this confirms your double-entry bookkeeping is mathematically sound and your books are balanced.
- Use the three-step process of unadjusted, adjusted, and post-closing trial balances throughout your accounting cycle to ensure accuracy at each stage before finalising your financial reports.
- Recognise that matching debit and credit totals don't guarantee error-free books, as missing transactions or incorrect account classifications can still exist even when your trial balance appears balanced.
What is a trial balance?
A trial balance is a financial report that lists the closing balances of all accounts in your general ledger at a specific point in time. It's a simple check to confirm your debits equal your credits before you prepare financial statements.
Many businesses create a trial balance as the first step in closing their books at the end of an accounting period. If the totals match, your books are likely free of fundamental errors.
Trial balance example
Here's a simple trial balance for a café called Kopi Senja, prepared as at 31 March 2026. Each line shows the account number, account name and closing balance:
- 1-100 Cash at bank, debit Rp8.000.000
- 1-200 Accounts receivable, debit Rp2.000.000
- 2-100 Accounts payable, credit Rp1.500.000
- 3-100 Owner's capital, credit Rp5.000.000
- 4-100 Sales revenue, credit Rp6.000.000
- 5-100 Rent expense, debit Rp2.500.000
The debit balances add up to Rp12.500.000, and the credit balances also add up to Rp12.500.000. Because the two totals match, the café's books balance.
Components of a trial balance
A trial balance has four columns, and each row lists one account from your chart of accounts. The columns show:
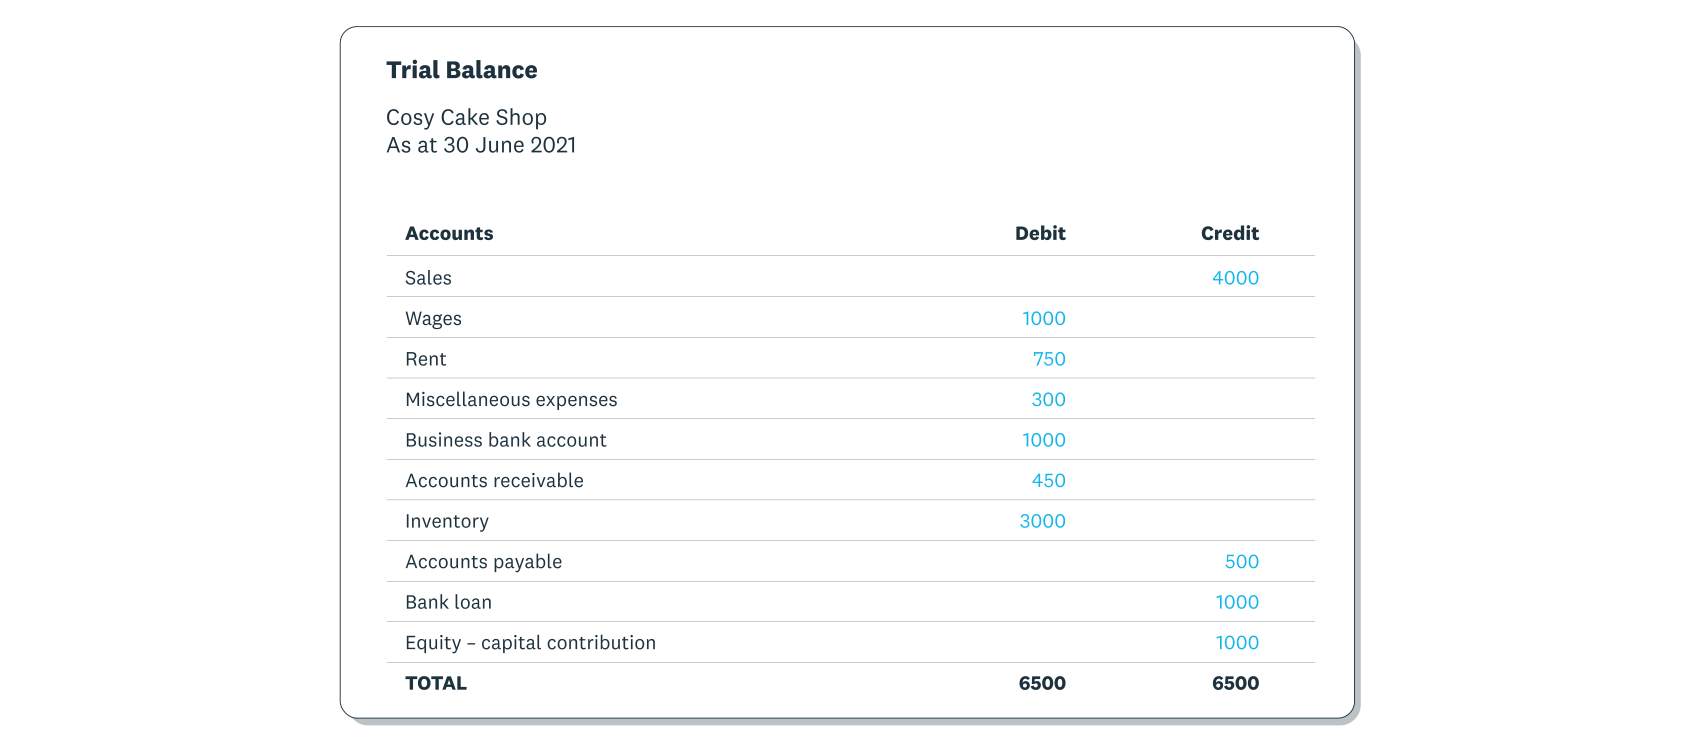
- the account number, a unique code that groups accounts by type
- the account name, such as cash at bank or rent expense
- the debit balance, used for assets like accounts receivable, plus expenses
- the credit balance, used for liabilities like accounts payable, plus capital and income
A heading at the top shows your business name, the report title and the date of the balances. A totals row at the bottom adds up the debit and credit columns, and these two figures should match.
You can omit accounts you haven't used during the period.
Why trial balances matter for small businesses
A trial balance matters because it catches errors before they affect your financial statements. For small businesses, this simple check can save time troubleshooting and help prevent costly mistakes. Learn more about small business accounting.
Here's why trial balances are important for your business:
- Error detection: identify mathematical mistakes and missing entries before they compound
- Financial confidence: verify your numbers are accurate before making business decisions
- Audit readiness: provide a clear record for accountants, auditors, or tax professionals
- Tax preparation: ensure your books are balanced before filing returns
- Time savings: catch issues early rather than tracing errors through months of transactions
You can prepare trial balances monthly or at least before year-end financial statements. Regular checks help you stay on top of your books without last-minute stress.
Types of trial balances
There are three types of trial balances, each used at a different stage of the accounting process: unadjusted, adjusted, and post-closing.
All three follow the same format but serve different purposes:
- Unadjusted trial balance: captures initial data from your general ledger and helps spot obvious errors or entries that need adjusting
- Adjusted trial balance: includes corrected entries and is the foundation for your financial statements
- Post-closing trial balance: confirms the ledger is ready for the next accounting period after temporary accounts are closed
Unadjusted trial balance
An unadjusted trial balance captures all initial data from your general ledger before you make any corrections. It records day-to-day transactions that can then be adjusted to balance the ledger.
Common adjustments include:
- Accruals: adding unpaid bills or earned but unreceived income
- Deferrals: recognising income only when it's earned
- Depreciation: spreading the cost of assets like vehicles over several years
These adjustments give you a clearer view of your business's financial position.
Adjusted trial balance
An adjusted trial balance summarises the final balances in all accounts after you make adjustments. You prepare it after the unadjusted trial balance but before creating your financial statements.
This report is the foundation for your balance sheet, income statement, and other financial reports.
Post-closing trial balance
A post-closing trial balance verifies that all debit and credit balances are equal after you've closed your temporary accounts. You prepare it after finalising your financial reports.
During the closing process, balances from temporary accounts (revenue, expenses, and dividends) move into retained earnings. The post-closing trial balance confirms your general ledger is ready for the next accounting period.
Trial balance vs. balance sheet
A trial balance and a balance sheet both show financial information, but they serve different purposes.
Trial balance:
- Purpose: checks that debits equal credits to catch mathematical errors
- Audience: internal use by bookkeepers and accountants
- Timing: prepared before financial statements
- Content: lists all account balances from the general ledger
Balance sheet:
- Purpose: summarises the business's overall financial position
- Audience: internal and external stakeholders (investors, lenders)
- Timing: prepared after the trial balance
- Content: shows assets, liabilities, and owner's equity
The trial balance is the first step to creating a balance sheet.
How to prepare a trial balance
Preparing a trial balance helps you verify your books are accurate before creating financial statements. Here's how to create one:
- Gather your general ledger balances: collect the closing balances from all accounts in your general ledger
- List all accounts: record each account name in the left column of your trial balance
- Separate debits and credits: enter debit balances in the debit column and credit balances in the credit column
- Total each column: add up all debits and all credits separately
- Verify the totals match: check that debits equal credits to confirm your books are balanced
If the totals differ, check the journal entries behind your ledger for errors. As a quick check, if the difference is divisible by 9, you may have a transposition error (reversed digits) or a slide error (misplaced digits or zeros).
These steps produce an unadjusted trial balance. From there, you'll prepare your adjusted trial balance, then your post-closing trial balance once your financial reports are finalised.
Accounting software, including Xero, can automate this process. You can generate trial balances instantly without manual calculations.
2 ways to prepare a trial balance: total method and balance method
You can prepare a trial balance using the total method or the balance method. Both start from the same ledger accounts, and both should give matching debit and credit totals.
The total method lists each account's total debits and total credits for the period. The balance method lists only each account's net closing balance, on either the debit or credit side. The balance method is the more common choice because it's shorter and flows straight into your financial statements.
Say your business has just finished its first month of trading. You invest Rp10.000.000, make Rp6.000.000 in credit sales and Rp4.000.000 in cash sales, then collect Rp2.500.000 from customers. You also buy Rp3.000.000 of supplies on credit, pay a supplier Rp1.000.000 and pay Rp2.000.000 in rent.
Using the total method, your trial balance lists each account's total debits and credits:
- 1-100 Cash, debits Rp16.500.000 and credits Rp3.000.000
- 1-200 Accounts receivable, debits Rp6.000.000 and credits Rp2.500.000
- 2-100 Accounts payable, debits Rp1.000.000 and credits Rp3.000.000
- 3-100 Owner's capital, credits Rp10.000.000
- 4-100 Sales revenue, credits Rp10.000.000
- 5-100 Supplies expense, debits Rp3.000.000
- 5-200 Rent expense, debits Rp2.000.000
Total debits and total credits both come to Rp28.500.000, so this version balances.
Using the balance method, you net each account down to one closing balance:
- 1-100 Cash, debit Rp13.500.000
- 1-200 Accounts receivable, debit Rp3.500.000
- 2-100 Accounts payable, credit Rp2.000.000
- 3-100 Owner's capital, credit Rp10.000.000
- 4-100 Sales revenue, credit Rp10.000.000
- 5-100 Supplies expense, debit Rp3.000.000
- 5-200 Rent expense, debit Rp2.000.000
Total debits and total credits both come to Rp22.000.000. The totals are smaller because each account's debits and credits are netted off, and the report still balances.
Common trial balance errors
Common trial balance errors include data entry mistakes, missing transactions, and incorrectly classified accounts. These simple mistakes can lead to inaccurate financial statements and poor business decisions.
Watch out for these errors:
- Transcription errors: mistyping figures like Rp500.000 as Rp5.000.000. One common type is a slide error, which happens when digits or zeros are misplaced, such as recording Rp1.500.000 as Rp15.000
- Omission errors: missing transactions left out of the accounts entirely
- Misclassification errors: recording transactions under the wrong account headings. For example, if the trial balance's difference is divisible by 2, it could mean a debit-balanced account was incorrectly entered as a credit, or vice versa
How to correct trial balance errors
Here's how to correct trial balance errors:
- Recheck your numbers: review your trial balance thoroughly, take a break to return with fresh eyes, and ask someone else to check for typos
- Verify your ledger entries: confirm your ledger figures are correct before transferring them to your trial balance
- Use accounting software: tools like Xero reduce mistyped entries and speed up calculations, giving you more time to verify accuracy
The role of trial balances in financial statements
Trial balances serve as the foundation for financial statements like balance sheets and income statements. They're also an important document for auditors.
You or your bookkeeper can use the trial balance to verify that debit and credit totals match. If they don't, you may need to investigate a missing transaction or copying error. Once you correct any mistakes, you can use the adjusted trial balance to prepare your financial reports.
Matching totals don't guarantee error-free books. Missing transactions or incorrect account classifications can still exist even when debits equal credits.
Streamline your trial balances with Xero
Trial balances help keep your financial statements accurate and give you confidence that your numbers reflect your business's actual financial position.
Xero's accounting software makes trial balances simple:
- Automatic generation: create trial balances instantly from your ledger entries
- Error reduction: reduce manual calculations and transcription mistakes
- Real-time visibility: access your trial balance anytime to check your books
- Quick reporting: move from trial balance to financial statements in a few clicks
Ready to simplify your accounting? Get one month free when you sign up for Xero.
FAQs on trial balances
Here are answers to common questions about trial balances for small businesses.
What are the three rules of trial balances?
- Total debits must equal total credits: This confirms your double-entry bookkeeping is balanced
- Use the correct chart of accounts: Each transaction must go to the right account category
- Enter data accurately: Careful data entry prevents transcription and omission errors
Can accounting software prepare trial balances automatically?
Yes. Modern accounting software like Xero automatically generates trial balances from your ledger entries. This eliminates manual calculations and reduces the risk of transcription errors.
How long does it take to prepare a trial balance?
Accounting software generates trial balances instantly. Preparing one manually takes longer, depending on your transaction volume and number of accounts.
Do I need a trial balance if I use accounting software?
Yes. While software automates the process, understanding trial balances helps you verify your books are accurate and catch any data entry errors before preparing financial statements.
How often should I prepare a trial balance?
You can run trial balances monthly to catch errors early. At least prepare one before year-end financial statements or whenever you need to verify your books are balanced.
What is a trial balance used for in month-end and year-end closing?
At month-end, you complete your bank reconciliation, post adjustments and run an adjusted trial balance to produce management reports. At year-end, the adjusted version supports your financial statements and annual tax return, then a post-closing trial balance confirms temporary accounts have moved into retained earnings.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.