General ledger (GL)
A general ledger (GL), or buku besar, is the master record of your business’s transactions, sorted by account.
Published Wednesday 30 September 2026
Table of contents
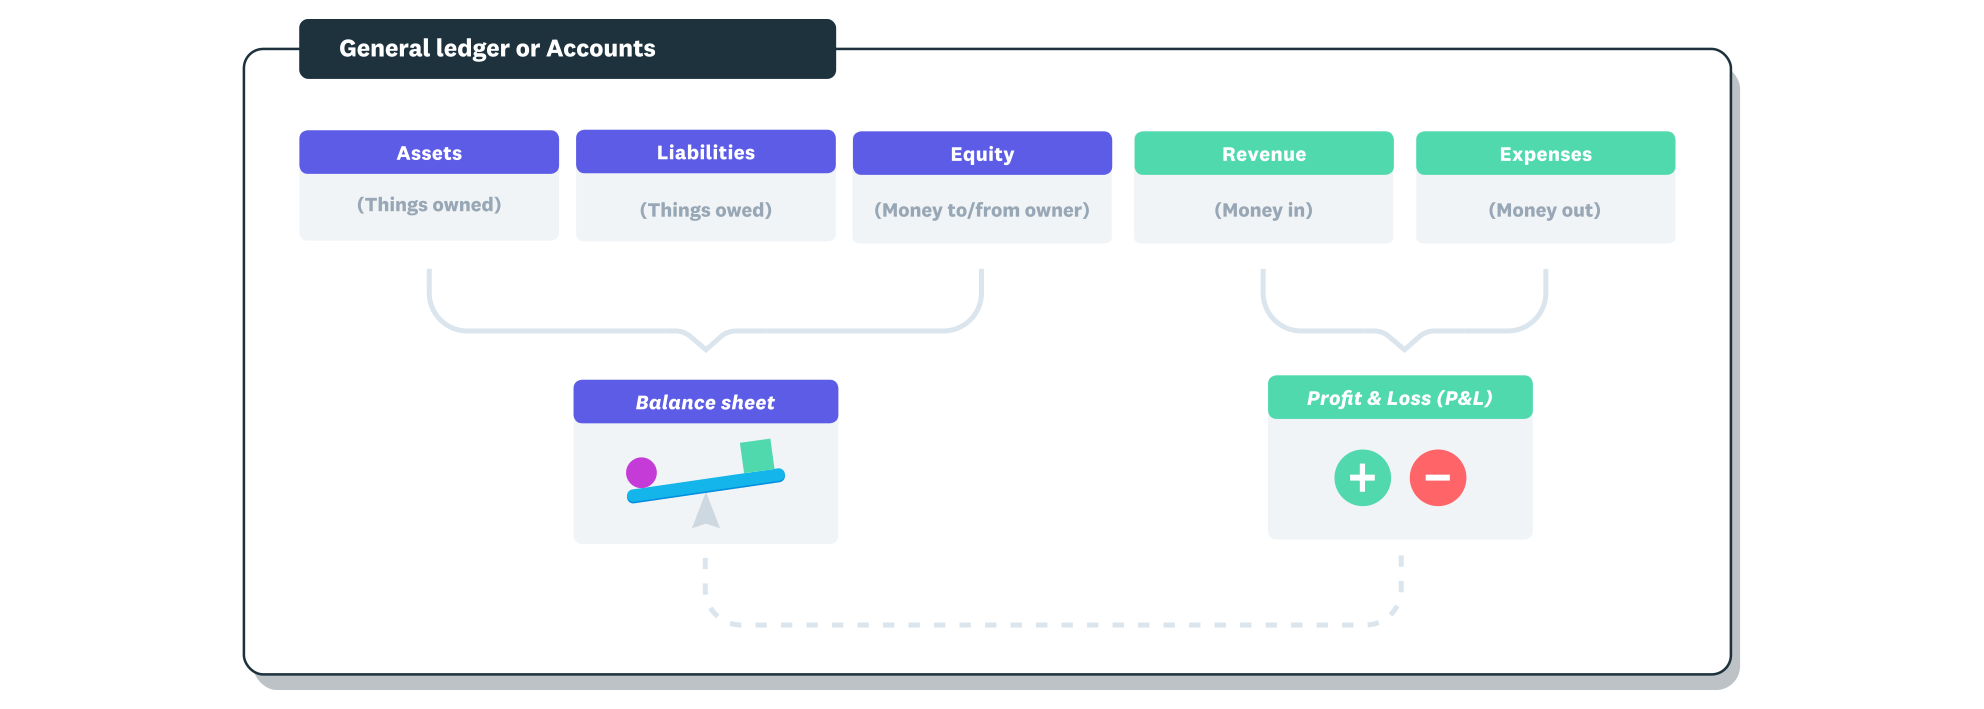
Transactions are entered into the correct account in order to produce the financial reports.
Key takeaways
- A general ledger (GL), or buku besar in Indonesian, is the master record of every financial transaction in your business, sorted by account
- Double-entry bookkeeping keeps the ledger balanced, because each transaction adds a debit to one account and an equal credit to another
- Indonesian tax law sets how you keep your books, including Rupiah as the default currency and a 10-year retention period
- Accounting software posts entries and builds reports from your ledger automatically, so you spend less time on manual data entry
What is a general ledger?
A general ledger (GL) is the master record of all your business’s financial transactions, sorted by account. In Indonesian, it’s known as buku besar.
Think of it as a filing cabinet for your finances, with one drawer for each account. Every sale, purchase, wage payment and expense goes into a drawer, and the ledger shows each drawer’s running balance.
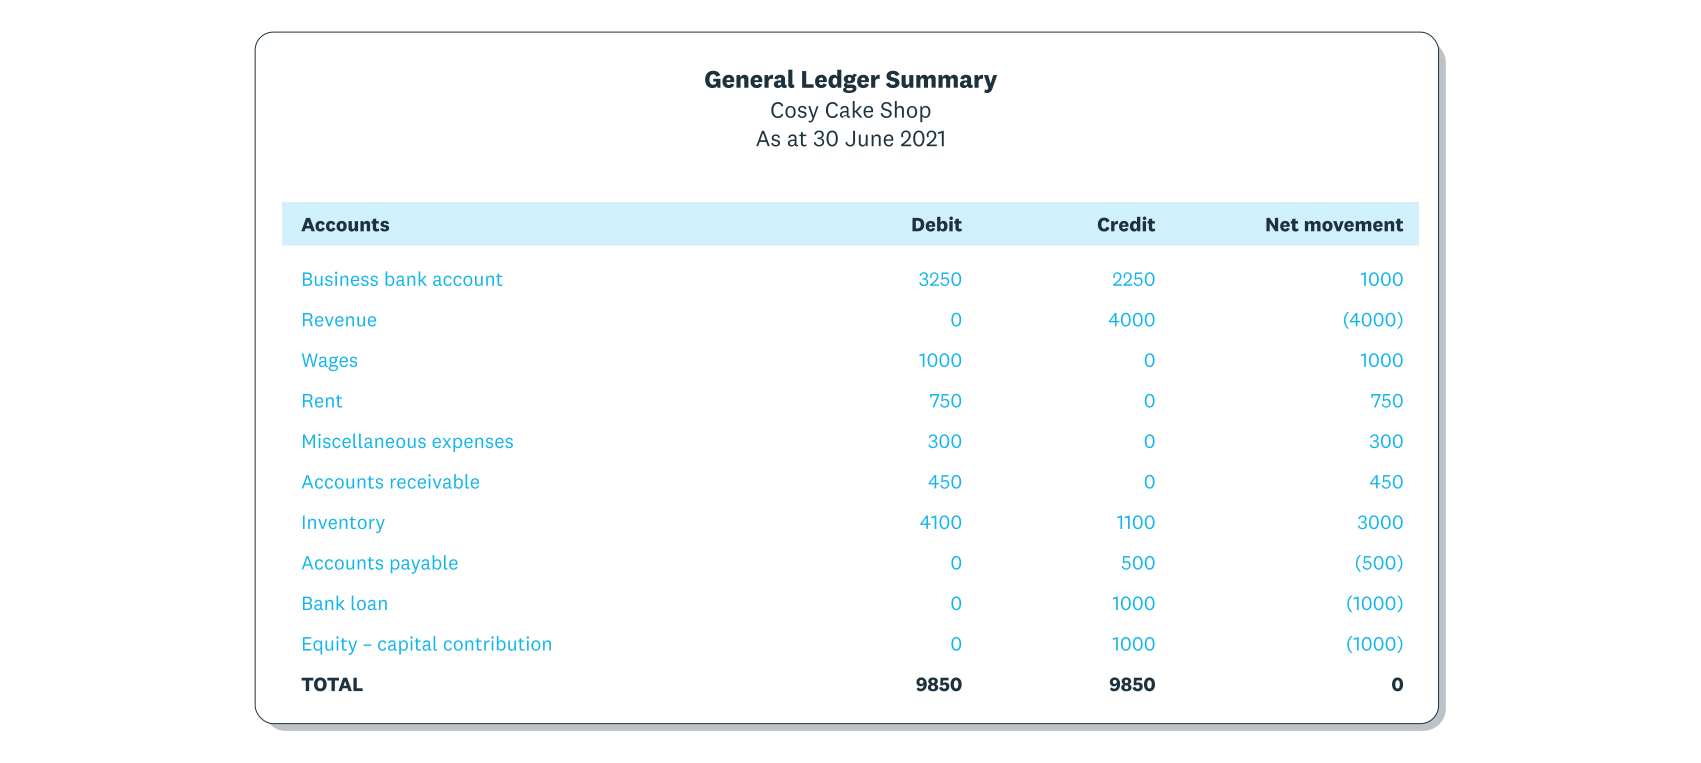
The general ledger summarises the credit and debit transactions for each account.
Your chart of accounts sets out those drawers. Each account has a name and a code, so every transaction lands in the right place and your financial reports draw on accurate totals.
How does a general ledger work?
A transaction moves through your GL in a set order before it shows up in your financial statements. Here’s the flow.
- A transaction happens, such as a sale or a wage payment
- You record it as a journal entry, with a debit to one account and an equal credit to another
- You post the entry to the matching accounts in the ledger
- Each account’s balance updates to show the new total
- At the end of the period, you prepare a trial balance from the ledger totals to check that debits equal credits
- You produce financial statements, such as the balance sheet and the profit and loss statement, from the checked balances
This cycle repeats for every transaction. Over time, your GL builds a complete financial history of your business.
What gets recorded in a general ledger
Every transaction in your business falls into one of five account categories. Together, they show what your business owns, owes, earns and spends. Your GL records:
- assets, such as cash in the bank, money customers owe you, equipment and inventory
- liabilities, such as loans, unpaid supplier bills, credit card balances and wages you owe
- equity, such as the capital you’ve put in and the profits you’ve kept in the business
- revenue, such as income from sales and services, plus interest earned
- expenses, such as rent, wages, utilities, office supplies and marketing
Types of general ledger accounts
Beyond the five categories, GL accounts also differ in how they behave at the end of an accounting period and how much detail they hold. These differences shape how you close your books and organise your codes.
Permanent vs temporary accounts
Permanent accounts carry their balances forward from one period to the next. Assets, liabilities and equity are permanent, so your cash balance on 31 December becomes your opening balance on 1 January.
Temporary accounts, meaning revenue and expenses, reset to zero at the end of each period. Closing entries move their balances into retained earnings, or into the owner’s capital account for a sole proprietorship.
Subledgers
A subledger holds the detail behind one GL account. Your accounts receivable subledger, for example, lists every customer invoice, while the GL shows only the total owed to you.
That GL total sits in a control account, a summary account that rolls up the subledger’s transactions. Control accounts are most common for accounts receivable and accounts payable, because both carry high transaction volumes.
GL codes and chart of accounts
Most businesses give each GL account a numeric code, grouped by category. For example, asset accounts might start at 1000, liabilities at 2000, equity at 3000, revenue at 4000 and expenses at 5000.
These codes make accounts faster to find and sort. Your chart of accounts is the full list of codes and account names your business uses.
What is double-entry bookkeeping?
Double-entry bookkeeping is the system behind every GL. Each transaction is recorded in at least two accounts, with a debit in one and a credit in the other for the same amount.
This keeps the accounting equation in balance: assets = liabilities + equity. If you pay Rp10,000,000 in rent, cash falls by Rp10,000,000 and rent expense rises by the same amount.
The system also gives you a built-in error check, because matching debits and credits show each entry is complete. You can read more on how debits and credits pair up across everyday transactions.
General ledger example
Seeing entries in action makes the ledger easier to follow. Here are two common transactions for a small business in Indonesia, recorded in Rupiah.
Buying office supplies with cash
Your business buys Rp2,000,000 of office supplies and pays in cash. To record it in the GL, you:
- debit office supplies (expense) by Rp2,000,000
- credit cash (asset) by Rp2,000,000
The expense account rises by Rp2,000,000 because you’ve spent money. Cash falls by the same amount because it’s left the business, so the two sides balance.
Invoicing a customer
You send a customer an invoice for Rp5,000,000 of services. To record it in the GL, you:
- debit accounts receivable (asset) by Rp5,000,000
- credit sales revenue (revenue) by Rp5,000,000
Accounts receivable rises because the customer now owes you Rp5,000,000, and revenue rises because you’ve earned it. When the customer pays, you record a second entry that debits cash and credits accounts receivable.
General ledger vs journal, trial balance and balance sheet
Several accounting records sound similar to a GL but do different jobs. Here’s how each one compares.
General ledger vs general journal
The general journal is where you first record transactions in date order, like a diary of financial events. The GL then sorts those same entries by account, so you can see a running balance for each one.
General ledger vs trial balance
A trial balance is a report drawn from the GL at the end of a period. It lists every account balance and checks that total debits equal total credits, while the GL keeps the full transaction detail.
General ledger vs balance sheet
The balance sheet is a financial statement built from GL data. It gives a snapshot of your assets, liabilities and equity on a set date, and it’s one of several reports the ledger supports.
How to set up a general ledger
To set up a general ledger, build an account structure that fits your reporting standard, then start recording. In Indonesia, that usually means Standar Akuntansi Keuangan Entitas Privat (SAK EP) or Standar Akuntansi Keuangan Entitas Mikro, Kecil, dan Menengah (SAK EMKM).
- Choose your account structure with your accountant. Confirm whether SAK EP or SAK EMKM fits your business.
- Set up your chart of accounts. Give each account a name and a numeric code, grouped by category.
- Enter your opening balances. Record what each account holds on your start date, using your last balance sheet or bank statements.
- Log each transaction by date, description, account, debit, credit and running balance. A spreadsheet suits very small businesses, but manual formulas add error risk.
- Post and reconcile your entries. Check each account against your bank statements and supplier bills, and fix any gaps.
- Run a trial balance. Confirm total debits equal total credits before you produce financial statements.
General ledger rules for Indonesian businesses
Indonesian tax law sets clear rules for how you keep your books, and your ledger is where you meet most of them. Here’s what applies to small businesses.
Pasal 28 of the Undang-Undang Ketentuan Umum dan Tata Cara Perpajakan (UU KUP) sets the core duty. Individuals and companies running a business in Indonesia must keep books (pembukuan). Those books need enough detail to calculate taxable income.
Individuals with gross turnover under Rp4.8 billion a year can instead keep simpler records (pencatatan), as set out in Peraturan Menteri Keuangan (PMK) 81/2024. They then work out net income using the deemed-profit norm (Norma Penghitungan Penghasilan Neto, or NPPN). Companies (badan) always keep full books, whatever their turnover.
You need to keep your books in Indonesia using Latin letters, Arabic numerals, Rupiah and Bahasa Indonesia. Books in English or US dollars need written permission from the Minister of Finance, which only certain taxpayer categories can get.
You also need to store your books and supporting documents for 10 years in Indonesia. This applies whether you keep full books or simpler records.
For financial statements, Ikatan Akuntan Indonesia (IAI) sets the accounting standards. Private businesses without public accountability now use SAK EP, which replaced Standar Akuntansi Keuangan Entitas Tanpa Akuntabilitas Publik (SAK ETAP) from 1 January 2025. SAK EMKM is a simpler IAI standard intended for micro, small and medium entities.
Why does your business need a general ledger?
A well-kept GL gives you the financial clarity to run your business with confidence. It helps you:
- produce accurate financial statements for your accountant and lenders
- prepare tax returns in Coretax DJP, the Direktorat Jenderal Pajak (DJP) system in effect since 1 January 2025
- meet your bookkeeping duties under Indonesian tax law and accounting standards
- stay ready for a tax audit, with records organised by account
- catch errors and unusual activity early through double entry and regular reconciliation
- track your cash flow and plan spending from real numbers
How to reconcile a general ledger
Reconciling your GL means checking your records against outside documents, such as bank statements, to confirm they match. Aim to reconcile monthly, starting with bank reconciliation, which matches your cash accounts to your bank statements.
- Gather the bank and credit card statements for the period
- Compare each GL account balance with its matching external record
- Find any differences, such as missing or duplicate transactions
- Make adjusting entries to correct errors or add missed transactions
- Confirm your balances are accurate and your trial balance balances
Accounting software with built-in reconciliation tools suggests matches between bank transactions and ledger entries. That means less time checking line by line.
General ledger and accounting software
Keeping a ledger by hand, in spreadsheets or on paper, takes time and leaves room for mistakes. Accounting software takes over the posting, so you spend more time running your business.
With Xero accounting software, each transaction you record posts to the right GL accounts and balances update straight away. You can run financial reports, like your trial balance and balance sheet, whenever you need them.
You can check your accounts from any device and share reports with your accountant or bookkeeper at any time. That means you can see where your business stands during the month, well before month-end.
Keep your general ledger up to date with Xero
An accurate general ledger underpins your reports and your tax returns, and keeping it current means fewer surprises at tax time. Xero posts entries as you invoice and reconcile, so your books stay ready for your accountant.
If you’d like to try Xero before you buy, you can get one month free and set up your ledger with every feature included.
FAQs on general ledgers
Here are quick answers to common questions about general ledgers.
What is a GL account?
A GL account is a single account in your ledger, such as cash at bank or rent expense, with its own code and running balance. Your chart of accounts lists every GL account your business uses.
Is a general ledger the same as an accounting ledger?
Mostly, yes, though accounting ledger is a broader term that can also mean a subledger. The general ledger is the master ledger that holds the summary balance of every account.
Which accounts need reconciling most often?
Bank and credit card accounts usually need the most frequent checks, because they carry the most day-to-day activity. After that, check that your receivables and payables control accounts match their subledger totals.
How long must Indonesian businesses keep ledger records?
Keep your books and supporting records for 10 years at your place of business or residence in Indonesia. If your ledger lives in accounting software, make sure you can access or export it for that full period.
Can you manage a general ledger without software?
Yes, a spreadsheet works if you add a trial balance tab that totals debits and credits each month. Locking formula cells and reconciling monthly helps keep it accurate as your transactions grow.
Does a business using pencatatan still need a general ledger?
Pencatatan meets the tax duty for eligible individuals, but a GL gives you a fuller view of your profit and what you owe. It also makes full bookkeeping easier to start if your turnover passes Rp4.8 billion.
Related terms
Learn more about general ledgers
Handy resources
Advisor directory
You can search for experts in our advisor directory
Xero Small Business Guides
Discover resources to help you do better business
Online accounting with Xero
Automate your accounting in the cloud
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.