Quick ratio vs current ratio
Learn how the quick ratio and current ratio differ, how to calculate each, and what healthy results look like.
February 2024 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- The current ratio compares all your current assets with your current liabilities, giving a broad view of the next 12 months
- The quick ratio, or acid test ratio, leaves out inventory and prepaid expenses to show what your most liquid assets can cover
- Analysts often treat a current ratio between 1.5 and 3.0 as healthy, while a quick ratio between 1.0 and 1.5 is a common sweet spot
- Comparing the quick ratio vs current ratio shows how much your liquidity relies on selling stock, so tracking both helps you spot cash risks early
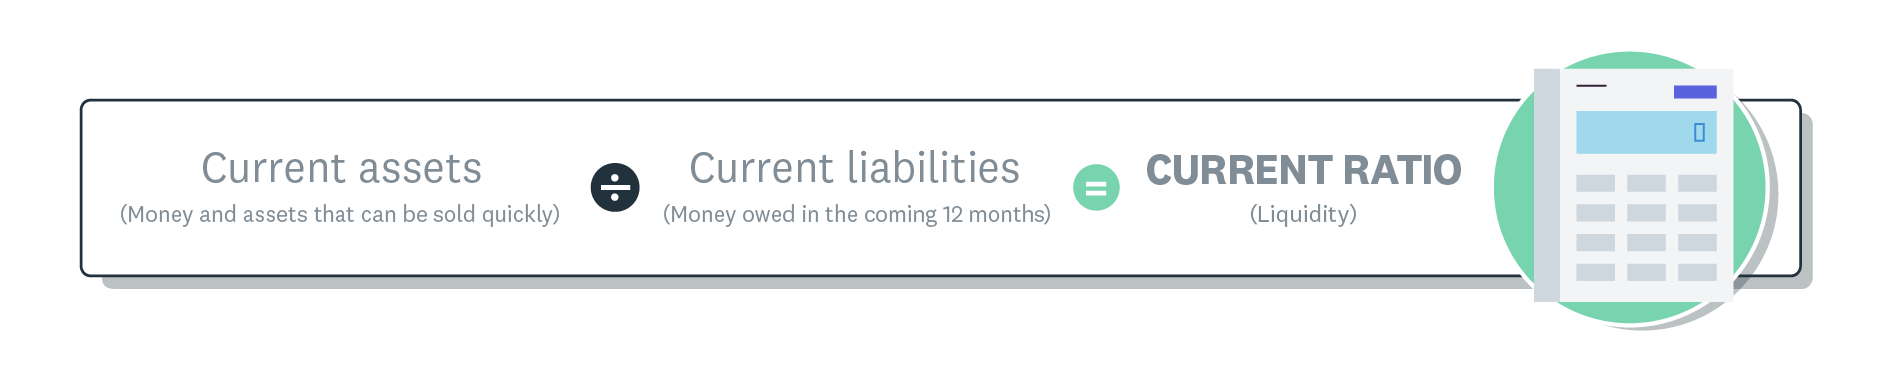
Current ratio liquidity formula.
What is the current ratio?
The current ratio shows how easily your business can cover its costs over the next 12 months. It's also called the working capital ratio. It compares what you can turn into cash within a year against what you owe in that time.
To work it out, divide your current assets by your current liabilities:
Current ratio = current assets / current liabilities
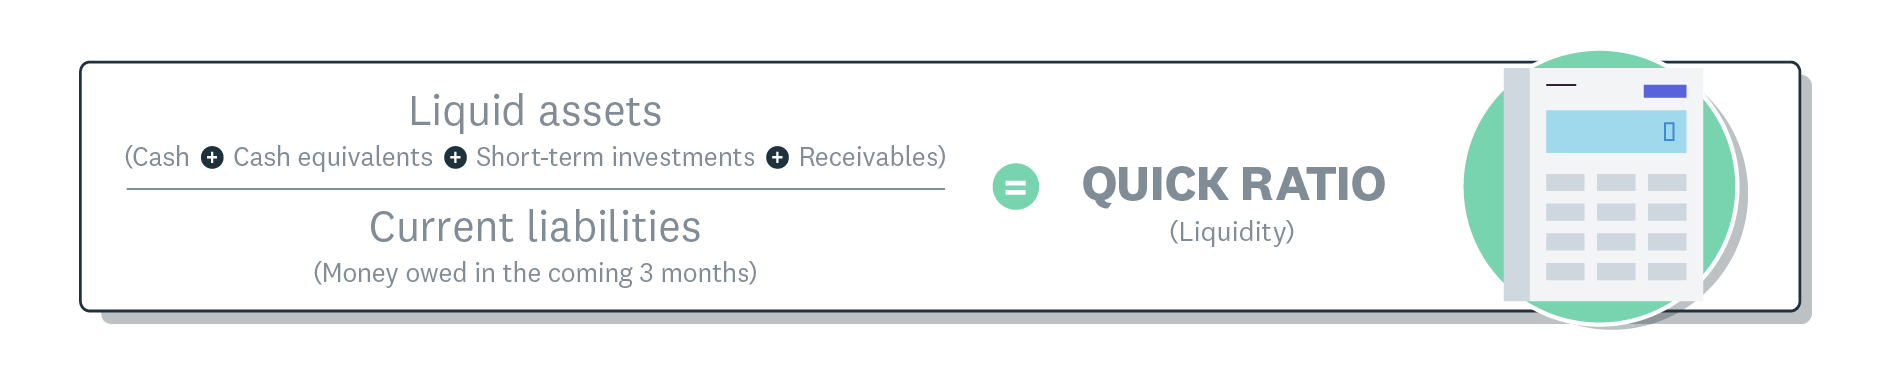
Quick ratio formula Version 1.
Current assets include cash, accounts receivable, inventory and prepaid expenses. Current liabilities include accounts payable, short-term loans, tax owed and any other debts due within 12 months.
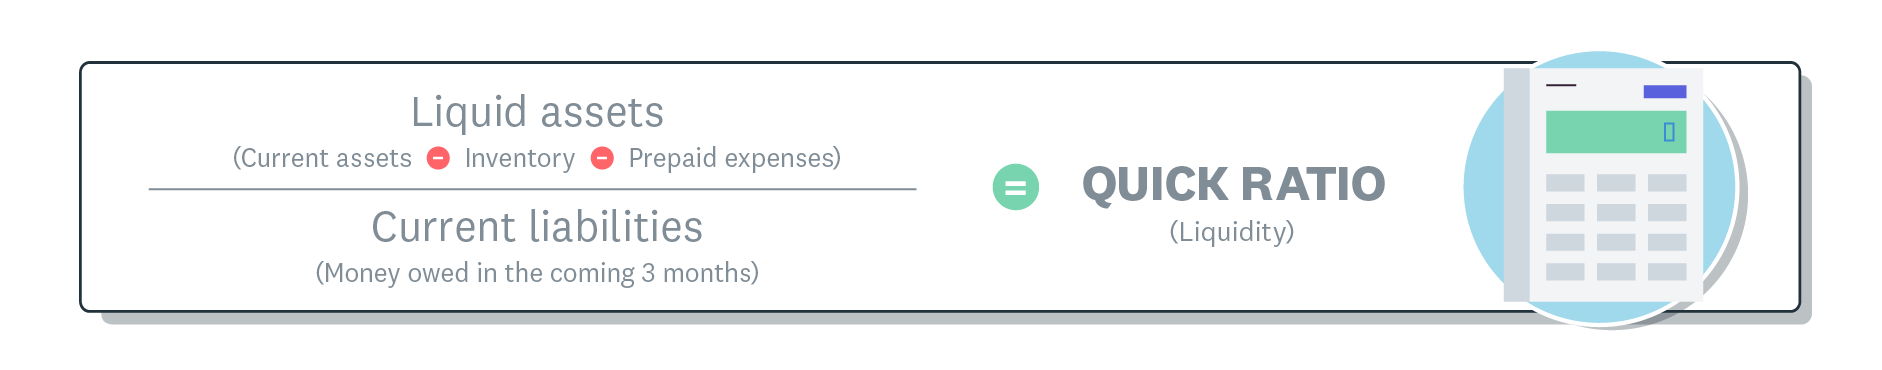
Quick ratio formula Version 2.
Say your business has €150,000 in current assets and €100,000 in current liabilities:
Current ratio = €150,000 / €100,000 = 1.5
That means you have €1.50 in current assets for every €1.00 you owe. It gives you a buffer if several bills land at once.
What is the quick ratio?
The quick ratio, also called the acid test ratio, measures whether your most liquid assets can cover your short-term debts. It leaves out inventory and prepaid expenses, because you can't always turn them into cash quickly.
You can calculate the quick ratio in two ways. Version 1 adds up your most liquid assets:
Quick ratio = (cash + marketable securities + accounts receivable) / current liabilities
Version 2 starts with all current assets and subtracts the ones that take longer to turn into cash:
Quick ratio = (current assets − inventory − prepaid expenses) / current liabilities
Both versions reach the same answer when your current assets are made up of these items. Version 2 is often faster if you already have a total for current assets.
Why inventory is excluded
Inventory is left out because turning stock into cash takes time. AccountingTools points out that stock can take months to sell, and you may have to cut the price to shift it.
Selling on credit adds another delay, because the stock becomes a receivable and you wait again for the customer to pay. The exception is a business with very fast stock turnover, such as a grocery shop, where inventory turns into cash almost as quickly as receivables.
Handy resources
Advisor directory
You can search for experts in our advisor directory.
Balance sheet template
See where and how assets and liabilities are reported.
Push-button liquidity reporting
Check your current ratio whenever you like with Xero’s accounting dashboard.
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.
Quick ratio example
Take the same business from the current ratio example. Its €150,000 in current assets breaks down like this:
- €30,000 in cash
- €50,000 in accounts receivable
- €55,000 in inventory
- €15,000 in prepaid expenses
With €100,000 in current liabilities, version 2 of the formula gives:
Quick ratio = (€150,000 − €55,000 − €15,000) / €100,000 = 0.8
The current ratio of 1.5 looked healthy, but the quick ratio of 0.8 shows the business needs stock sales to cover its short-term debts. That matters if several bills fall due before customers buy.
How to calculate the quick ratio and current ratio
You can work out both ratios from one balance sheet in a few minutes. Follow these steps:
- Run a balance sheet for the date you want to check
- Add up your current assets, meaning everything you expect to turn into cash within 12 months
- Add up your current liabilities, meaning every debt due within 12 months
- Divide current assets by current liabilities to get your current ratio
- Subtract inventory and prepaid expenses from current assets, then divide the result by current liabilities to get your quick ratio
- Compare the two results with each other and with your figures from previous months
Key differences between the quick ratio and current ratio
Both ratios test whether you can pay what you owe soon, but they count different assets. Here's how they compare:
- The current ratio covers the next 12 months, while the quick ratio shows what you could pay almost straight away
- The current ratio counts every current asset, while the quick ratio counts only cash, marketable securities and accounts receivable
- The current ratio gives a broader reading, while the quick ratio is more conservative because it leaves out slower assets
- The current ratio suits wider financial planning, while the quick ratio is the one lenders often check to judge your ability to pay now
Accounts receivable, a key input in the quick ratio, depends on how quickly customers pay. If customers regularly pay late, the quick ratio gives you a more honest picture of whether receivables can cover near-term bills.
What the gap between the 2 ratios tells you
The gap between your current ratio and quick ratio shows how much of your liquidity is tied up in stock and prepaid expenses. A small gap means most of your current assets are already cash or close to it.
A wide gap means you'd need to sell stock to pay your bills on time. Say your current ratio is 2.0 but your quick ratio is 0.7: you look comfortable on paper, yet you rely heavily on inventory to stay liquid.
The earlier example, with a current ratio of 1.5 and a quick ratio of 0.8, tells the same story. If that gap widens month after month, check whether stock is building up faster than you're selling it.
How to interpret your results
Your ratios make most sense when you compare them with benchmarks and with your own past results. According to the Corporate Finance Institute (CFI), analysts often consider a current ratio of 1.5–3.0 healthy, depending on the business.
CFI adds that a quick ratio above 1.0 usually means you can meet your short-term obligations, with 1.0–1.5 a common sweet spot. Below 1.0 on either ratio, your current liabilities are larger than the assets counted, so you may need extra funding or sales to keep up.
A very high current ratio can also mean there's cash sitting idle that you could reinvest to grow your business. Look for a level that covers your bills and still keeps your money working.
What counts as healthy liquidity ratios also varies by industry. Some retailers can run comfortably on lower quick ratios because steady sales bring cash in predictably.
The most useful comparison is your own trend over time, set against businesses similar to yours.
When to use the quick ratio vs the current ratio
The right ratio depends on the question you're asking about your finances. Here's when each one helps most:
- Use the current ratio for a broad view of your short-term financial health over the next 12 months
- Use the quick ratio to check whether you can pay bills without waiting on stock sales
- Use the quick ratio if you carry seasonal stock, because it stays steadier as inventory rises and falls
- Use either ratio if you run a service business with little stock, because both will show similar results
- Use both ratios together when you apply for a loan, prepare financial reports or review your cash flow strategy
Tracking these ratios regularly helps you spot shifts in your liquidity before they become urgent, especially when costs are rising.
Limitations of liquidity ratios
Liquidity ratios give you a fast read on short-term health, and they're most useful with some context. Keep these points in mind when you read yours:
- Compare several months, because each ratio is a snapshot of a single date
- Measure at the same point in your seasonal cycle, because stock and sales can swing between busy and quiet months
- Treat year-end figures with care, because one-off timing, such as paying suppliers just before the date, can flatter the result
- Check long-term solvency separately, because both ratios look only at the next 12 months
How to improve your liquidity ratios
If your ratios are lower than you'd like, a few practical changes can strengthen them. Here are five ways to improve your liquidity:
- Collect receivables sooner by tightening your payment terms and offering early payment discounts
- Ask suppliers for longer credit periods to ease pressure on current liabilities
- Manage your inventory levels so cash isn't tied up in slow-moving stock
- Build a cash reserve to cover unexpected costs or slow-paying customers
- Review your ratios alongside your other financial statements so you catch trends early
Even small changes to how you collect and spend cash can move both ratios in the right direction.
Track your liquidity ratios with Xero
Accurate liquidity ratios depend on up-to-date figures. Xero bank feeds bring your transactions into Xero's cloud accounting software automatically, so your reports reflect what's in your account today.
With a real-time balance sheet, you can check both ratios in minutes whenever a lender asks or a big bill is coming up. See how easy it is when you get one month free.
FAQs on quick ratio vs current ratio
These answers cover common questions about the quick ratio vs current ratio that go beyond the basics.
What does a current ratio of 1.5 mean?
A current ratio of 1.5 means your current assets could fall in value by a third and still cover your current liabilities. That buffer helps if you have to sell some stock at a discount or a customer pays late.
Can a business with a high quick ratio still run short of cash?
Yes. The quick ratio counts receivables at face value, so late payers or bills due before invoices are settled can still leave you with a cash gap.
Is there a stricter test than the quick ratio?
Yes, the cash ratio divides only cash and marketable securities by current liabilities. It leaves out receivables too, so it shows what you could pay using money you already hold.
Why are prepaid expenses left out of the quick ratio?
Prepaid expenses, such as insurance or rent paid in advance, can't be turned back into cash. They lower your future costs rather than giving you money to pay today's bills.
Is working capital the same as the current ratio?
They use the same figures in different ways: working capital is current assets minus current liabilities in euro, while the current ratio divides one by the other. The example business has €50,000 of working capital and a current ratio of 1.5.