Liquidity
Learn what liquidity means, how to measure it with the current, quick and cash ratios, and how to improve it.
Published Wednesday 30 September 2026
Table of contents
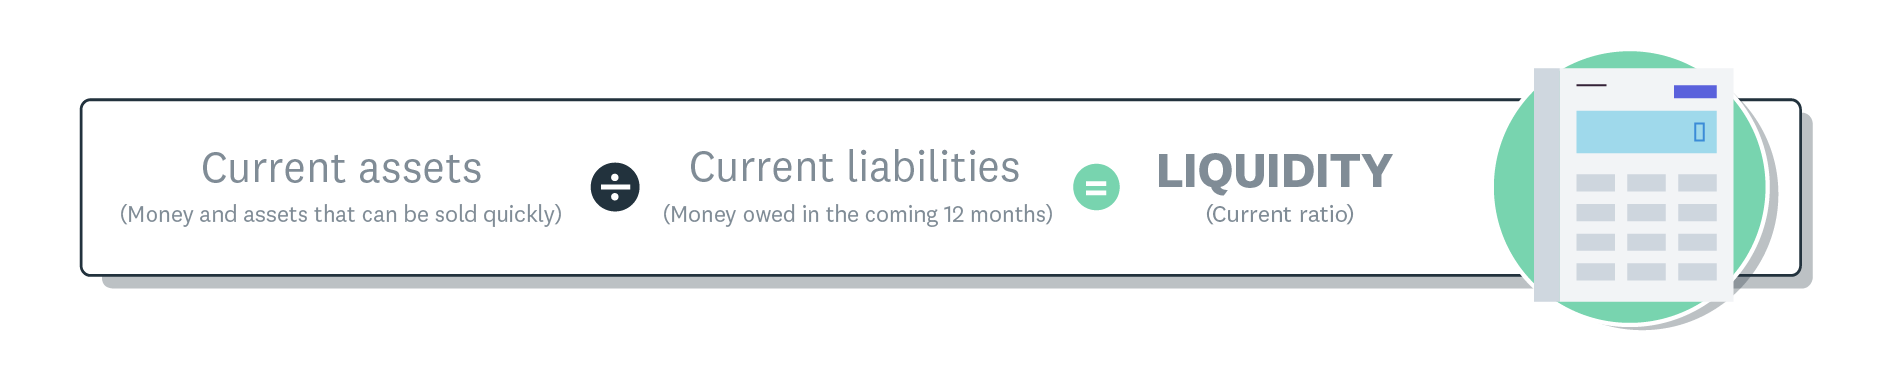
Current ratio liquidity formula.
Key takeaways
- Liquidity is your ability to pay bills and loan repayments due in the next 12 months using cash or assets you can quickly convert
- The current, quick and cash ratios all divide liquid assets by total current liabilities, and the cash ratio is the strictest test
- A current ratio above 1.0 means your current assets exceed your current liabilities, and 2:1 is a rule of thumb that varies by industry
- A profitable business can still run short of cash, so check liquidity monthly and act early on slow payments and excess stock
What is liquidity?
Liquidity is how easily your business can pay its upcoming bills and loan repayments with cash or assets it can quickly convert to cash. The Corporate Finance Institute (CFI) ties it to meeting your short-term financial obligations.
You measure liquidity by comparing your current assets with your current liabilities, usually as a ratio. Under the accounting standard IAS 1, current liabilities are generally amounts due for settlement within 12 months of the reporting date.
Current assets include cash, money customers owe you, stock and prepayments, plus anything else you expect to turn into cash within that period. Picture a builder with €40,000 in unpaid invoices and a €30,000 supplier bill due this month. If customers pay on time, the bill is covered; if they pay late, the builder has a liquidity problem.
Liquid and illiquid assets
Some assets turn into cash much faster than others. In financial markets, liquidity describes how quickly you can sell an investment without lowering its price.
Financial Edge Training ranks cash as the most liquid asset and property among the least liquid. Here’s how common business assets line up, starting with the most liquid.
- Cash in your business bank account, which you can spend straight away
- Short-term deposits, which you can usually access within days
- Accounts receivable, which become cash when customers pay their invoices
- Stock, which becomes cash only once you sell it
- Equipment, vehicles and property, which can take a long time to sell at a fair price
The first four items on this list are current assets. Equipment and property still add value to your business, but you’ll rely on the more liquid assets to pay a bill due next week.
How to measure liquidity
Liquidity ratios compare what you own in the short term with what you owe in the short term. There are three common measures, each stricter than the last, and this in-depth guide to each ratio has more examples.
Current ratio
The current ratio is the most widely used liquidity measure, and it’s also called the working capital ratio. It compares all your current assets with all your current liabilities, using the formula set out by AccountingTools.
Current ratio = current assets ÷ current liabilities
A result of 2.0 means you have €2 of current assets for every €1 you owe in the short term.
Quick ratio
The quick ratio, or acid-test ratio, leaves out stock and prepayments because they’re harder to turn into cash quickly. It still divides by your total current liabilities, as the AccountingTools quick ratio formula shows.
Quick ratio = (cash + marketable securities + accounts receivable) ÷ current liabilities
You’ll get the same answer by subtracting stock and prepayments from your current assets, then dividing by current liabilities.
Cash ratio
The cash ratio is the strictest test because it counts only cash and cash equivalents. It shows whether you could pay every current liability today using the money you already hold, based on the AccountingTools definition.
Cash ratio = (cash + cash equivalents) ÷ current liabilities
Cash equivalents are very short-term investments, such as deposits you can access almost immediately.
Worked example in euro
Say you run a café and your balance sheet shows these figures at the end of the month. They give you €50,000 in current assets.
- €15,000 in cash at the bank
- €10,000 owed by customers
- €20,000 in stock
- €5,000 in prepayments, such as insurance paid in advance
- €25,000 in current liabilities, including supplier bills and loan repayments
Here’s how the three ratios work out for the café.
Current ratio = €50,000 ÷ €25,000 = 2.0
Quick ratio = (€15,000 + €10,000) ÷ €25,000 = 1.0
Cash ratio = €15,000 ÷ €25,000 = 0.6
On paper, the café can cover its short-term debts twice over. Take stock out of the picture, though, and it relies on customers paying on time to meet every bill.
What is a good liquidity ratio?
A current ratio above 1.0 means you have more current assets than liabilities, according to AccountingTools. The same source notes that a very high ratio can point to cash or stock sitting idle when it could be put to work.
A ratio of around 2:1 is often treated as healthy, though the right level varies by industry. Treat these figures as rules of thumb and read up on interpreting your current ratio before you set your own target.
A ratio below 1.0 can be fine for a short spell. A growing business might dip below it while investing in stock or staff, so aim to climb back above it once that investment starts to pay off.
To compare like with like, measure at the same point in your billing cycle each month. That way, a large invoice run or supplier payment has less effect on the figures.
Why liquidity matters for your business
Good liquidity means you can pay staff, suppliers, Revenue and your lender on time. It also gives you room to handle a quiet month or an unexpected repair bill calmly.
Profit and liquidity measure different things. As AccountingTools points out, a business can report strong profits and still be short of cash. That can happen when customers pay slowly or when cash is tied up in stock.
Strong liquidity also helps when you apply for a loan or overdraft, since it shows you can keep up with repayments.
Liquidity vs solvency, working capital and cash flow
These terms all describe your financial health, but each one answers a different question. CFI defines liquidity as meeting short-term obligations and solvency as meeting long-term ones.
Here’s how each term compares with liquidity, which tells you how easily you can cover upcoming costs.
- Solvency is your ability to meet long-term obligations, such as a five-year business loan
- Working capital is the euro amount left when you subtract current liabilities from current assets
- Cash flow is the movement of money in and out of your business over a period
- Free cash flow is operating cash flow minus capital expenditure, or the cash left after investing in equipment and property
In the café example, working capital is €25,000. For a closer look at the first pair, read about how the two measures differ.
How to improve liquidity
Improving liquidity comes down to bringing cash in sooner and holding on to it for longer. These steps can help you strengthen your ratios over time.
- Send invoices as soon as the work is done and follow up promptly on overdue ones
- Offer customers more ways to pay, such as card or online bank transfer
- Ask suppliers for longer payment terms, especially if you’ve been a reliable customer
- Order stock in smaller batches so less cash sits on your shelves
- Sell equipment or vehicles you’ve stopped using
- Build a rolling cash flow forecast so you can spot shortfalls weeks ahead
- Arrange an overdraft while trading is strong and keep it as a short-term buffer for timing gaps
Keep track of your liquidity with Xero
Xero keeps your balance sheet up to date with automated bank feeds, so your current assets and liabilities are ready whenever you check your ratios. You can pull real-time financial reports and see your cash flow in one place.
That visibility helps you spot shortfalls early and make confident decisions about spending and growth. Try Xero today and get one month free.
FAQs on liquidity
Here are quick answers to common questions about liquidity.
Is liquidity the same as cash?
Cash is one part of liquidity, which also includes assets you can quickly turn into cash. A business with a low bank balance but invoices due this week can still be liquid.
What’s another word for liquidity?
In everyday business talk, people often say ‘cash position’ or ‘short-term financial health’. Liquid assets are also called quick assets, which is where the quick ratio gets its name.
Where do I find the figures to work out my liquidity?
Your balance sheet lists current assets and current liabilities separately, so you can calculate each ratio straight from it. Reconcile your accounts first, as unrecorded bills or payments will skew the result.
Can a business be liquid but insolvent?
Yes. A business could hold plenty of cash for this month’s bills yet owe more in long-term loans than its total assets are worth.
Should I include my overdraft when I calculate liquidity?
Any overdraft balance you’ve drawn counts as a current liability, so it goes in the denominator. The unused part of the facility isn’t an asset, but it gives you extra room to handle timing gaps.
Related terms
Learn more about liquidity
Handy resources
Advisor directory
You can search for experts in our advisor directory
Xero Small Business Guides
Discover resources to help you do better business
Online accounting with Xero
Automate your accounting in the cloud
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.