Free cash flow (FCF)
Learn what free cash flow is, how to calculate it and how to use it to plan your small business spending.
Published Wednesday 30 September 2026
Table of contents
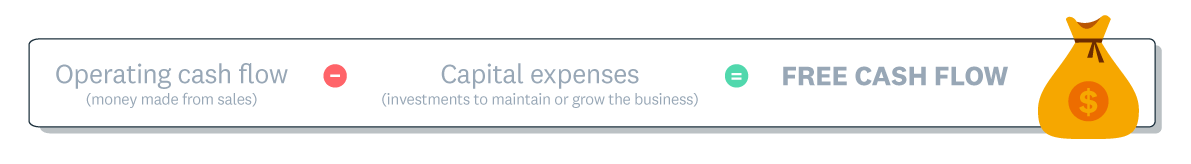
Free cash flow formula.
Key takeaways
- Free cash flow (FCF) is the cash your business generates from operations after capital expenditures, so it shows what’s genuinely available to spend or save
- FCF tracks real cash movements rather than profit on paper, which makes it a practical guide for decisions about hiring and big purchases
- The core formula is operating cash flow minus capital expenditures, and you can work it out in four steps from your cash flow statement
- You can raise FCF without growing sales, for example by collecting payments sooner or timing large equipment purchases carefully
What is free cash flow?
Free cash flow (FCF) is the cash your business has left from its everyday operations after paying for long-term assets like equipment or vehicles. It shows how much money you can actually use once running costs and investments are covered.
Think of it like your household budget after the mortgage and the car repairs are paid. Your business might be profitable on paper. If cash is tied up in stock or unpaid invoices, though, there’s less in the bank than your profit suggests.
FCF bridges that gap between what your income statement says you earned and what your bank balance shows. It gives you a straightforward measure of your financial flexibility.
Why free cash flow matters
FCF gives you and your lender a realistic view of your business’s financial health. Revenue and profit are useful, but FCF tells you whether there’s enough cash to run smoothly and grow.
Tracking FCF helps you in four practical ways.
- It shows your true spending power once all essential costs are covered
- It helps you plan ahead, especially when you’re forecasting your cash position for the months ahead
- It builds credibility with banks and investors who want to see that you can take on debt comfortably
- It supports decisions about whether now is the right time to hire or buy new equipment
Many Irish small businesses fund their plans from the cash they generate themselves. The Department of Finance published its SME Credit Demand Survey for 2025 on 4 June 2026. It found 82% of small and medium-sized enterprises (SMEs) that didn’t apply for credit had enough internal funds.
The same survey found only 16% of SMEs applied for bank finance in 2025, down from 20% in 2024. When your plans run on internal funds, FCF tells you how much you can safely commit.
Free cash flow formula
Free cash flow equals operating cash flow minus capital expenditures. Here’s the core free cash flow formula.
Free cash flow = operating cash flow – capital expenditures
Each part of the formula comes from a different section of your cash flow statement.
- Operating cash flow (OCF) is the cash your regular trading brings in, after paying suppliers and staff. It’s often labelled “cash from operations”.
- Capital expenditures (CapEx) are the money you spend on long-term assets your business needs. Common examples are new equipment, technology, vehicles or a workspace renovation.
If you’re starting from your profit and loss figures instead, there’s an alternative route. The Corporate Finance Institute’s guide to the FCF formula sets out this version.
Free cash flow = net income + depreciation and amortisation – change in working capital – CapEx
Both versions should land on a similar figure, because operating cash flow is net income adjusted for non-cash items and working capital. What’s left is cash you can use as you choose.
How to calculate free cash flow
You can calculate FCF in four steps once your financial statements are up to date. Work through them in order for the period you want to review.
1. Locate your operating cash flow
Start with your cash flow statement and find the section labelled “cash flows from operating activities”. This figure is your net income adjusted for non-cash items like depreciation.
It also reflects changes in working capital, such as movements in accounts receivable and accounts payable.
2. Identify your capital expenditures
Next, find your CapEx in the “cash flows from investing activities” section. It includes purchases of property, equipment, vehicles and other long-term assets.
If you use Xero accounting software, you can pull these figures straight from your reports.
3. Subtract capital expenditures from operating cash flow
Take your operating cash flow and subtract your CapEx. The result is your FCF for the period you’re analysing.
4. Review and compare across periods
One FCF figure is helpful, but tracking it monthly or quarterly tells you much more. Compare each result with previous periods to spot trends and seasonal patterns.
Free cash flow calculation example
A worked example shows how the formula plays out in a real business. Imagine you run a small landscaping business, and your quarterly cash flow statement shows these figures.
- Operating cash flow of €85,000
- Capital expenditures of €20,000 for a new mower and trailer
Using the formula, free cash flow = €85,000 – €20,000 = €65,000. That’s the cash your business generated that quarter after covering operating costs and new equipment.
Now imagine the next quarter: operating cash flow drops to €60,000 and you spend €35,000 on a used van. Your FCF would be €25,000. The drop reflects a planned investment, and it tells you to be more careful with optional spending that quarter.
What you can do with positive free cash flow
Positive FCF gives you choices about where your spare cash goes. Small businesses commonly put it to work in five ways.
- Pay down loans or overdrafts early to cut interest costs
- Build a cash reserve that covers quiet months or unexpected bills
- Reinvest in new equipment or extra staff to take on more work
- Pay yourself through drawings as a sole trader, or dividends if you run a limited company
- Fund growth plans from your own cash instead of borrowing
For example, the landscaping business above could put €30,000 towards its van loan and keep €35,000 in reserve. Knowing your FCF each month makes that split easier to decide.
How free cash flow compares to other financial metrics
FCF is one of several metrics that measure the health of your business. Each captures something different, so it helps to know how they relate.
- Cash flow covers all the money moving in and out of your business, including investing and financing activities. Free cash flow narrows this to cash left from operations after CapEx.
- Operating cash flow is the cash your everyday trading brings in, before any spending on long-term assets. Free cash flow starts there and subtracts CapEx.
- Free cash flow and EBITDA (earnings before interest, taxes, depreciation and amortisation) differ because EBITDA leaves out capital spending. The Corporate Finance Institute’s EBITDA explainer describes it as a profitability measure, whereas FCF shows cash left after investment.
- Working capital compares current assets with current liabilities at a single point in time. Free cash flow measures the cash generated over a whole period.
- Net income includes non-cash charges like depreciation and depends on accounting choices. Free cash flow adds those back to show the cash your business produced.
- Liquidity describes how easily you can access cash or turn assets into cash, often measured with liquidity ratios. Free cash flow is one input into that wider picture.
Each metric adds a piece of the story. Tracking FCF alongside your other financial statements gives you a fuller view of where your business stands.
Types of free cash flow
There are two main types of FCF, and they differ in whose share of the cash they measure.
- Free cash flow to the firm (FCFF), also called unlevered free cash flow, is cash available to all lenders and owners. It’s calculated before interest and debt repayments.
- Free cash flow to equity (FCFE), sometimes called levered free cash flow, is the cash left for owners after debt payments. You could pay it out as dividends or keep it as retained earnings.
For most small business owners, the standard formula works well for everyday decisions. FCFF and FCFE become more useful when you’re seeking investment or preparing to sell.
How to interpret free cash flow
Your FCF figure makes most sense when you read it in context. Start with whether it’s positive or negative, then look at how it moves over time.
Positive FCF means your business generates more cash than it spends on operations and investment. Consistently positive FCF over several quarters is a sign of a financially stable business.
Negative FCF can be a normal result of a large, planned investment, like new equipment or a second location. What matters is whether it’s a short-term, deliberate dip or a recurring pattern that needs a closer look at your costs.
Trends tell you more than a single number, so review FCF over at least four quarters. A steady rise shows stronger cash generation, while a steady fall is a prompt to check costs and collections.
Outside conditions matter too. A dip in FCF during a slow season or wider downturn may reflect demand across your sector rather than how you run the business. Compare your numbers with what similar businesses are seeing.
How to improve free cash flow
You can strengthen FCF by bringing cash in sooner and holding onto it for longer. These practical steps each help.
- Send invoices as soon as work is done, and use online invoices so customers can pay directly
- Ask suppliers for longer payment terms so cash stays in your account for longer
- Review subscriptions and services you rarely use, and try these practical ways to cut business costs
- Order stock to match actual demand, as excess inventory ties up cash
- Space out large purchases or lease equipment to spread the cost
- Adjust your prices or add a complementary service to lift operating cash flow
Small changes across several areas often add up to more than one big change. Review your FCF each month to see which steps make the most difference.
Benefits and limitations of free cash flow
FCF is a valuable metric, and like any measure it has strengths and blind spots. Knowing both helps you use it well.
Tracking FCF gives you four clear benefits.
- It reflects real cash, so it’s harder to distort than net income
- It helps you budget for investments and debt payments with more confidence
- It lets you benchmark your business across periods or against similar businesses
- It signals financial strength to lenders and potential buyers
FCF also has four limitations to keep in mind.
- It can swing sharply, as one large purchase can turn a strong quarter negative
- It leaves out loan repayments and owner drawings, so it isn’t a full list of your cash commitments
- It can be shifted by timing, such as delaying a purchase until next quarter
- It works best alongside working capital and profit margins
Track your free cash flow with Xero
Knowing your FCF puts you in a stronger position to plan your next move. With the right tools, tracking it becomes part of your regular routine.
Xero brings your bank transactions and reports into one place, so you have the figures you need to calculate FCF. Its cash flow forecasting tools help you see what’s coming before you commit to a big purchase or loan.
Choose a plan that suits your business and get one month free to see your cash position clearly.
FAQs on free cash flow
These answers cover common questions small business owners ask about free cash flow.
What is a good free cash flow?
A good FCF is one that stays positive and covers your loan repayments with room to spare. Dividing FCF by revenue gives you an FCF margin you can track against your own past results.
Can a business have negative free cash flow?
Yes, and it’s common in periods when a business is buying equipment and building stock. Plan how long it will last and how you’ll cover the gap, whether from savings or an agreed overdraft.
Is EBITDA the same as free cash flow?
No. A fast-growing business can report strong EBITDA while its FCF is negative, because cash is going into new equipment and extra stock.
What counts as capital expenditure?
Capital expenditure is spending on assets you’ll use for more than a year, such as vans, machinery, computers or shop fit-outs. Routine repairs and maintenance are operating expenses, so they sit in operating cash flow instead.
How often should you calculate free cash flow?
Monthly works well for most small businesses, as it fits with your regular bookkeeping. A quarterly review with your accountant then adds context from your full financial statements.
Does free cash flow include loan repayments?
Standard FCF is calculated before you repay loan capital, so check that it covers your repayment schedule. FCFE is the version that deducts debt payments, showing what’s left for owners.
Related terms
Learn more about free cash flow
Handy resources
Advisor directory
You can search for experts in our advisor directory
Cash flow statement template
Download our template to help you stay across cash flow for your business
Financial reporting
Keep track of your performance with accounting reports
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.