Current ratio: formula, calculation and interpretation
Learn how to calculate your current ratio, read the result and use it to plan your business cash.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Tuesday 6 October 2026
Table of contents
Key takeaways
- Divide current assets by current liabilities to get your current ratio, which shows whether you can pay your short-term bills
- Aim for a current ratio of 1.5–3.0, since below 1.0 can signal trouble paying bills and above 3.0 may mean assets are sitting idle
- Calculate it on the same day each month so you can spot trends and cash flow issues early
- Pair it with the quick ratio, working capital and cash flow forecasts, because it’s a single-date snapshot that treats inventory like cash
What is the current ratio?
The current ratio measures whether your business can pay its short-term bills and loan repayments with the assets it has. You might also see it called the working capital ratio.
It’s a type of liquidity ratio that gives you a broader view than the quick ratio. That’s because it includes assets that take longer to turn into cash, like inventory.
Think of it as a stress test. If every bill due this year arrived today, could the assets you’ll turn into cash this year cover them?
What are current assets and current liabilities?
To calculate your current ratio, you need two numbers from your balance sheet: current assets and current liabilities. Both relate to the next 12 months.
Current assets are resources you can turn into cash within 12 months, including:
- cash and cash equivalents, or money in your bank accounts
- accounts receivable, or payments your customers owe you
- inventory, or products you plan to sell
- prepaid expenses, or costs you’ve paid in advance
Current liabilities are obligations you must pay within 12 months, including:
- accounts payable, or bills you owe suppliers
- short-term loans, or debt due within the year
- accrued expenses, or costs you’ve incurred but haven’t paid yet
- the current portion of long-term debt, or loan repayments due this year
Each total usually appears as its own line, with current assets listed under assets and current liabilities under liabilities.
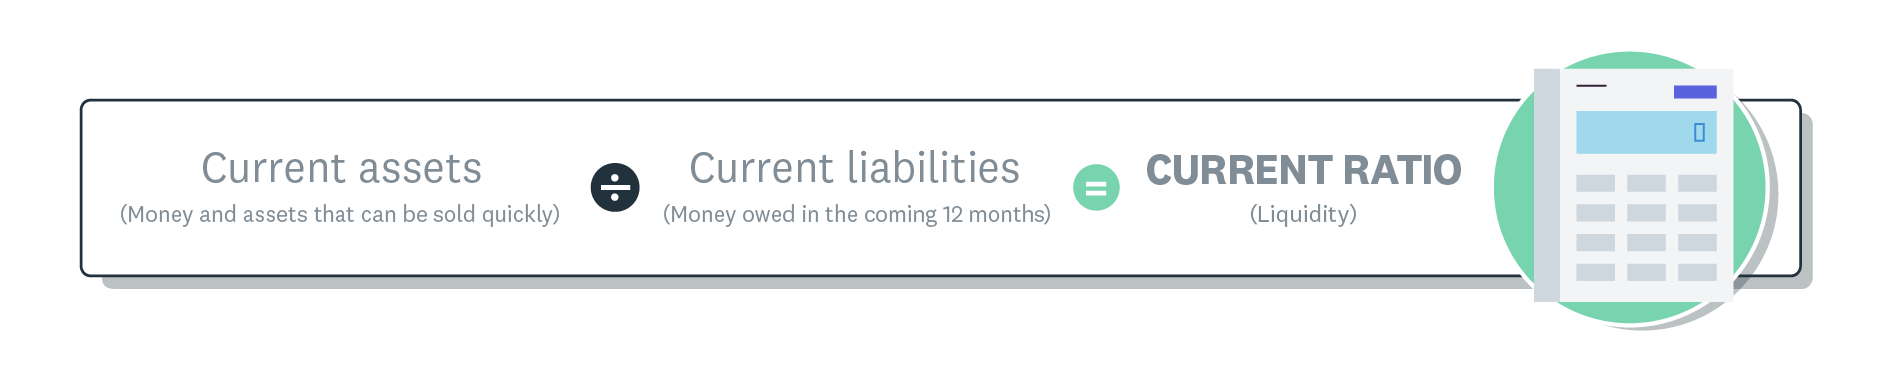
Current ratio liquidity formula.
How to calculate current ratio
The current ratio formula is simple: divide your total current assets by your total current liabilities.
Current ratio = current assets ÷ current liabilities
Both numbers come straight from your balance sheet, so it’s one of the easiest financial ratios to work out. Follow these steps:
- Find your total current assets.
- Find your total current liabilities.
- Divide current assets by current liabilities.
- Round the result to two decimal places.
Current ratio calculation example
Here’s how the calculation works for a small construction business. The owner wants to check the business can cover upcoming loan repayments and material costs, so they pull the numbers from the month-end balance sheet.
Start with current assets. Adding them line by line gives cash $60,000 + accounts receivable $95,000 + inventory $80,000 + prepaid expenses $15,000 = $250,000.
Next, total the current liabilities the same way. That’s accounts payable $70,000 + short-term loan $50,000 + accrued expenses $30,000 + current portion of long-term debt $25,000 = $175,000.
Now divide the two totals: $250,000 ÷ $175,000 = 1.4286, which rounds to 1.43. The business has $1.43 of current assets for every $1 of current liabilities.
Subtracting liabilities from assets also shows $75,000 of working capital. That cushion gives the owner room to invest in growth or hold cash as a buffer for leaner periods. Because 1.43 sits just below the 1.5–3.0 range, keeping some of it as a buffer is the safer choice.
How to interpret your current ratio
Once you have your number, the next step is working out what it says about your business. Use these guidelines when you read your result:
- a ratio below 1.0 means you may struggle to pay suppliers on time, unless it’s a short dip while you invest in growth
- a ratio of exactly 1.0 means you can just cover your bills, with no buffer for surprise costs
- a ratio between 1.0 and 1.5 means you can meet your obligations, with a thin margin for unexpected expenses
- a ratio of 1.5–3.0 gives you a comfortable cushion and is a healthy target for most small businesses
- a ratio above 3.0 may mean you’re holding assets you could put to work in growth
- a good ratio varies by industry, so compare your result with similar businesses
- a trend tells you more than one result, so measure on the same day each month, such as the last day
- a ratio works best alongside other measures, like the quick ratio and cash flow forecasts
Current ratio vs quick ratio and other liquidity ratios
Different liquidity ratios measure your financial health in different ways. The two most common alternatives to the current ratio are:
- the quick ratio, or acid test ratio, which leaves out inventory and counts only assets you can turn into cash within 90 days
- the cash ratio, which compares only cash and cash equivalents with current liabilities
The quick ratio gives you a more conservative view of your liquidity. The cash ratio shows whether you could pay your bills right now. Using several ratios together gives you a fuller view of your cash position.
Current ratio in relation to working capital and cash flow
Your current ratio is closely tied to other measures of your business’s spending power. Seeing how they connect helps you understand your whole financial position.
Working capital is the dollar amount left when you subtract current liabilities from current assets. It’s the money you have for day-to-day running costs.
The current ratio shows your liquidity as a ratio, while working capital shows it as a dollar amount. Aim for a balanced level of working capital: enough to pay bills comfortably, without large sums sitting idle.
Cash flow measures add detail on how money moves through your business. The two to watch are:
- cash flow, or the net amount of money moving in and out of your bank account
- free cash flow, or what’s left of operating cash flow after spending on equipment or property
What are the limitations of current ratio?
The current ratio is useful, but it has limits worth knowing before you rely on it. Keep in mind that the ratio:
- shows your position on one date only, while your finances change daily
- treats all assets the same, even though cash is available now and inventory can take months to sell
- assumes all liabilities fall due at once, when payments actually land at different times
- may give an unusual reading if your sales change a lot by season
A cash flow forecast shows when money actually comes in and goes out, which fills the timing gap the ratio leaves.
Track your current ratio easily with Xero
Let Xero handle the calculations, so you get a clear view of your business’s financial health without the manual work. With Xero, you can:
- see cash flow at a glance, with money in and out tracked in real time
- monitor key metrics like your current ratio over time
- build cash flow forecasts using built-in reporting
- make confident decisions with the insights you need to plan ahead
Sign up to get one month free and see how Xero makes managing your finances simpler.
FAQs on current ratio
Here are answers to common questions about calculating and using the current ratio.
What is a good current ratio?
A good current ratio usually falls in the 1.5–3.0 range, though the right target depends on your industry and how quickly your stock sells. Businesses that hold little inventory can often run comfortably near the lower end.
What does a current ratio of 2.5 mean?
A current ratio of 2.5 means you have $2.50 in current assets for every $1.00 of current liabilities. It sits well within the 1.5–3.0 range, so you can meet short-term obligations with room to spare.
Is a current ratio of 1.0 acceptable?
A current ratio of 1.0 is the minimum acceptable level, because your assets only just cover your liabilities. One late customer payment or a large one-off bill could leave you short.
How often should I calculate my current ratio?
Calculate your current ratio monthly at a consistent point, such as the last day of the month. Checking more often during tight or seasonal periods helps you act on cash flow issues sooner.
What’s the difference between current ratio and quick ratio?
The quick ratio leaves out inventory and counts only assets you can turn into cash within 90 days. That means your quick ratio will always be equal to or lower than your current ratio.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.