Quick ratio vs current ratio: what’s the difference?
Compare the quick ratio and current ratio, see how to calculate each, and learn what your results mean.
February 2024 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- The current ratio compares all your current assets with your current liabilities to show whether you can cover bills due within a year
- The quick ratio leaves out inventory and prepaid expenses, giving a stricter view of how well your most liquid assets cover short-term debts
- A wide gap between the two ratios shows how much of your liquidity depends on selling stock
- Healthy levels vary by industry, so compare your ratios with similar businesses and track them over time
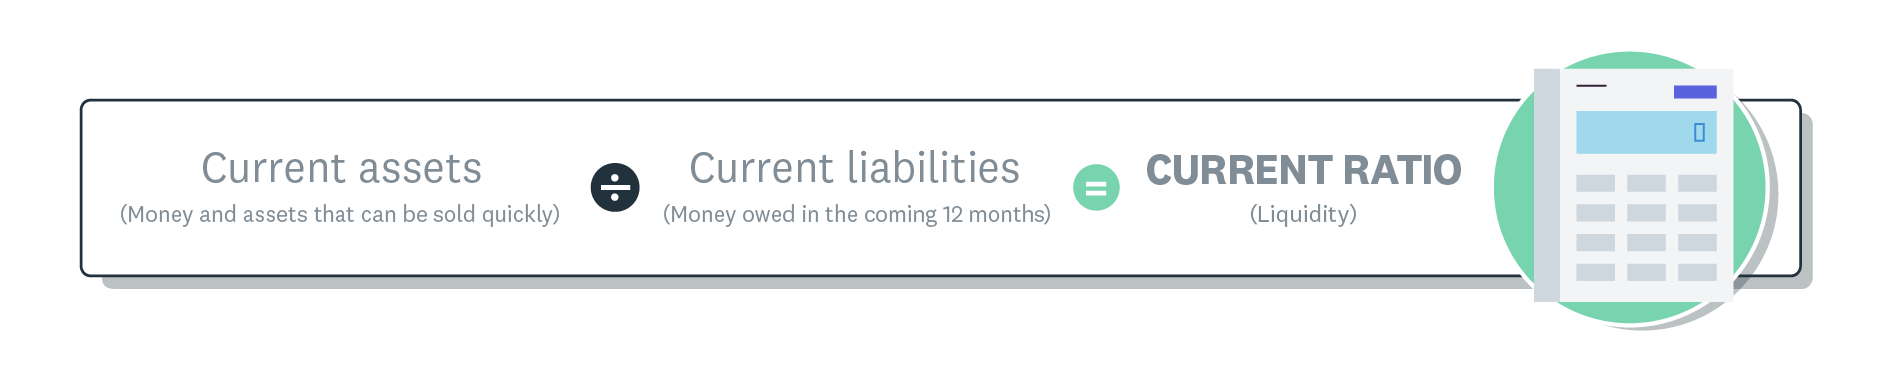
Current ratio liquidity formula.
What is the current ratio?
The current ratio, also called the working capital ratio, shows whether your current assets can cover your current liabilities. The Corporate Finance Institute (CFI) comparison guide describes it as a measure of your ability to pay short-term obligations due within a year.
The formula for calculating the current ratio is:
Current ratio = current assets / current liabilities

Quick ratio formula Version 1.
Both figures come from your balance sheet. Your current assets include cash, accounts receivable, inventory and prepaid expenses. Your current liabilities include accounts payable, short-term loans, taxes owed and other debts due within 12 months.

Quick ratio formula Version 2.
In Indonesia, these figures often come from statements prepared under SAK EMKM for micro, small and medium entities or SAK EP for private entities.
Current ratio example
Say your business has Rp1.5 billion in current assets and Rp1 billion in current liabilities. Here’s the calculation:
Current ratio = Rp1.5 billion / Rp1 billion = 1.5
A current ratio of 1.5 means you have Rp1,500 in current assets for every Rp1,000 you owe over the next year.
What is the quick ratio?
The quick ratio, also called the acid test ratio, measures whether you can pay short-term debts using only your most liquid assets. It leaves out inventory and prepaid expenses because they’re slower to turn into cash.
According to CFI’s quick ratio guide, you can calculate the quick ratio in two ways. Version 1 adds up your most liquid assets, including accounts receivable:
Quick ratio = (cash + marketable securities + accounts receivable) / current liabilities
Version 2 starts with all current assets and subtracts the ones that take longer to convert:
Quick ratio = (current assets – inventory – prepaid expenses) / current liabilities
Both versions give the same result when your balance sheet is complete, so pick whichever matches the figures you have to hand.
Why inventory is excluded
Handy resources
Advisor directory
You can search for experts in our advisor directory.
Balance sheet template
See where and how assets and liabilities are reported.
Push-button liquidity reporting
Check your current ratio whenever you like with Xero’s accounting dashboard.
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.
Inventory can take too long to sell to cover pressing bills, and prepaid expenses can’t be used to pay other liabilities, as CFI explains. If a supplier invoice is due on Friday, you can’t count on clearing a warehouse of stock by then.
Quick ratio example
Using the same business, the Rp1.5 billion in current assets breaks down like this:
- Rp300 million in cash
- Rp500 million in accounts receivable
- Rp550 million in inventory
- Rp150 million in prepaid expenses
Using version 2 of the formula with Rp1 billion in current liabilities:
Quick ratio = (Rp1.5 billion – Rp550 million – Rp150 million) / Rp1 billion = 0.8
The current ratio looked comfortable at 1.5, but the quick ratio of 0.8 shows this business needs some inventory sales to cover every short-term bill.
Key differences between the quick ratio and current ratio
Both ratios measure short-term liquidity, and the difference comes down to which assets count. The quick ratio drops inventory and prepaid expenses, so it’s always equal to or lower than the current ratio.
Here’s how the two ratios compare:
- The current ratio counts all current assets, including inventory and prepaid expenses
- The quick ratio counts only cash, marketable securities and accounts receivable
- The quick ratio gives a more conservative view because it leaves out slower-to-convert assets
- The current ratio suits broader planning, while the quick ratio shows what you can pay from assets that turn into cash quickly
Your business model shapes which one matters more. Inventory-heavy businesses such as retailers may lean on the current ratio, while businesses holding little inventory often see the two ratios sit close together.
What the gap between your ratios tells you
The gap between your current and quick ratio shows how much of your liquidity sits in inventory and prepaid expenses. According to CFI, a wide gap often signals heavy reliance on inventory. That can suit a retailer but raise concerns in low-inventory sectors like tech.
In the example above, the gap is 0.7, which equals Rp700 million held in stock and prepayments. If that gap widens month after month, stock may be building up faster than you’re selling it.
How to interpret your results
A ratio above 1.0 means your assets cover your short-term debts, while a ratio below 1.0 means you owe more than those assets are worth. What counts as healthy depends on your industry, so treat any benchmark as a guide.
Current ratio benchmarks
According to CFI’s liquidity benchmarks, analysts often consider a current ratio of 1.5–3.0 healthy, though retailers may operate well at around 0.90. Here’s how to read your result:
- Above 1.0 means your current assets cover your current liabilities
- Below 1.0 means you may need extra revenue or funding to meet short-term bills
- Well above the healthy range can mean cash or stock is sitting idle
- A steady fall over several months is a cue to review your cash flow
Quick ratio benchmarks
CFI’s guidance puts a typical quick ratio above 1.0 and an ideal one at 1.0–1.5, though retailers may run as low as 0.30. A result below 1.0 means you’d rely on stock sales or new funding to meet every upcoming bill.
Industry context
Healthy liquidity ratios vary by industry. Businesses that hold lots of stock tend to have lower quick ratios, since stock is left out of the calculation. Track your own ratios over time and compare them with businesses like yours.
When to use the quick ratio vs the current ratio
Use the current ratio for a broad 12-month view and the quick ratio to check whether your most liquid assets alone can cover your bills. Your business type decides which one you’ll lean on most.
Here’s when each ratio works best:
- Use the current ratio for a broad view of your short-term financial health
- Use the quick ratio to check whether you can cover bills without relying on inventory sales
- Use the quick ratio during seasonal stock build-ups, since it stays steady when inventory levels swing
- Use both together when preparing a loan application or reviewing your cash flow strategy
If your business holds little inventory, both ratios will look similar because there’s little stock to exclude. Compare each month’s ratios with your cash flow forecast so you can see pressure building before bills fall due.
The cash ratio: a stricter liquidity check
The cash ratio compares only your cash and cash equivalents with your current liabilities. It’s the strictest of the three liquidity checks because it leaves out receivables as well as inventory.
The formula for calculating the cash ratio is:
Cash ratio = (cash + cash equivalents) / current liabilities
AccountingTools’ cash ratio guide calls it the most conservative liquidity measure, as it excludes inventory and accounts receivable. Using the earlier example, Rp300 million in cash against Rp1 billion in current liabilities gives a cash ratio of 0.3.
That means you could pay Rp300 of every Rp1,000 you owe today, without waiting on customers or sales. For a longer-term view beyond these short-term checks, compare liquidity and solvency.
How to improve your liquidity ratios
You can lift your liquidity ratios by bringing cash in sooner and keeping short-term debts in check. Here are 5 ways to improve your liquidity:
- Collect receivables sooner by setting clear payment terms and following up on overdue invoices
- Agree longer credit periods with suppliers to ease pressure on your current liabilities
- Keep inventory lean so less cash sits on shelves for months
- Build a cash reserve to cover unexpected costs or slow-paying customers
- Review your ratios regularly alongside your financial statements to catch trends early
Small gains in collections or stock control can move both ratios in the right direction. Aim for enough liquidity to keep your business running smoothly through quiet months.
Track your business liquidity with Xero
Reliable liquidity ratios start with accurate, up-to-date figures. When your balance sheet is current, you can trust every ratio you calculate.
Xero’s cloud accounting software brings in your bank transactions automatically and keeps your balance sheet up to date in real time. You can check your quick ratio and current ratio whenever you need to, so try Xero and get one month free.
FAQs on quick ratio vs current ratio
Here are answers to common questions about the quick ratio vs current ratio.
What is a good quick ratio for a small business?
A quick ratio of 1.0 or above is a common rule of thumb, but the right level depends on your industry. Your own trend over several months is often more useful than any single benchmark.
Is 0.5 a good quick ratio?
A quick ratio of 0.5 means you have Rp500 in liquid assets per Rp1,000 owed, so you’d need stock sales or funding for every bill. That can work for some inventory-heavy retailers, but most other businesses would aim to lift it closer to 1.0.
Can a high quick ratio be a bad sign?
It can, as a very high quick ratio may mean cash is sitting idle instead of funding equipment or growth. Weigh it against your plans for the year to decide whether some of that cash could be put to work.
Can a company have a high current ratio but a low quick ratio?
Yes, this happens when much of your current assets sit in stock or prepayments. A retailer holding Rp2 billion in stock might have a strong current ratio but a weak quick ratio, relying on sales to pay bills.
How often should you calculate liquidity ratios?
Monthly works well for most small businesses, ideally at the same point in your billing cycle each time. Consistent timing gives you comparable figures, so you can spot trends instead of reacting to one-off swings.
Which ratio do lenders look at when assessing a business loan?
Lenders may review your liquidity ratios alongside other financial information, and each lender sets its own criteria. Ask your lender or accountant which figures matter most for your application.