Prepare Irish VAT and RTD returns for your clients
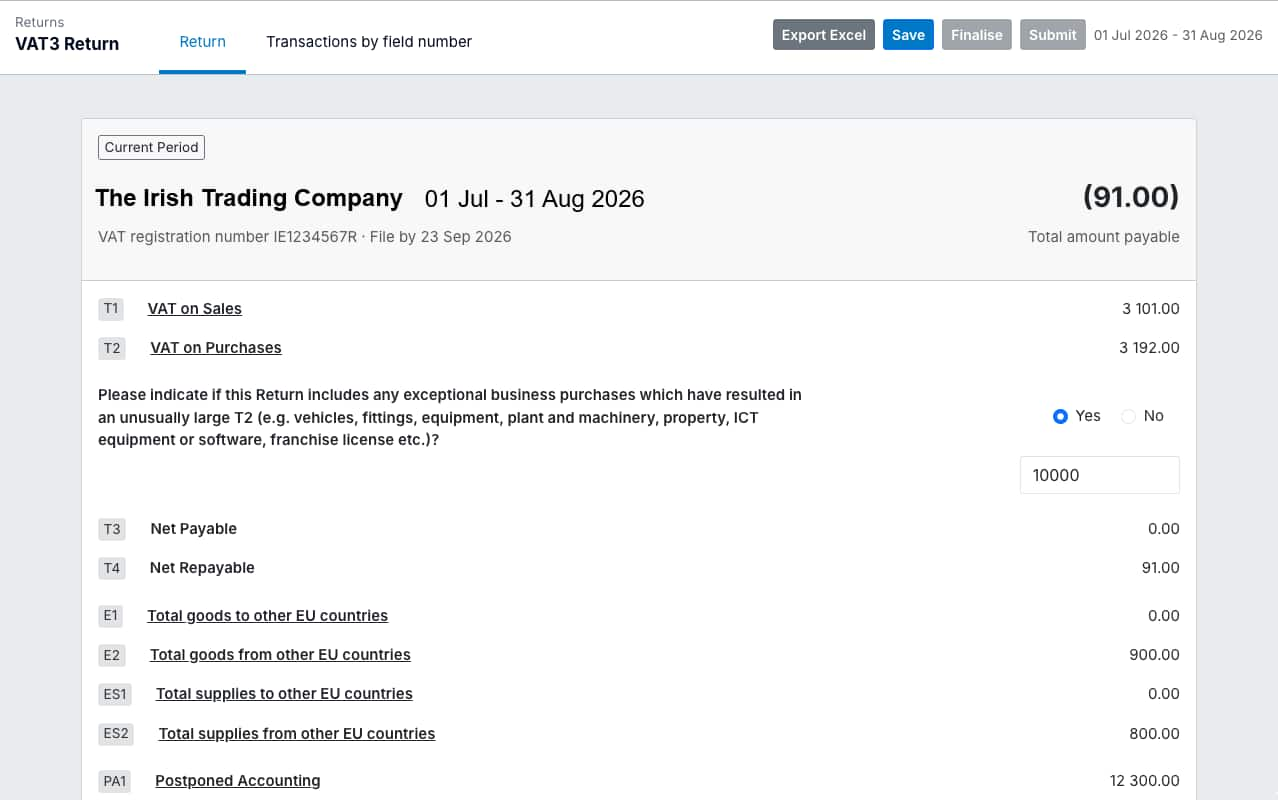
Xero works out the VAT on every invoice and bill as you enter it, so your figures are ready when your filing period closes. Prepare your VAT 3 return, compile your annual Return of Trading Details, and export for submission through ROS.
Irish VAT rates built in
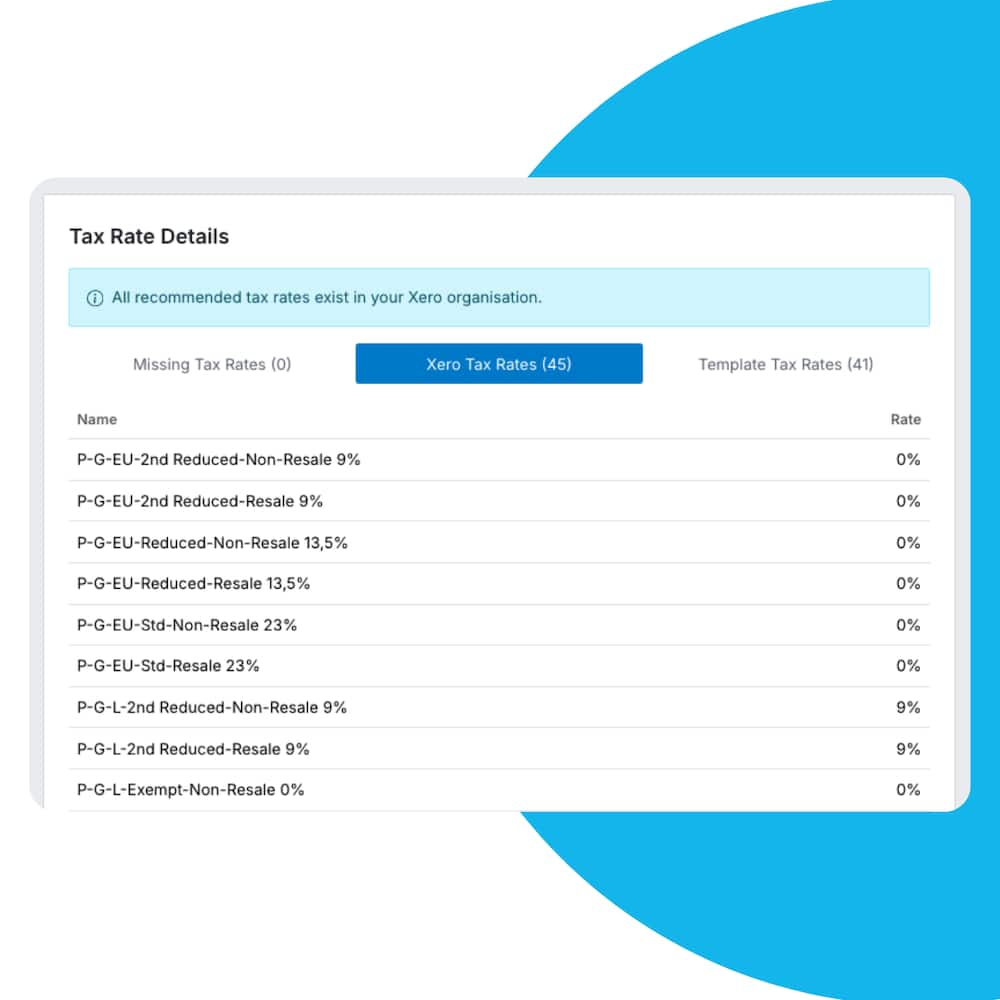
Standard, reduced, second reduced, zero and exempt rates, ready to use.
VAT calculated automatically
Xero works out the VAT on every invoice, bill and quote.
Prepare your VAT 3 for Revenue
Prepare and export your VAT return to submit via ROS.
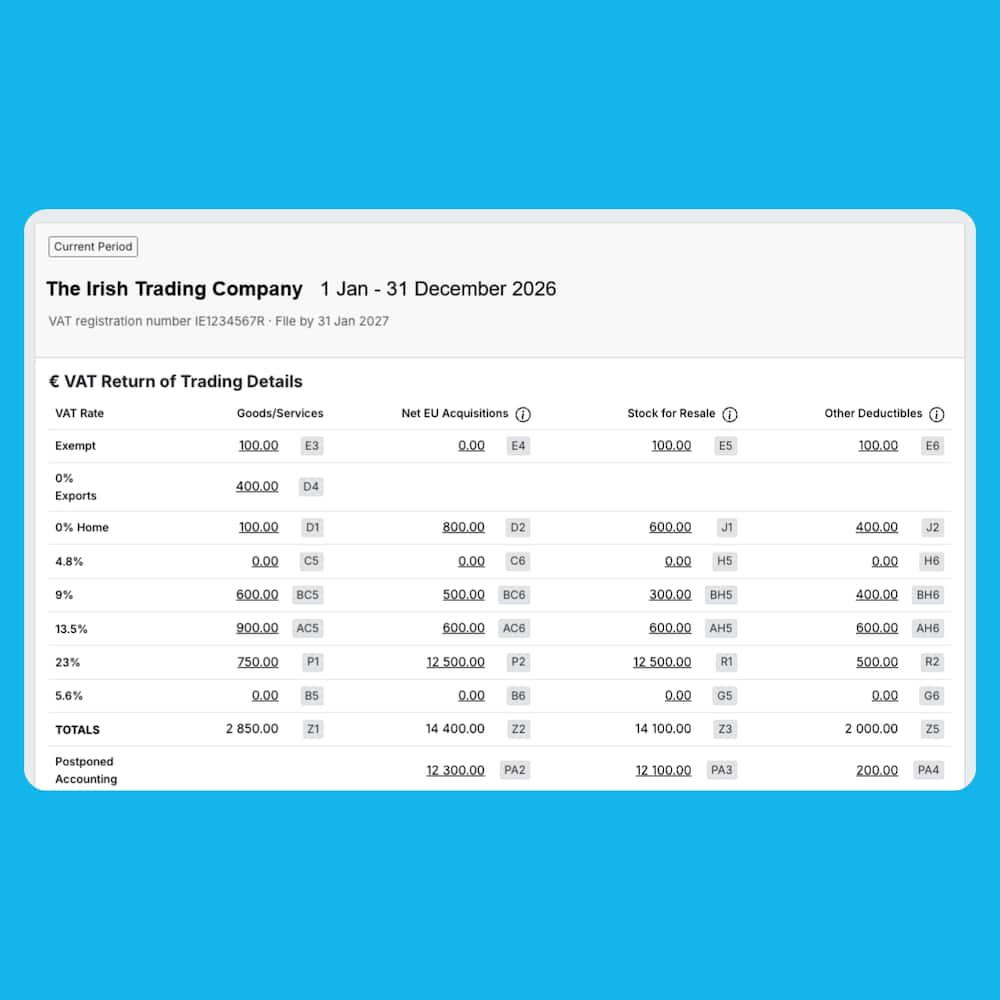
Annual RTD from the same figures
Compile your Return of Trading Details without rebuilding it.
Plans to suit your business
All pricing plans cover the accounting essentials, with room to grow.
Irish VAT rates, built into Xero
Ireland's VAT rates are already set up in Xero – the standard rate, both reduced rates, the zero rate and exempt supplies. Raise an invoice or enter a bill, pick the rate from the dropdown, and the VAT is worked out for you. Your VAT is right from day one.
- Apply VAT on the invoices you send and the bills you pay
- Set default VAT rates for your contacts, inventory items and accounts
- Add your own rate, or override the VAT on a single line when you need to
VAT calculated on every transaction
Pick a VAT rate once and Xero works out the VAT on every line of an invoice, quote, purchase order or bill, and keeps a running total for the period. Enter your amounts as VAT inclusive or VAT exclusive, whichever suits the way you work.
- Xero works out VAT on every transaction, from a one-off quote to a monthly bill
- Record amounts as VAT inclusive, VAT exclusive, or zero-rated
- See the VAT on each line before you send or approve the transaction
Prepare your VAT 3 return and annual RTD
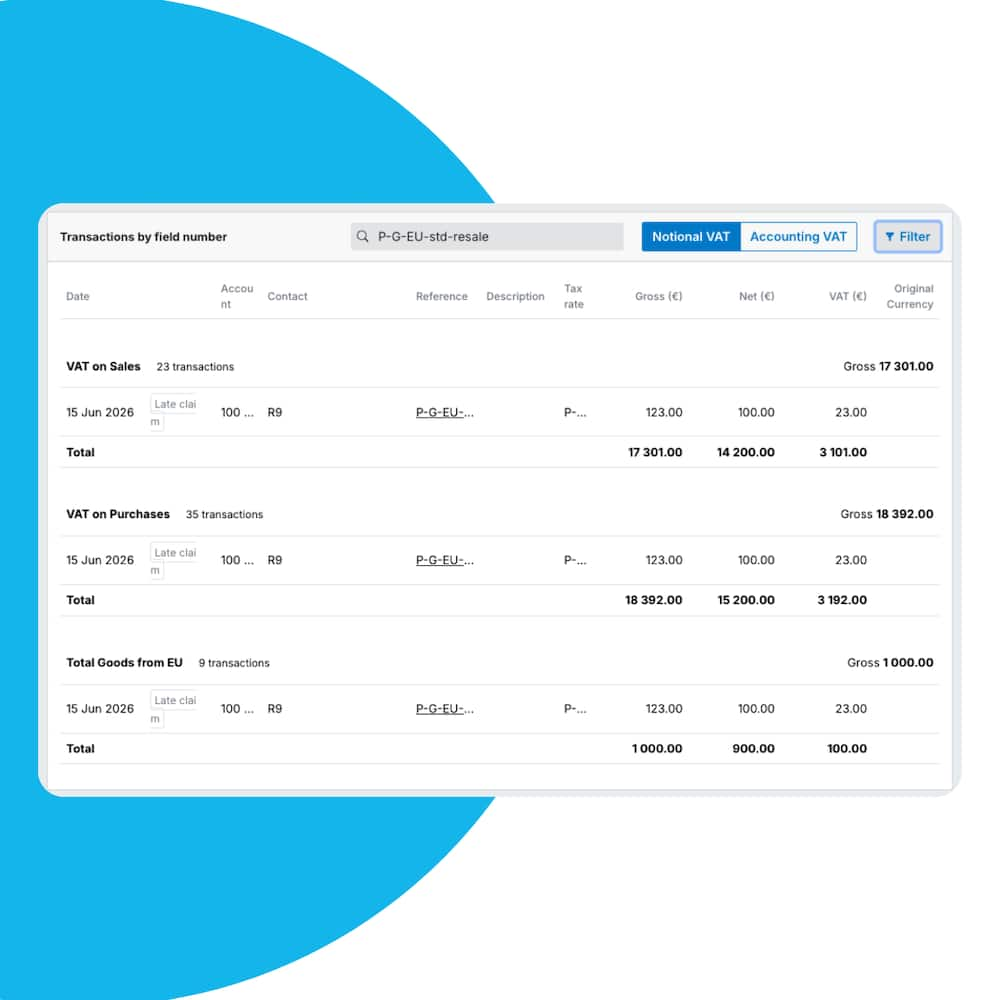
When your filing period closes, run the VAT report in Xero. Your figures come straight from the transactions you have already recorded, so there is nothing to re-key. Review your VAT 3 return, then export it for ROS submission. Compile and review your annual RTD from the same figures.
- Drill into the transactions behind any figure
- Export a reviewed VAT 3 return for submission through ROS
- Compile your annual RTD from the same figures, rather than rebuilding it by hand
- Switch between the Cash Basis (Monies received) and invoice basis for your VAT figures
Handle EU and reverse charge VAT
Selling into other EU countries, or buying services from suppliers there, changes how VAT is treated. Pick the right rate in Xero and the amounts carry through to the correct boxes on your VAT 3 and your annual RTD, so trading abroad does not mean a separate spreadsheet.
- Zero-rate intra-EU supplies to VAT-registered customers
- Apply the reverse charge on services you buy from abroad
- Keep cross-border figures feeding into your VAT 3 and RTD
FAQs about submitting VAT returns online in Ireland
As a Xero partner, you’ll have access to this solution for clients on Starter, Standard or Premium plans. Access by connecting the Xero Compliance Ireland app here.
If you’re not a Xero partner, become one today - Join the partner program
As a Xero partner, you’ll have access to this solution for clients on Starter, Standard or Premium plans. Access by connecting the Xero Compliance Ireland app here.
If you’re not a Xero partner, become one today - Join the partner program
If you file through ROS, your VAT 3 return and the payment are both due by the 23rd of the month after your taxable period ends. Most businesses file bi-monthly, so the January–February period is due on 23 March. Paper returns are due by the 19th, but almost all filing is now done online through ROS. Check revenue.ie for the deadlines that apply to your business.
If you file through ROS, your VAT 3 return and the payment are both due by the 23rd of the month after your taxable period ends. Most businesses file bi-monthly, so the January–February period is due on 23 March. Paper returns are due by the 19th, but almost all filing is now done online through ROS. Check revenue.ie for the deadlines that apply to your business.
Yes, if Revenue agrees to it. Most businesses file bi-monthly, but Revenue can move you to quarterly, four-monthly, half-yearly or annual filing depending on the size of your VAT liability. Annual filing usually comes with a direct debit arrangement so you spread payments across the year. You need to apply to Revenue to change your filing frequency, so talk to your accountant about whether it suits your business.
Yes, if Revenue agrees to it. Most businesses file bi-monthly, but Revenue can move you to quarterly, four-monthly, half-yearly or annual filing depending on the size of your VAT liability. Annual filing usually comes with a direct debit arrangement so you spread payments across the year. You need to apply to Revenue to change your filing frequency, so talk to your accountant about whether it suits your business.
The RTD is an annual return that summarises your supplies, purchases and imports broken down by VAT rate. It does not create a VAT liability of its own, but Revenue uses it to cross-check the totals on your VAT 3 returns, so the figures need to line up. It is due within 23 days of the end of your accounting period. Xero compiles your RTD from the transactions you have already recorded.
The RTD is an annual return that summarises your supplies, purchases and imports broken down by VAT rate. It does not create a VAT liability of its own, but Revenue uses it to cross-check the totals on your VAT 3 returns, so the figures need to line up. It is due within 23 days of the end of your accounting period. Xero compiles your RTD from the transactions you have already recorded.
You must register with Revenue if your turnover from taxable supplies goes over the registration threshold, or if you expect it to in the next 12 months. There are two thresholds: €42,500 for services and €85,000 for goods. Businesses with no establishment in Ireland must register regardless of turnover. Thresholds change from time to time, so check the current figures on revenue.ie before you decide.
You must register with Revenue if your turnover from taxable supplies goes over the registration threshold, or if you expect it to in the next 12 months. There are two thresholds: €42,500 for services and €85,000 for goods. Businesses with no establishment in Ireland must register regardless of turnover. Thresholds change from time to time, so check the current figures on revenue.ie before you decide.
Xero helps you prepare and review your VAT 3 return using the transactions already recorded. Export the reviewed return from Xero, then submit it through ROS. Xero keeps the underlying transactions and reports together for review.
Xero helps you prepare and review your VAT 3 return using the transactions already recorded. Export the reviewed return from Xero, then submit it through ROS. Xero keeps the underlying transactions and reports together for review.
Under the reverse charge, the customer accounts for the VAT instead of the supplier. It applies to services you buy from suppliers in other EU countries, and in the construction sector where Relevant Contracts Tax applies — there, the principal contractor accounts for the VAT rather than the subcontractor charging it. In Xero you apply a reverse charge rate to the transaction and the amounts carry into the right boxes on your VAT 3.
Under the reverse charge, the customer accounts for the VAT instead of the supplier. It applies to services you buy from suppliers in other EU countries, and in the construction sector where Relevant Contracts Tax applies — there, the principal contractor accounts for the VAT rather than the subcontractor charging it. In Xero you apply a reverse charge rate to the transaction and the amounts carry into the right boxes on your VAT 3.
To reclaim VAT you generally need a valid VAT invoice showing the supplier's VAT number, the rate applied and the VAT amount. Revenue can disallow a claim if you cannot produce one, so it is worth capturing invoices as you go rather than hunting for them at the end of the period. Xero stores the invoice or receipt against the transaction, so the evidence sits with the record.
To reclaim VAT you generally need a valid VAT invoice showing the supplier's VAT number, the rate applied and the VAT amount. Revenue can disallow a claim if you cannot produce one, so it is worth capturing invoices as you go rather than hunting for them at the end of the period. Xero stores the invoice or receipt against the transaction, so the evidence sits with the record.
Revenue requires you to keep VAT records and supporting documents for six years. Xero retains your VAT 3 returns along with the underlying transactions, so if Revenue queries a figure you have a full audit trail rather than a box of paperwork.
Revenue requires you to keep VAT records and supporting documents for six years. Xero retains your VAT 3 returns along with the underlying transactions, so if Revenue queries a figure you have a full audit trail rather than a box of paperwork.
Small business guides for Ireland
Practical, plain-English guides on cash flow, invoicing, tax, and the day-to-day admin of running and growing your small business.
Explore our small business guides
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.