Liquidity ratios: formulas, examples and how to use them
Learn the current, quick and cash ratio formulas with HK$ examples, and ways to improve your liquidity.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Monday 26 October 2026
Table of contents
Key takeaways
- Calculate your current ratio monthly by dividing current assets by current liabilities. A common rule of thumb is 1.5 to 2.0, but it varies by industry.
- Use the quick ratio to assess your ability to pay bills in the short term without selling inventory, as it provides a stricter measure by excluding inventory and focusing only on cash, investments, and receivables.
- Improve low liquidity ratios by speeding up invoice collection, negotiating better payment terms with suppliers, and cutting non-essential spending to increase your available cash.
- Track liquidity trends over time rather than relying on single snapshots, as monthly monitoring helps you spot potential cash flow issues early and make informed decisions about spending and growth.
What are liquidity ratios?
Liquidity ratios measure your business's ability to pay short-term bills using cash or assets you can quickly convert to cash. These ratios help you understand whether you have enough money on hand to cover expenses over the next 12 months.
Cash flow is a common pressure point. In a 2025 QBE Hong Kong SME survey, about half of small and medium-sized businesses named finances, including cash flow and funding, as a challenge. Liquidity ratios give you a clear picture of your short-term financial health so you can make informed decisions about spending, growth, and investments.
There are three widely used liquidity ratios:
- Current ratio: compares all current assets to current liabilities
- Quick ratio: excludes inventory for a stricter measure
- Cash ratio: only counts cash and cash equivalents
When you use accounting software like Xero, the business performance dashboard shows key metrics such as debt ratios and gross profit. Here's how each ratio works.
Liquidity ratio formulas at a glance
Each formula divides a different group of assets by your current liabilities, from the broadest measure to the strictest:
- Current ratio = current assets ÷ current liabilities
- Quick ratio = (cash + cash equivalents + short-term investments + accounts receivable) ÷ current liabilities
- Cash ratio = (cash + cash equivalents) ÷ current liabilities
Why liquidity ratios matter for small businesses
Liquidity ratios help you avoid cash flow surprises and make confident financial decisions. Here's why they matter:
- Early warning signs: liquidity ratios help you spot cash flow pressure before bills fall due
- Smarter spending: knowing your ratios helps you decide when to invest, hire, or hold back
- Lender and investor confidence: lenders and investors may look at liquidity ratios, alongside other measures, when you apply for a loan or funding
- Benchmarking: compare your ratios to industry standards to see how your business stacks up
- Short-term planning: track your ability to cover salaries, Mandatory Provident Fund (MPF) contributions, bills, and loan payments over the next three to 12 months
Understanding your liquidity puts you in control. Without it, you risk spending too much, growing too fast, or missing opportunities to reinvest.
Current (working capital) ratio
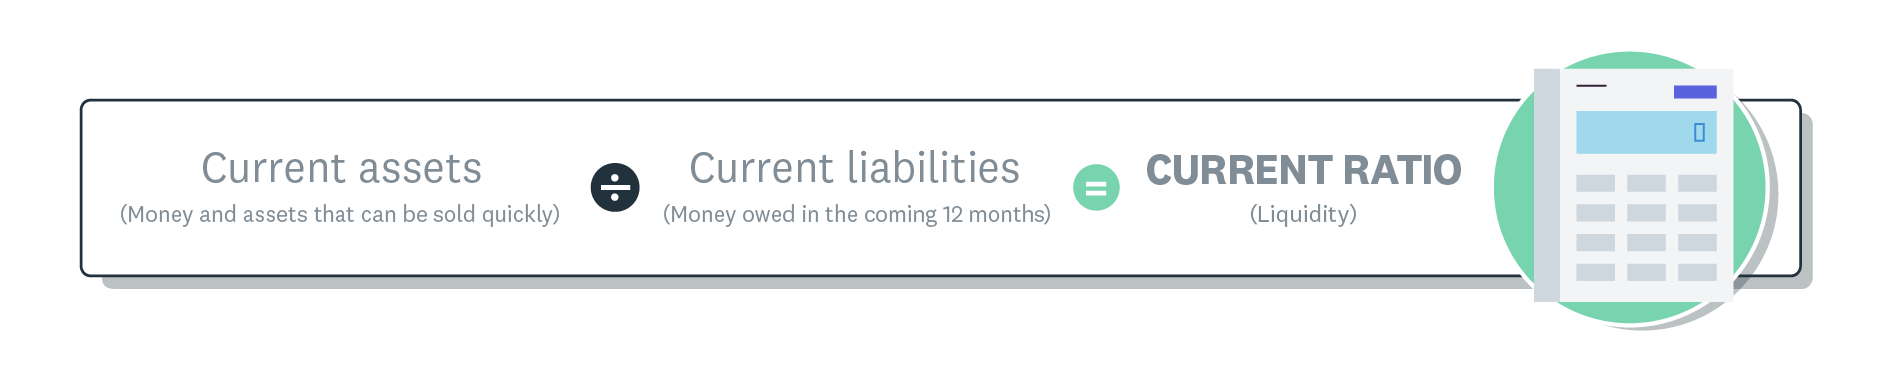
Current ratio liquidity formula
The current ratio (also called the working capital ratio) measures whether your total current assets can cover all current liabilities over the next 12 months. It's the most comprehensive liquidity ratio because it includes all short-term assets, including inventory. Accurately calculating inventory value can be a challenge, especially if you track inventory manually.
Use this formula: current assets ÷ current liabilities = current ratio.
Current ratio calculation
You can find the numbers for this calculation on your balance sheet. Look for your total current assets near the top of the report and total current liabilities near the middle. You can ignore your long-term assets or liabilities for this calculation. You can use our free balance sheet template.
Unlike the quick ratio, the current ratio includes your inventory. It accounts for the inventory based on its value on your balance sheet; typically, this means the cost you paid for the inventory, not the price you're going to sell it for. If your inventory is worth less than it cost (such as out-of-season holiday inventory), you should adjust its value on the balance sheet so you get a more accurate current ratio.
Generally, your current liabilities include all bills due within 12 months or less. But keep in mind that the way you do your bookkeeping affects how your liabilities appear on your balance sheet. For instance, if you don't record monthly bills until they go through your bank account they won't appear on your balance sheet, and you therefore won't be able to calculate this ratio easily. An accountant or the support team for your bookkeeping software can help you set up your books so you can calculate this ratio.
Current ratio example
Here's an example using a sample small business balance sheet. The quick ratio and cash ratio examples below use the same figures, so you can compare the results.
Current assets:
- Cash at bank: HK$300,000
- Cash equivalents (short-term deposits): HK$50,000
- Accounts receivable: HK$150,000
- Inventory: HK$250,000
- Prepaid expenses: HK$50,000
- Total current assets: HK$800,000
Your balance sheet groups these together, so you can find the total under "current assets."
Current liabilities include accounts payable, short-term bank loans, accrued salaries and MPF contributions, and profits tax payable:
- Accounts payable: HK$220,000
- Short-term bank loan: HK$100,000
- Accrued salaries and MPF contributions: HK$50,000
- Profits tax payable: HK$30,000
- Total current liabilities: HK$400,000
Example calculation: HK$800,000 ÷ HK$400,000 = 2.0 ratio
The lower your liabilities relative to assets, the higher your ratio and the stronger your ability to cover costs.
What's a good current ratio?
Any liquidity ratio above one is usually considered healthy. For the current ratio, 1.5 to 2.0 is a common rule of thumb, but a comfortable level varies by industry. A ratio in that range means you have HK$1.50 to HK$2.00 in current assets for every HK$1 of current liabilities.
Here's how to interpret your current ratio:
- 2.0 or higher: Strong liquidity, though very high ratios may indicate underused assets.
- 1.5 to 2.0: Common rule-of-thumb range, though norms differ between industries.
- Below 1.5: May indicate cash flow risk; a slow sales month could make it hard to pay bills.
- 3.0 or higher: Consider reinvesting excess cash into growth opportunities.
When to use the current ratio
You can use the current ratio to make decisions about your expenses and cash on hand. For instance, if you have a low working capital ratio, you may need to cut expenses. A low ratio also indicates that if you're buying equipment, you probably shouldn't use your cash on hand; consider a loan to spread the cost over time, instead.
On the other hand, if your ratio is 3.0 or higher, you may be missing out on opportunities; you probably have cash, investments, or inventory lying around that should be reinvested into growing the company.
While this ratio is useful, consider it alongside other financial metrics. If you run a seasonal business, use additional metrics alongside this ratio to assess your ability to cover short-term bills. This ratio looks at your current assets and liabilities; it doesn't take into account the long-term profitability of your business, the types of loans you have, or other factors that contribute to your business.
Strengths of the current ratio:
- Calculates easily with just two numbers from the balance sheet
- Allows business owners to quickly assess cash flow issues
- Helps assess your ability to cover expenses
- Identifies when you need to take out loans
- Identifies when you should think about expanding or investing
Limitations of the current ratio:
- Easily skewed when one of the two numbers changes for any reason
- Hides seasonal trends and doesn't reflect seasonal cash flow issues
- Only shows short-term financial health, not future challenges beyond 12 months
- Lacks insights into the company's long-term financial health
- Provides no insights into the business's loans and profitability
Quick (acid test) ratio
The quick ratio (also called the acid test ratio) measures whether you can pay short-term expenses without selling inventory or borrowing money. It includes cash, cash equivalents, short-term investments, and accounts receivable.
This ratio answers a critical question: do you have enough liquid assets to cover salaries, MPF contributions, bills, and loan payments in the short term?
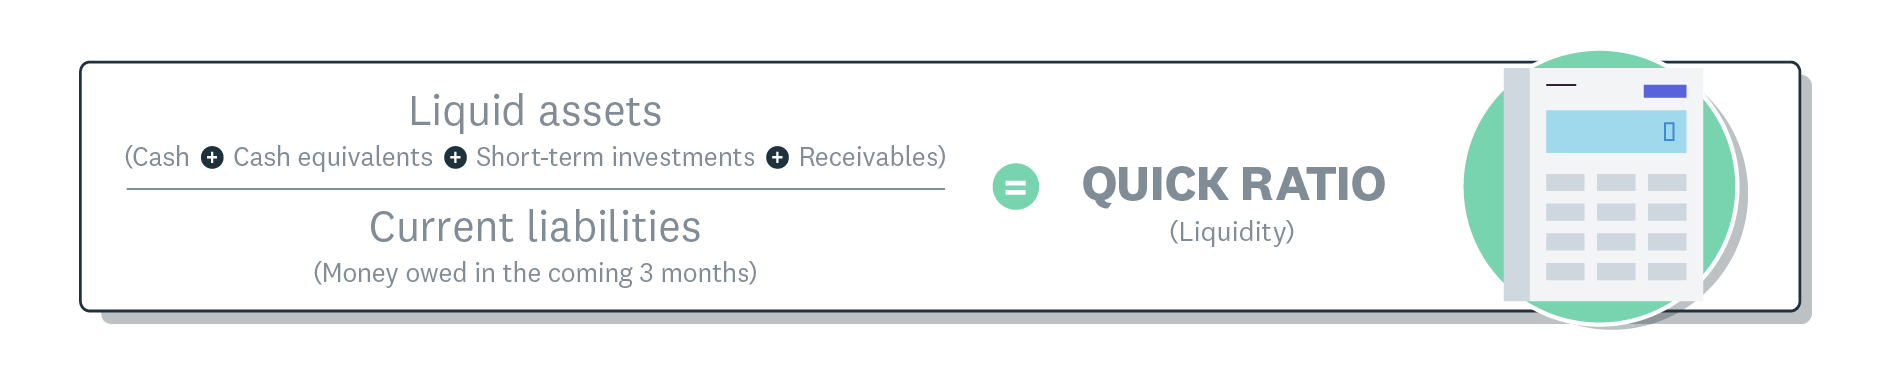
Quick ratio liquidity formula Version 1
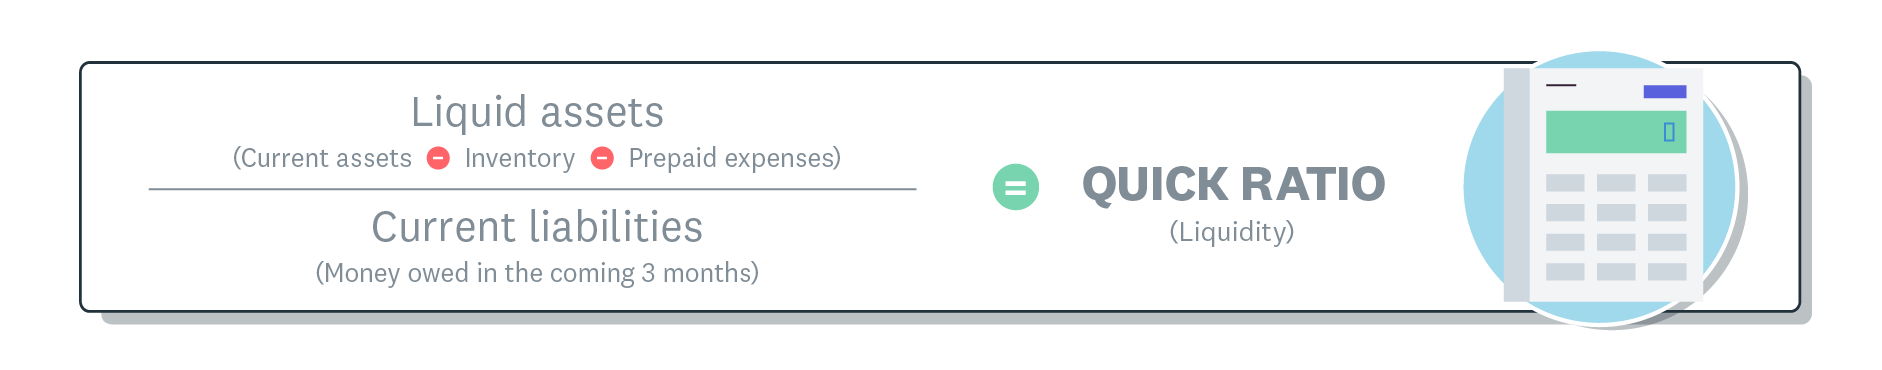
Quick ratio liquidity formula Version 2
Quick ratio calculation
Calculate the quick ratio using either method:
Method 1: (cash + cash equivalents + short-term investments + accounts receivable) ÷ current liabilities = quick ratio
Method 2: (current assets − inventory − prepaid expenses) ÷ current liabilities = quick ratio
Both methods produce the same result. Use whichever works best with the data you have available.
Quick ratio example
Using the same sample balance sheet, add cash at bank, cash equivalents, and accounts receivable, then divide by current liabilities: (HK$300,000 + HK$50,000 + HK$150,000) ÷ HK$400,000 = 1.25. Method 2 gives the same answer: HK$800,000 − HK$250,000 − HK$50,000 = HK$500,000, and HK$500,000 ÷ HK$400,000 = 1.25.
The quick ratio is also called an acid test ratio. Your balance sheet should have all the numbers you need to calculate this ratio.
What's a good quick ratio?
A quick ratio of 1.0 or higher is generally healthy. This means you have at least HK$1 in liquid assets for every HK$1 of short-term liabilities.
Here's how to interpret your quick ratio:
- 1.5 or higher: Strong liquidity; you have HK$1.50 for every HK$1 of expenses.
- 1.0: Adequate liquidity; you can cover upcoming bills.
- Below 1.0: Potential cash flow concerns; a ratio of 0.3 means only HK$0.30 for every HK$1 of bills.
When to use the quick ratio
Use this ratio to compare different companies if you're thinking about investing in a new company. You can also use it to compare your business's financial health to other companies in your industry, or to look at your business's liquidity over different periods.
You can use this ratio as a quick guide when you're thinking about taking on new expenses. For long-term health assessments, use additional metrics. For instance, you might be sitting on a stack of cash because you've had a great launch, but the quick ratio alone can't predict whether your product or service will sustain that cash flow. The quick ratio measures current liquidity only.
Strengths of the quick ratio:
- Calculates easily with readily available numbers
- Gives you a good idea of whether you can cover your expenses over the short term
- Helps you compare differences in cash flow between periods, so you can plan ahead for shortages
- Lets you see liquidity to determine if you can afford more expenses or investments
Limitations of the quick ratio:
- Excludes operating income from the calculation
- Only considers a short-term period
- Can be tricky to estimate if you have lots of marketable securities during times of economic instability
- May be inaccurate if you overstate the value of your accounts receivables; be realistic about the percentage of these bills that won't get paid
Cash ratio
The cash ratio measures whether you can cover short-term bills using only cash and cash equivalents. It's the strictest liquidity ratio because it excludes inventory, accounts receivable, and other assets.
Use this formula: cash and cash equivalents ÷ current liabilities = cash ratio. Some definitions also count short-term investments, so check which version a lender or benchmark uses.
This ratio tells you if you can pay salaries, MPF contributions, expenses, and loan payments over the next year without selling inventory or collecting receivables.
Cash ratio calculation
The cash ratio calculation includes:
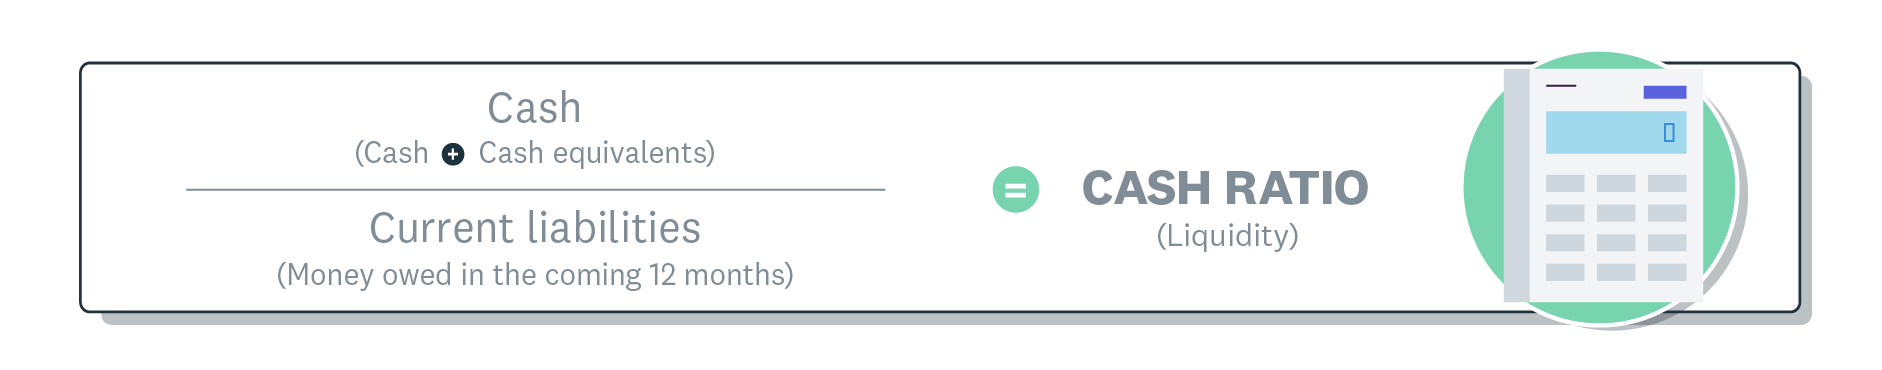
Cash ratio liquidity formula
- bank account balances: cash you can access immediately
- cash equivalents: securities you can convert to cash quickly
The cash ratio excludes:
- inventory: products you haven't sold yet
- accounts receivable: money customers owe you
- expected revenue: income you haven't received yet
Cash ratio example
Using the same sample balance sheet, add cash at bank (HK$300,000) and cash equivalents (HK$50,000) to get HK$350,000. Now find the current liabilities line on your balance sheet. This includes all of your upcoming expenses, like your loan payments, monthly bills, profits tax due, and salaries and MPF contributions.
With current liabilities of HK$400,000, your ratio is: HK$350,000 ÷ HK$400,000 = 0.88 (rounded from 0.875).
Side by side, the same business scores 2.0 on the current ratio, then 1.25 on the quick ratio, then 0.88 on the cash ratio, because each ratio counts fewer assets than the one before.
What's a good cash ratio?
A cash ratio of 1.0 or higher means you have enough cash to cover all short-term liabilities. A ratio below 1.0 suggests you may struggle to pay upcoming bills without selling assets or collecting receivables.
If your ratio is low, consider getting clients to pay invoices faster or reducing short-term expenses.
When to use the cash ratio
The cash ratio works best when you need a quick snapshot of your ability to pay bills with cash on hand. A low ratio after a major investment doesn't always signal trouble; it may simply reflect a strategic decision to deploy cash for growth.
Strengths of the cash ratio:
- Calculates quickly with just two numbers
- Provides immediate insight into cash availability
- Shows your most conservative ability to cover short-term expenses
Limitations of the cash ratio:
- Excludes operating income from the calculation
- Excludes supplier credit terms from the calculation
- Focuses only on short-term expenses, excluding long-term business challenges
Another metric for liquidity: Days sales outstanding
Days sales outstanding is another metric that may help you assess liquidity, depending on your industry and the way you operate your business.
Days sales outstanding (DSO) measures the average number of days it takes to collect payment after a sale. A lower DSO means faster cash collection and better liquidity.
Use this formula from the Association for Financial Professionals (AFP): (average accounts receivable ÷ net revenue) × 365 = DSO. Use net revenue for the trailing 12 months, so it matches the 365 days in the formula. DSO applies to credit sales, so count revenue from credit sales only; including cash sales would make your DSO look lower than it is.
What's a good DSO?
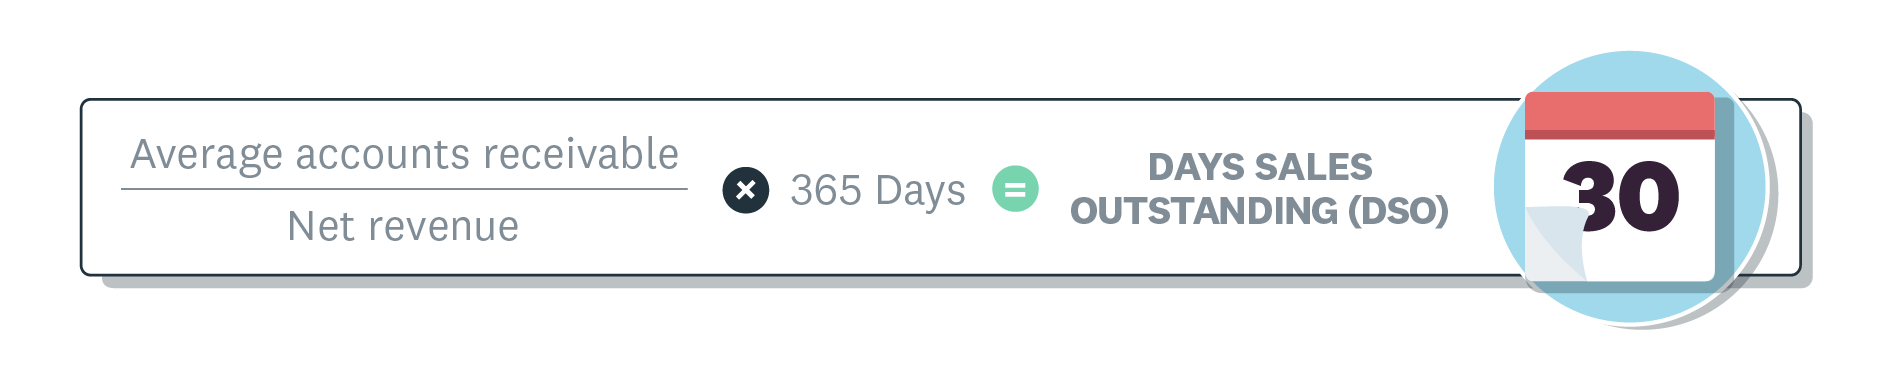
The days sales outstanding formula
This varies by industry, but as a benchmark, Upflow's data put the median DSO across industries at 56 days in 2024. Generally:
- Industry range: Upflow's figures run from about 42 days (clothing, accessories and home) to 105 days (office and facilities management).
- Common target: Many companies aim for a DSO under 45 days, according to the AFP.
- Longer terms: Some sectors like consulting have higher DSOs because 90-day payment terms are common.
- Collection issues: For most businesses, tighten payment terms or follow up on overdue invoices.
Using liquidity ratios
Here's how to get the most from your liquidity ratios:
- Calculate monthly: Check your ratios at the same time each month for consistency.
- Track trends: Look at how ratios change over time, not just single snapshots.
- Know the limitations: Each ratio has blind spots; use multiple ratios together.
- Consider the full picture: Analyse liquidity alongside efficiency and solvency ratios, such as the gearing ratio. Read up on liquidity vs solvency to see what each one measures.
- Get expert input: Work with an accountant or financial advisor for complex decisions.
How to improve liquidity
If your liquidity ratios are lower than you'd like, here are practical ways to improve them:
- Speed up invoicing:Use accounting software like Xero to send invoices faster and collect payments more efficiently.
- Collect receivables faster: Improve your accounts receivable by offering early payment discounts and sending automated reminders for overdue invoices.
- Shorten trade credit terms: Move customers from 60- or 90-day terms to 30 days or less to cut receivable days.
- Use invoice financing: Borrow against unpaid invoices to bring in cash before customers pay. See how invoice financing works before you apply.
- Negotiate better payment terms: Extend supplier payment windows where possible while avoiding late fees.
- Cut non-essential spending: Review operating costs and eliminate discretionary expenses.
- Optimise inventory levels:Manage your inventory by using just-in-time ordering to avoid tying up cash in excess stock.
- Sell unproductive assets: Convert unused equipment or inventory into cash.
- Grow revenue strategically:Increase sales by expanding your customer base without proportionally increasing operating costs.
- Refinance expensive debt: Consolidate high-interest short-term loans into lower-rate options.
Your accountant can help you prioritise these strategies. You may need to start the conversation and ask for proactive advice. Find experienced accountants and bookkeepers in the Xero advisor directory.
Track your liquidity with Xero
Understanding your liquidity ratios helps you make confident decisions about spending, growth, and cash flow management. With the right tools, tracking these metrics becomes part of your regular routine rather than a time-consuming task.
Xero's business performance dashboard shows key metrics such as debt ratios and gross profit, and Xero's reports give you the numbers to calculate all three liquidity ratios. Bank feeds bring your transactions into Xero automatically, so your cash position stays up to date.
Ready to take control of your cash flow? Get one month free and see your financial health in real time.
FAQs on liquidity ratios
Here are answers to common questions about liquidity ratios and how to use them.
What is a healthy liquidity ratio?
A current ratio above 1.0 is usually considered healthy, and 1.5–2.0 is a common rule of thumb that varies by industry. For the quick ratio, aim for 1.0 or higher.
What does a liquidity ratio of 2.5 mean?
A liquidity ratio of 2.5 means you have HK$2.50 in assets for every HK$1 of short-term liabilities. This indicates strong liquidity, though a very high ratio may suggest you could reinvest some cash into growth opportunities.
How often should I calculate my liquidity ratios?
Calculate your liquidity ratios monthly, ideally at the same point in your billing cycle each time. This helps you spot trends and catch potential cash flow issues early.
Can liquidity ratios be too high?
Yes. A very high ratio (above 3.0) may indicate you're holding too much cash or inventory that could be reinvested into the business. Balance liquidity with growth opportunities.
Which liquidity ratio is most important for small businesses?
The current ratio is most commonly used because it gives a comprehensive view of short-term financial health. However, the quick ratio provides a stricter measure if you want to exclude inventory from the calculation.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.