Profitability
Learn what profitability is, how to measure it with key ratios, and practical ways to improve your margins.
June 2023 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- Profitability shows the share of each euro of revenue you keep as profit, so it puts your earnings in context
- Gross, net and operating profit margins, plus return on assets (ROA) and return on equity (ROE), each show a different layer of performance
- A business can be profitable and short of cash at the same time, so it pays to track profit and cash flow side by side
- A 5% net margin is often seen as low and 20% as high, but your own trend over time is the most useful benchmark
What is profitability?
Profitability measures how efficiently your business turns revenue into profit, shown as a percentage. It tells you how much of each sale you keep after covering your costs.
Two profit figures sit behind it. Gross profit is revenue minus cost of goods sold (COGS). Net profit is gross profit minus all other expenses, including interest and tax.
The basic formula uses net profit.
- Profitability = (Net profit ÷ Revenue) × 100
Say your business earns €500,000 in revenue and keeps €75,000 as net profit. Your profitability, or net profit margin, is 15%. You keep 15 cents from every euro of sales.
The percentage puts your earnings in context. A profit of €1 million sounds impressive, but on €20 million of revenue it’s a 5% margin. A business making €200,000 on €1 million of revenue has a 20% margin.
Profit vs profitability
Profit is the euro amount your business keeps after expenses. Profitability is the share of revenue that becomes profit, so it shows how efficiently you earn it.
Here’s how two businesses compare.
- Business A earns €2 million in revenue and keeps €100,000 in profit. That’s a 5% margin.
- Business B earns €400,000 in revenue and keeps €80,000 in profit. That’s a 20% margin.
Business A makes more profit in euro terms, but Business B is four times as profitable. B keeps 20 cents from every euro, while A keeps 5 cents.
This difference shapes how you plan for growth. In a highly profitable business, each new sale adds more to your bottom line. Aim to grow total profit while holding or improving your margin.
Profitability vs cash flow
Profitability measures what you earn over a period, while cash flow tracks the money moving in and out of your bank account. The two often tell different stories, because sales and costs rarely line up with payments.
A profitable business can still run short of cash. If you invoice €60,000 in March on 60-day terms, the profit shows in March but the cash arrives in May. A €40,000 van purchase drains your account at once, while your accounts spread the cost over several years as depreciation.
The reverse happens too. A €50,000 bank loan lifts your bank balance, but it isn’t revenue, so a loan-funded business can look cash-rich while making a loss. Watching both numbers together shows whether your margins are turning into cash you can use.
Why profitability matters
Profitability shows whether your business model can keep going over the long term. A profitable business can reinvest in growth and build a cash buffer for quieter months.
Here’s what regular tracking does for your business.
- Shows how efficiently you operate, since a higher margin means you need less revenue to reach your profit goals
- Guides better decisions on pricing and hiring, because you can see what’s driving your returns
- Makes your business more attractive to lenders and investors, who check your margins before offering finance
- Gives you early warning when margins shrink while revenue stays flat, so you can act on costs quickly
Factors that affect profitability
Several factors shape how profitable your business is, and you can influence most of them. Knowing how each one works helps you decide where to focus.
Pricing strategy
Your prices set the ceiling for your margins. Price too low and you may win customers but struggle to cover costs; price too high and sales may slow.
Review your prices regularly against your costs and the value you deliver. Your pricing model matters too: a monthly subscription spreads revenue more evenly than one-off project fees.
Cost of goods sold
The cost of producing or purchasing what you sell has one of the biggest effects on profitability. Negotiating better supplier terms or buying in bulk can lift your gross margin.
Operating expenses
Rent, utilities, insurance, marketing and admin all reduce your profit. Audit your overheads regularly to find costs you can reduce or drop without affecting quality.
Customer demand and sales volume
Higher sales volume can improve profitability when your fixed costs stay steady. Heavy discounting to chase volume can shrink margins, though, so check whether extra sales are adding to your bottom line.
Competition
Competitive pressure can push you to lower prices or spend more on marketing. Standing out through better service or specialist expertise helps protect your margins.
Productivity and efficiency
The more efficiently your team works, the more output you get for each euro spent on labour. Training and software that automates repetitive tasks both help you get more from the same hours.
Team growth and staff costs
Hiring often comes before the revenue it’s meant to support, so margins can dip as your team grows. Staff costs include wages plus employer Pay Related Social Insurance (PRSI), so budget for the full amount.
Take a hypothetical business earning €400,000 a year, with staff costs of €100,000, or 25% of revenue. It hires two people at a combined €90,000 and revenue rises to €480,000. Staff costs now take about 40% of revenue, so net margin falls unless the new hires lift sales further.
Scale
As you grow, you may benefit from economies of scale by spreading fixed costs across more revenue. Growth also brings new costs, such as larger premises, so track whether scaling is lifting your margins.
How to measure profitability
There are several profitability ratios, and each shows a different side of your financial performance. You’ll find the figures you need on your profit and loss statement and balance sheet.
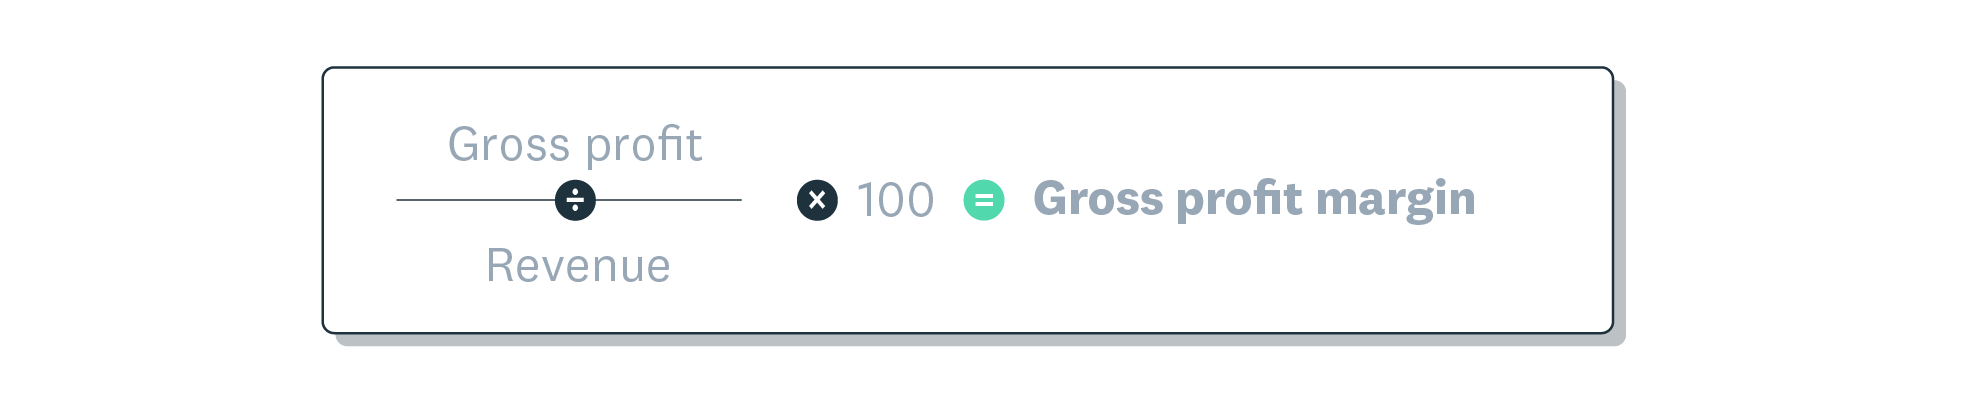
Gross profit margin
Gross profit margin shows the percentage of revenue left after you subtract the direct costs of what you sell. Calculate it with this formula.
- Gross profit margin = ((Revenue minus COGS) ÷ Revenue) × 100
If your business earns €300,000 in revenue and COGS is €180,000, your gross profit is €120,000. Your gross profit margin is (€120,000 ÷ €300,000) × 100 = 40%. You keep 40 cents from every euro of sales before operating expenses.
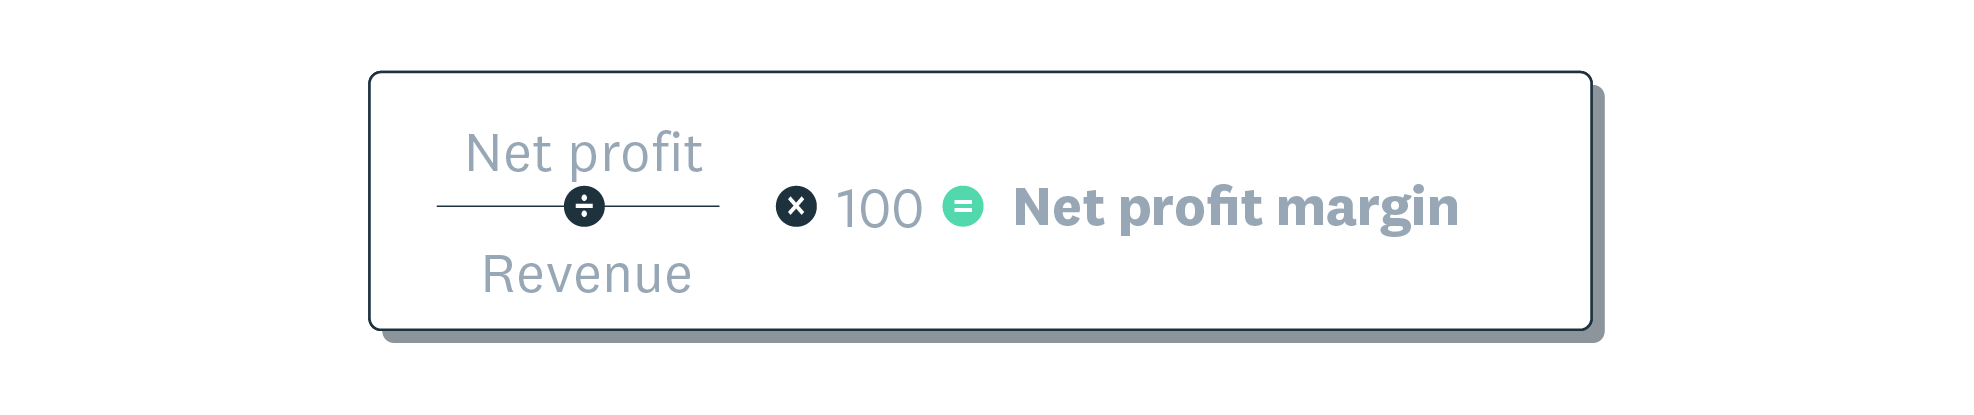
Net profit margin
Net profit margin shows the percentage of revenue left after all expenses, including COGS, operating costs, interest and tax. It’s the fullest view of your profitability. Use this formula to work it out.
- Net profit margin = (Net profit ÷ Revenue) × 100
Using the same €300,000 of revenue, say COGS is €180,000, operating expenses are €60,000 and interest and tax come to €15,000. Your net profit is €45,000. Your net profit margin is (€45,000 ÷ €300,000) × 100 = 15%.
Operating profit margin
Operating profit margin shows the percentage of revenue left after COGS and operating expenses, but before interest and tax. It isolates how well your core operations perform. Here’s how to calculate it.
- Operating profit margin = (Operating profit ÷ Revenue) × 100
With revenue of €300,000, COGS of €180,000 and operating expenses of €60,000, your operating profit is €60,000. Your operating profit margin is (€60,000 ÷ €300,000) × 100 = 20%.
Return on assets (ROA)
Return on assets shows how well your business uses its assets to generate profit. It helps you judge whether spending on equipment or stock is paying off. The formula divides profit by assets.
- ROA = (Net profit ÷ Total assets) × 100
If your net profit is €45,000 and your total assets are €500,000, your ROA is (€45,000 ÷ €500,000) × 100 = 9%. Every euro of assets generates 9 cents of profit.
Return on equity (ROE)
Return on equity measures profit against the money the owners have invested in the business. It’s useful for comparing your business’s return with other places you could put your money. The formula divides profit by equity.
- ROE = (Net profit ÷ Owner’s equity) × 100
If your net profit is €45,000 and your owner’s equity is €200,000, your ROE is (€45,000 ÷ €200,000) × 100 = 22.5%. The business returns 22.5% on the money invested in it.
EBITDA
Earnings before interest, taxes, depreciation and amortisation (EBITDA) adds those costs back to net profit to show what your core operations earn. It’s common in larger businesses, and it helps when you compare companies with different financing or asset structures.
- EBITDA = Net profit + Interest + Taxes + Depreciation + Amortisation
Suppose €10,000 of the earlier €60,000 in operating expenses is depreciation and amortisation. Add that and the €15,000 of interest and tax to your €45,000 net profit. Your EBITDA is €70,000.
Compare your ratios over time
A single ratio is a snapshot, so compare each one with the same period in prior years. Measuring profitability over several years shows whether your business is becoming more or less efficient.
Watch the gap between gross and net margin, because it shows how well you control expenses. Say your gross margin holds at 40% for two years, but net margin drops from 15% to 11%. The gap has widened from 25 to 29 percentage points, so overheads are growing faster than revenue.
What’s a good level of profitability?
A good profit margin depends on your industry and business model. As a rough guide, Brex’s profit margin rule of thumb treats a 5% net margin as low, 10% as healthy and 20% as high.
Industry averages vary widely. The NYU Stern margins dataset from Aswath Damodaran, updated January 2026, covers 5,994 US-listed firms. Across the total market, the average gross margin is 37.76% and the average net margin is 9.74%.
Retail runs much thinner, with a net margin of 5.61% for Retail (General) and 1.32% for Retail (Grocery and Food). These are US-listed company averages, so Irish small business margins will differ.
The best benchmark is your own trend. If your profit margin improves year on year, you’re moving in the right direction. Very high margins can sometimes slow sales, so balance margin with steady demand.
How to improve profitability
You improve profitability by raising revenue, cutting costs or both. These strategies suit most small businesses.
Review your pricing
If you haven’t changed your prices recently, you may be undercharging. Check your costs and what competitors charge, then set prices that reflect the value you deliver.
Small rises add up. Using the earlier example, a 5% price rise on €300,000 of revenue adds €15,000 to operating profit if sales volume holds. That lifts your operating margin from 20% to about 24%.
Cut unnecessary costs
Go through your expenses line by line. Look for subscriptions you don’t use and suppliers you could renegotiate with.
Rank products and customers by profit
Some products and customers earn much more than others once you count the time and costs they take. Rank each by gross profit, then focus your sales effort on the top earners.
Look closely at the bottom of the list. A customer who asks for frequent changes or pays late may cost more to serve than they bring in. Consider raising prices for that work or phasing it out.
Automate repetitive tasks
Manual admin takes time you could spend on paid work. Software that handles invoicing, bank reconciliation, expense tracking and payment reminders frees you up for tasks that bring in revenue.
Track projects against budgets
In service businesses, scope creep can quietly erode margins. Set a budget for each project and track actual costs against it. When clients ask for extra work, agree a change order before you start.
Monitor your margins regularly
Review your profit and loss reports monthly or quarterly. Regular checks help you spot trends early and act while issues are still small.
Keep track of your profitability with Xero
Profitability tells you how much of every euro you keep, and regular tracking helps you act before small issues grow. That’s easier when your numbers are current and in one place.
Xero accounting software brings your revenue and expenses together in financial reports you can run at any time. Automated bank feeds keep the figures up to date, and Xero Analytics helps you spot margin trends and project your cash position.
See where your margins stand today when you try Xero and get one month free.
FAQs on profitability
Get quick answers to common questions about profitability.
Can a business be profitable but still fail?
Yes. A business with strong margins can still fail if it runs out of cash to pay bills or loan repayments when they fall due.
How does corporation tax affect your net profitability in Ireland?
Irish companies pay corporation tax at 12.5% on trading income and 25% on non-trading income, such as rental or investment income. Tax comes off before net profit, so the same pre-tax profit gives a lower net margin when more of it is non-trading income.
How often should you check your profitability?
Review your gross and net margins monthly, and look at ROA and ROE quarterly or at year end. Check again after any big change, such as a price rise or a new hire.
When should you seek professional advice about profitability?
Speak to an accountant or bookkeeper if margins fall for two quarters running and you can’t find the cause. The Xero Advisor Directory lists certified advisers near you.
Related terms
Learn more about profitability
/www.xero.com/ie/guides/track-business-expenses/">How to track your business expenses
Handy resources
Advisor directory
You can search for experts in our advisor directory
P&L template
Download a P&L template to help track your profitability
Instant profitability reports
Generate key reports at the click of a mouse with Xero accounting software
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.