Accumulated depreciation: definition and calculation
Learn what accumulated depreciation is, how to calculate it and how IRD allowances apply in Hong Kong.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Wednesday 21 October 2026
Table of contents
Key takeaways
- Calculate straight-line accumulated depreciation by dividing cost minus salvage value by useful life, then multiplying by the years you've owned the asset
- Record accumulated depreciation as a contra asset on your balance sheet, which reduces book value and shows what your assets are worth today
- Claim Inland Revenue Department (IRD) depreciation allowances for Hong Kong Profits Tax, because accounting depreciation is added back in your tax computation
- Track accumulated depreciation to plan asset replacements and maintenance schedules more effectively
What is accumulated depreciation?
Accumulated depreciation is the total depreciation of an asset since you purchased it. The accounting principles are outlined in International Accounting Standard (IAS) 16 Property, Plant and Equipment. This standard helps show how much value an asset has lost over time due to wear, use or age.
Tracking accumulated depreciation lets you record the true value of your assets on financial statements. This value, known as book value, reflects what the asset is realistically worth today. Book value equals asset cost minus accumulated depreciation.
Here's how that works for two common business assets.
- Office furniture costs HK$5,000 and depreciates by HK$1,000 each year, so after three years accumulated depreciation totals HK$3,000 and book value is HK$2,000
- Machinery costs HK$25,000 and depreciates by HK$2,500 each year, so after six years accumulated depreciation totals HK$15,000 and book value is HK$10,000
Depreciation vs accumulated depreciation
Depreciation is a recurring expense that shows the decrease in an asset's value over a set period, such as a month or a year. Accumulated depreciation is the running total of all depreciation expenses recorded for an asset since you bought it.
Each time you record a depreciation expense, accumulated depreciation increases by that amount.
Is accumulated depreciation an asset or a liability?
Knowing where accumulated depreciation sits on your balance sheet supports accurate financial reporting. Accumulated depreciation is neither an asset nor a liability. It's classified as a contra asset account, which offsets the original value of assets on your balance sheet.
Unlike liabilities (amounts your business owes), accumulated depreciation isn't a debt to repay. It reflects the reduction of an asset's book value over time.
You record a contra asset alongside your other assets, but it always carries a negative value. This gives you a more realistic view of what each asset is worth today.
How to calculate accumulated depreciation
Use the straight-line method, a common approach to calculating accumulated depreciation. Most companies prefer straight-line depreciation for reporting purposes, as it tends to result in higher net income during an asset's early years.
The straight-line depreciation calculation
Annual depreciation expense = (cost of asset − salvage value) ÷ useful life. In this formula:
- cost of asset is the original purchase price
- salvage value is the estimated resale or scrap value
- useful life is the estimated number of years the asset will function
Calculate straight-line depreciation
Say an asset costs HK$1,000, has a useful life of five years and has a salvage value of HK$100. Follow these steps to work out its accumulated depreciation and book value.
- Calculate the annual depreciation expense: (HK$1,000 − HK$100) ÷ 5 = HK$180
- List accumulated depreciation by year: HK$180 in year one, HK$360 in year two, HK$540 in year three, HK$720 in year four, HK$900 in year five
- Subtract accumulated depreciation from the initial cost to find book value; after three years, that's HK$1,000 − HK$540 = HK$460
How does accumulated depreciation affect financial statements?
Depreciation shows up on your balance sheet, income statement and cash flow statement in different ways. Hong Kong Profits Tax also treats it differently from your accounts.
Accumulated depreciation on the balance sheet
Accumulated depreciation reduces an asset's book value on the balance sheet. The balance sheet lists the original cost, and accumulated depreciation adjusts it downward.
Accumulated depreciation on the income statement
Depreciation expense appears on your income statement and reduces reported profit. As a non-cash expense, it lowers reported profits without any cash leaving the business. For example, a HK$10 increase in depreciation means operating income would decrease by HK$10.
Each period's expense adds to the accumulated total. For Hong Kong Profits Tax, your tax relief comes from IRD depreciation allowances instead of this book figure.
Accumulated depreciation on the cash flow statement
You add depreciation back to net income on the cash flow statement because no cash leaves the business.
Depreciation allowances for Hong Kong Profits Tax
For Profits Tax, you adjust accounting profit by adding back book depreciation and claiming tax depreciation allowances instead, as PwC Tax Summaries explains. The IRD's Profits Tax guidance sets out the main allowances, which include:
- a 60% initial allowance for plant and machinery in the purchase year, then 10%, 20% or 30% annual allowances on each pool's reducing value
- a 20% initial allowance plus a 4% annual allowance for industrial buildings
- a 4% annual allowance for commercial buildings
Here's how that works for a machine. If you buy a HK$100,000 machine, you get a HK$60,000 initial allowance and HK$40,000 goes into the pool. At a 20% rate, the annual allowance is HK$8,000.
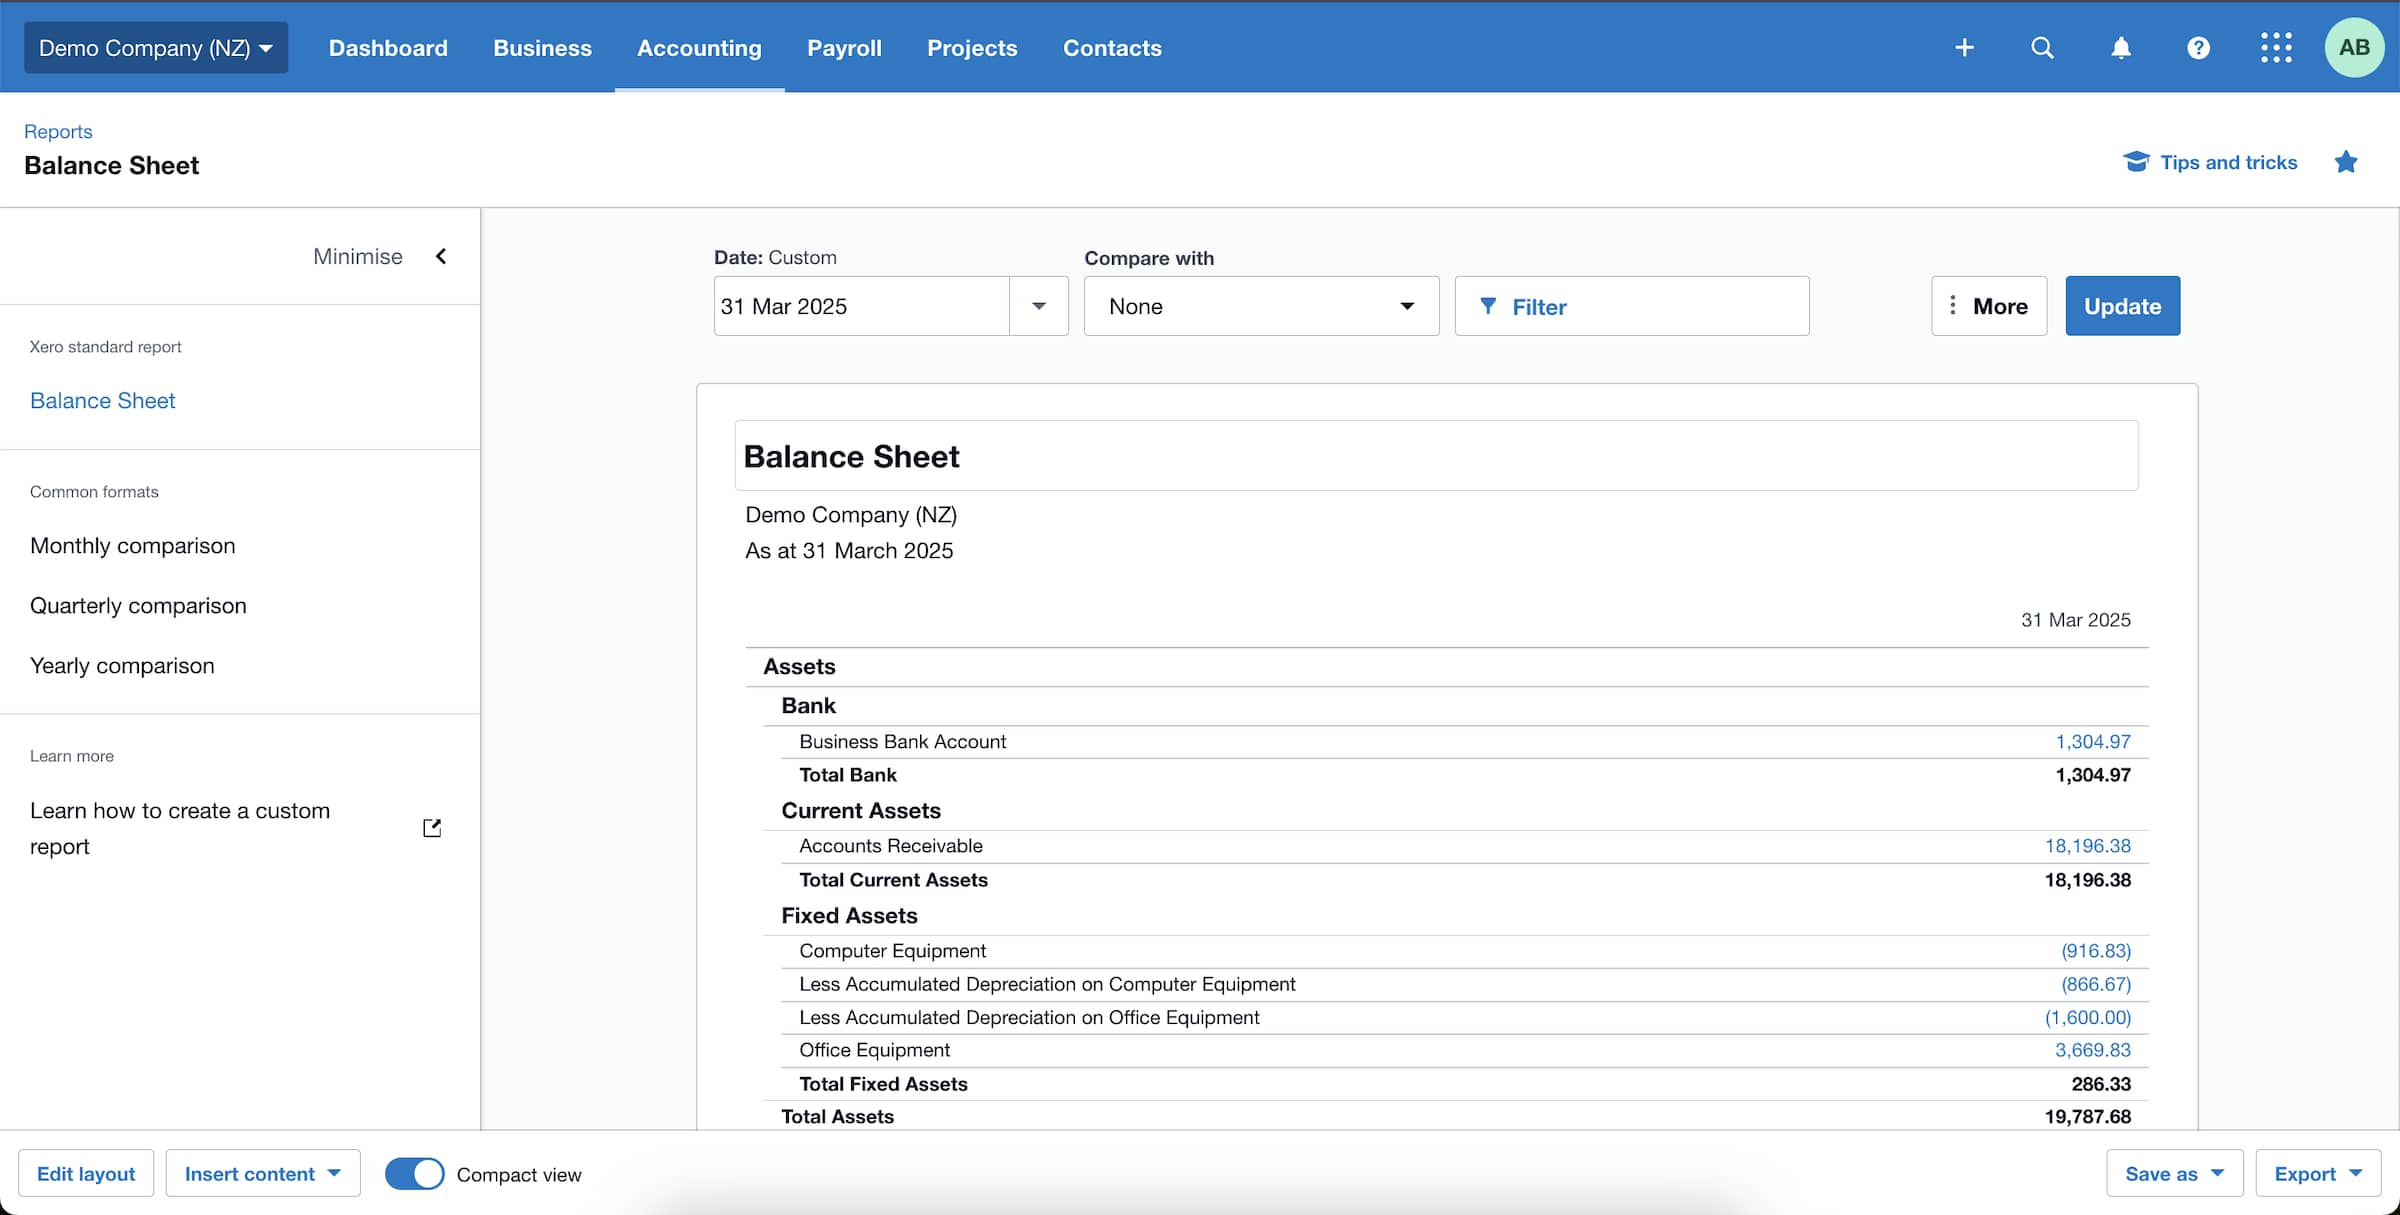
Example balance sheet for accumulated depreciation
This balance sheet example shows how accumulated depreciation reduces the net book value of assets. The contra asset offsets each asset's original cost.
- Equipment costing HK$200,000, less HK$60,000 accumulated depreciation, has a net book value of HK$140,000
- Vehicles costing HK$300,000, less HK$120,000 accumulated depreciation, have a net book value of HK$180,000
- Buildings costing HK$1,500,000, less HK$300,000 accumulated depreciation, have a net book value of HK$1,200,000
- Total assets costing HK$2,000,000, less HK$480,000 accumulated depreciation, have a net book value of HK$1,520,000
Why understanding accumulated depreciation matters for your business
Tracking accumulated depreciation gives you a clearer picture of what your assets are worth. It helps you:
- plan replacements, upgrades and maintenance by tracking how asset values change
- claim IRD depreciation allowances in your Profits Tax computation, where they replace book depreciation
- get financing more easily by presenting accurate book values to lenders and investors
Simplify depreciation tracking with Xero
Xero takes care of the depreciation calculations for you. With Xero, you can create detailed depreciation schedules, track fixed asset values and make your financial reporting more accurate.
As your business grows, Xero scales with you. Start tracking your assets in Xero and get one month free.
FAQs on accumulated depreciation
Here are quick answers to common questions about accumulated depreciation.
How does accumulated depreciation affect cash flow?
Accumulated depreciation is a non-cash item, so no money leaves your business when you record it. In Hong Kong, any tax relief comes through IRD depreciation allowances instead of the depreciation in your accounts.
What happens to an asset's accumulated depreciation when you sell it?
When you sell an asset, you remove its accumulated depreciation from your books along with the asset. Compare the asset's book value with the sale price to work out your gain or loss.
Do I record accumulated depreciation as a debit or a credit?
You record accumulated depreciation as a credit. As a contra asset, its credit balance offsets the asset's debit balance.
Is accumulated depreciation a current liability?
No. Current liabilities are amounts due within 12 months, while accumulated depreciation is a contra asset that reduces an asset's book value.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.