Quick ratio
Learn how to calculate the quick ratio, what a good result looks like and how to improve it.
February 2024 | Published by Xero
Published Wednesday 30 September 2026
Table of contents
Key takeaways
- The quick ratio shows whether your most liquid assets can cover your current liabilities without selling any stock
- A quick ratio of 1.0 or higher usually means you can meet short-term bills, and a lower figure is a prompt to check cash flow
- The quick ratio leaves out inventory and prepaid expenses, so it gives a stricter view of liquidity than the current ratio
- Count payroll taxes owed to Revenue and pension contributions, including My Future Fund auto-enrolment, in your current liabilities for an accurate figure
What is the quick ratio?
The quick ratio divides your quick assets by your current liabilities to show whether you could pay your short-term debts right now. Quick assets are cash and anything you can turn into cash within about 90 days.
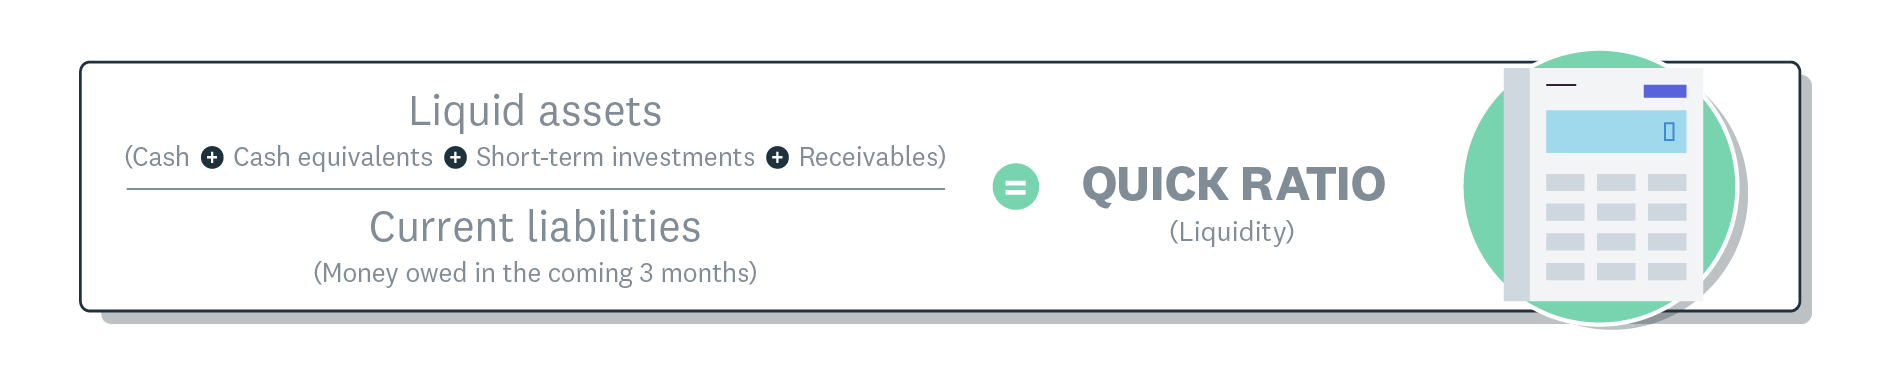
Quick ratio formula Version 1.
You'll also see it called the acid-test ratio. It strips out slower-moving assets such as inventory and prepaid expenses, so the result reflects only money you can reach quickly.
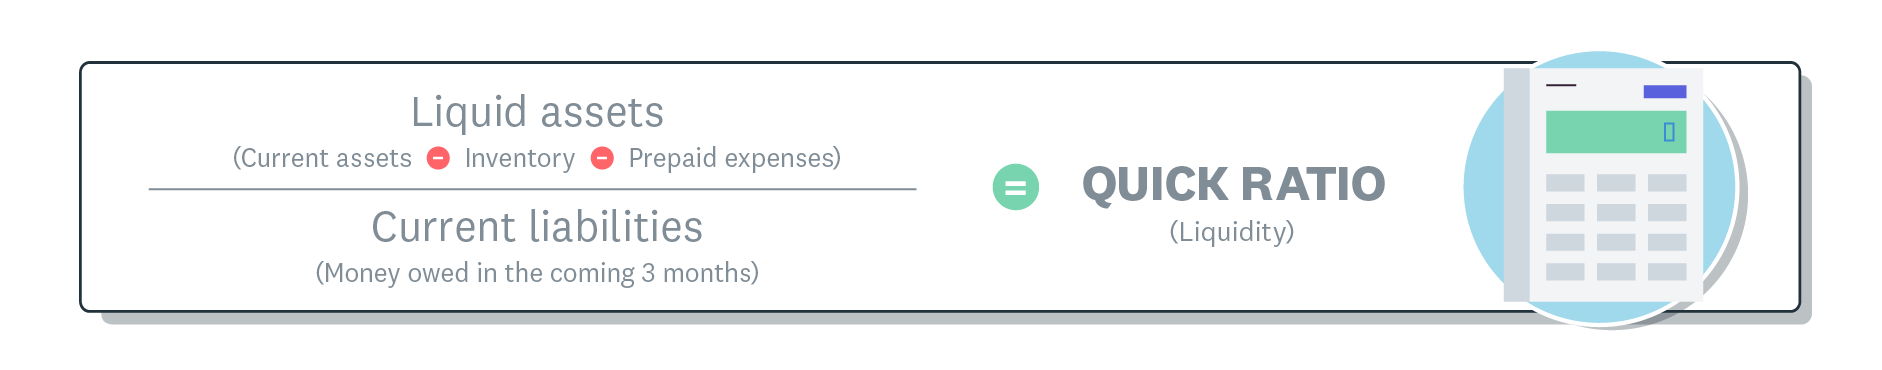
Quick ratio formula Version 2.
Picture a €15,000 equipment repair bill landing on your desk this month. The quick ratio tells you whether your bank balance and what customers owe you could cover it, along with your other bills.
The quick ratio measures liquidity, which is your ability to meet bills over the next 12 months. Solvency looks at long-term debts instead, and this guide to liquidity and solvency explains how the two connect.
How to calculate the quick ratio
To calculate the quick ratio, divide your quick assets by your current liabilities. You can write the formula in two ways.
Formula 1: Quick ratio = (cash + marketable securities + net accounts receivable) / current liabilities
Formula 2: Quick ratio = (current assets − inventory − prepaid expenses) / current liabilities
Both formulas give the same answer. Formula 1 adds up your liquid assets directly, while Formula 2 starts with total current assets and subtracts the items that take longer to convert.
Follow these steps to work out your own quick ratio:
- Find your quick assets on your balance sheet, or set them out using a ready-made balance sheet template
- Add up your current liabilities, meaning everything you owe within the next 12 months
- Divide your quick assets by your current liabilities
- Compare the result with 1.0 and with your own figures from previous months
Worked example
Here's how the maths works for a business with these figures. Suppose your balance sheet shows:
- €50,000 in cash
- €10,000 in marketable securities
- €40,000 in net accounts receivable
- €30,000 in inventory
- €80,000 in current liabilities
Using Formula 1: Quick ratio = (€50,000 + €10,000 + €40,000) / €80,000 = €100,000 / €80,000 = 1.25
The €30,000 of inventory stays out of the sum, so it has no effect on the result. A quick ratio of 1.25 means you have €1.25 in liquid assets for every €1 of short-term debt. That leaves a buffer after every current bill is paid.
Components of the quick ratio
The quick ratio uses two groups of figures from your balance sheet: quick assets and current liabilities. Knowing what belongs in each group keeps your result accurate.
Assets included
Quick assets are the ones you can turn into cash within about 90 days. They include:
- cash in your business bank accounts, including petty cash
- cash equivalents such as term deposits, which usually mature within three months under the International Accounting Standard 7 (IAS 7) definition
- marketable securities, such as listed shares or government bonds you can sell quickly
- net accounts receivable, meaning money customers owe you minus debts you don't expect to collect
Liabilities included
Your balance sheet splits liabilities into current and non-current, as the IAS 1 presentation rules require. Current liabilities are the obligations due within 12 months, and for an Irish business they typically include:
- accounts payable, meaning bills you owe suppliers
- short-term loans and overdrafts
- credit card balances
- wages and the payroll taxes you owe Revenue: Pay As You Earn (PAYE), Universal Social Charge (USC) and Pay Related Social Insurance (PRSI)
- value-added tax (VAT) and other tax due within the year, such as corporation tax
- pension contributions, including My Future Fund auto-enrolment, where employers match the 1.5% of gross pay that eligible employees contribute in 2026
- the current portion of any long-term debt
What's excluded
The quick ratio leaves out assets that take longer to turn into cash. Inventory is excluded because selling stock can take weeks or months, and a rushed sale may bring in less than full value. Prepaid expenses, such as insurance or rent paid in advance, are excluded because you can't convert them back into cash.
What is a good quick ratio?
A good quick ratio is 1.0 or higher, the benchmark the Corporate Finance Institute (CFI) uses in its explanation of the quick ratio formula. At 1.0, you have €1 in liquid assets for every €1 of short-term debt.
Here's how to read different results:
- Below 1.0: your quick assets fall short of your current liabilities, so you may need stock sales or new finance to pay on time.
- Exactly 1.0: you can cover your current liabilities with nothing left over.
- Between 1.0 and 1.5: you can cover short-term bills with a buffer, and CFI describes this range as the sweet spot for many businesses.
- Very high: your liquidity is strong, and some of that cash could go towards growing your business.
A quick ratio of 0.75 means you have €0.75 in quick assets for every €1 you owe in the short term. You'd need to find the remaining €0.25 per euro from stock sales or new finance. It's a signal to review your collections and payment terms.
A quick ratio of 1.5 means you have €1.50 for every €1 of current liabilities. That covers every short-term bill with a 50% cushion for a late customer payment or an unexpected cost.
How the quick ratio varies by industry
The quick ratio varies by industry because businesses that hold a lot of stock naturally report lower figures than service businesses. Retail shops and manufacturers put a large share of their current assets into stock, which the quick ratio leaves out. Hospitality businesses such as cafés and restaurants carry food and drink stock too.
A consultancy or design studio holds little stock, so most of its current assets are cash and receivables. Its quick ratio usually sits close to its current ratio.
Your own trend tells you more than any single industry figure. Track your ratio each month alongside your working capital to see whether liquidity is improving. When you compare with other businesses, pick ones with a similar stock profile and seasonal pattern.
What the quick ratio means for your business
Your quick ratio tells you whether you could pay all your short-term debts today using only your most accessible assets. Lenders and investors often check it before offering credit or investing in your business.
A ratio that stays above 1.0 shows you manage cash well and can meet obligations without depending on stock sales. A dip below 1.0 is an early warning to investigate. It may point to generous credit terms for customers or heavy short-term borrowing.
Checking the ratio often gives you early sight of cash flow pressure. You can then act before a shortfall becomes urgent, for example by chasing overdue invoices or agreeing longer payment terms with suppliers.
Pros and limitations of the quick ratio
The quick ratio's main strengths are speed and caution, while its limitations come from being a single snapshot. The quick ratio has two clear advantages:
- it's fast, because you can calculate it in minutes from your balance sheet
- it's conservative, because it only counts assets you can turn into cash quickly
Keep these limitations in mind when you read the result:
- it shows one moment in time, so a large payment the next day can change the picture
- it assumes customers will pay what they owe, even though some debts may run late
- it treats money arriving in 60 days the same as cash in the bank, even when a supplier bill is due this week
- it varies by industry, so comparisons work best between similar businesses
Quick ratio vs current ratio
The quick ratio counts only your most liquid assets, while the current ratio counts all current assets, including stock and prepaid expenses. The current ratio formula is:
Current ratio = current assets / current liabilities
Because it leaves out inventory, the quick ratio is a better guide to paying immediate obligations than the current ratio. If your business holds a lot of stock, the gap between the two ratios can be wide. A high current ratio paired with a low quick ratio suggests much of your liquidity is tied up in stock.
Use the current ratio for a broad view of short-term health. Use the quick ratio when you want a cautious check on whether you can pay debts quickly.
Other liquidity ratios to use alongside the quick ratio
The cash ratio and the operating cash flow ratio fill gaps the quick ratio leaves. You'll find more measures in this overview of liquidity ratios.
Cash ratio
The cash ratio is the strictest liquidity test because it counts only cash and cash equivalents. The formula is:
Cash ratio = (cash + cash equivalents) / current liabilities
It leaves out receivables and marketable securities, so it shows what you could pay today with money already in the bank.
Operating cash flow ratio
The operating cash flow ratio compares the cash your day-to-day trading brings in with what you owe in the short term. The formula is:
Operating cash flow ratio = operating cash flow / current liabilities
Because it uses cash generated over a period, it balances out the single-day snapshot the quick ratio gives you.
How to improve your quick ratio
You can improve your quick ratio by increasing your liquid assets or reducing your short-term liabilities. These five steps help with both.
1. Speed up your receivables
The sooner customers pay, the more cash you have on hand. Send invoices as soon as you finish a job and set clear payment terms. Offering online payment options shortens the gap between invoicing and payment.
2. Reduce short-term liabilities
Pay down short-term debt where you can, or renegotiate payment terms with suppliers. Moving a short-term loan into a longer-term arrangement takes it out of current liabilities, which lifts your ratio.
3. Build your cash reserves
Set aside part of your revenue in a dedicated account to create a buffer. A cash flow forecast shows how much you can put away each month while still covering upcoming bills.
4. Manage inventory more efficiently
Inventory sits outside the quick ratio, but excess stock ties up cash you could hold instead. Review stock levels regularly and order in line with actual demand.
5. Monitor your ratio regularly
Check your quick ratio monthly or quarterly so you can spot trends early and adjust before a dip becomes a problem. Real-time financial reports give you the figures whenever you need them.
Simplify your financial reporting with Xero
Xero keeps the figures behind your quick ratio up to date, so you can check your liquidity whenever you need to. Automatic bank feeds and customisable reports give you a real-time view of what you own and what you owe.
You can pull up your balance sheet at any time and track your ratio without manual sums. Sign up today to get one month free and see your financial position in one place.
FAQs on quick ratio
These answers cover common questions about the quick ratio that go beyond the basics.
Why is it called the quick ratio?
It's named after quick assets, the ones you can turn into cash fast. The other name, acid-test ratio, comes from the old practice of using acid to test whether metal was real gold.
Is a higher quick ratio always better?
A high ratio is only as strong as the assets behind it, so check whether it comes from cash or from slow-paying receivables. A large receivables balance can lift the ratio even when there's little cash in the bank.
Why is inventory excluded from the quick ratio?
Stock usually has to be sold and then paid for before it becomes cash, which can take longer than the ratio's 90-day window. Its sale value is also uncertain, so leaving it out keeps the ratio conservative.
Can a business have a high current ratio but a low quick ratio?
Yes, and it's common for retailers stocking up before Christmas, when current assets rise but most of the increase is stock. The quick ratio usually recovers once that stock sells and customers pay.
Who uses the quick ratio?
Suppliers may check it before offering you trade credit, and your accountant may review it when preparing your year-end accounts.
Related terms
Learn more about quick ratio
Handy resources
Advisor directory
You can search for experts in our advisor directory.
Balance sheet template
See where and how assets and liabilities are reported.
Push-button liquidity reporting
Check your current ratio whenever you like with Xero’s accounting dashboard.
Disclaimer
This glossary is for small business owners. The definitions are written with their requirements in mind. More detailed definitions can be found in accounting textbooks or from an accounting professional. Xero does not provide accounting, tax, business or legal advice.